The Policy tab sits on the Macro Risk Scorecard between Credit and Liquidity and Outlook, and the module describes its coverage as monitoring Federal Reserve policy, Treasury yields, and CPI and inflation data, with interest rate forecasting and yield curve analysis. So the raw material for a policy rule comparison is in the module's scope. The comparison itself is something you assemble, and this article is about doing that rather than about a panel you can open.
The idea is old and simple. Write down a rule that says where a policy rate ought to sit given inflation and the state of the labour market, compute what the rule says today, and subtract the actual rate. The difference is a distance. It is not a forecast, and almost every bad use of this measure comes from treating a distance as a prediction.
The rule in one paragraph of arithmetic
The standard form has four terms and you can do it on a phone. Start with an estimate of the neutral real rate, the rate that neither stimulates nor restrains. Add current inflation, which converts it to a nominal rate. Then add a fraction, conventionally a half, of the amount by which inflation exceeds the central bank's target. Then add a fraction, again conventionally a half, of the output gap, which in practice most people proxy with how far unemployment sits from its longer run level.
That is it. Two economic readings, two policy parameters, one estimate of neutral. The output is a suggested nominal policy rate, and the gap is that number minus the rate actually in force.
The interpretation is deliberately narrow. A rule rate above the actual rate says policy is looser than the rule would have it. Below, and policy is tighter than the rule. That is a statement about the present configuration and nothing more.
Why I am not printing a number for you
The honest reason there is no headline figure in this article is that the figure is mostly a function of choices you have not made yet, and quoting one would give you false confidence in somebody else's assumptions.
Start with the neutral real rate. Nobody observes it. It is estimated, the estimates differ, and they get revised. Move your assumption by one percentage point and the rule rate moves by one percentage point, which is often larger than the gap you were trying to measure.
Then the inflation measure. Headline or core, which index, and over what window. A twelve month rate and a three month annualised rate can be a long way apart, and choosing between them changes the answer materially.
Then the coefficients. The convention is a half on each term, and it is a convention rather than a law. Put a higher weight on the inflation term and the rule becomes more hawkish by construction, without you having learned anything about the economy.
Then the output gap proxy. Estimates of the longer run unemployment level differ and are revised in the same way the neutral rate is.
Four choices, each individually reasonable, each worth a meaningful amount of the final gap. If somebody hands you a single number for the policy gap without telling you their four choices, the number is decoration. That is not a reason to skip the exercise. It is a reason to do it yourself, where you know what went in.
Computing your own version, and doing it twice
Ten minutes, once a month, on the same day.
- Write down the current policy rate, the current inflation reading on a measure you have chosen and will not change, and the current unemployment rate. All three are published and free.
- Fix your neutral real rate assumption, your inflation target, your assumed longer run unemployment level and your two coefficients. Write them at the top of the sheet. These are the numbers you are not allowed to adjust after seeing the result.
- Compute the rule rate and subtract the actual rate. Record the date and the gap.
- Then compute it again with a deliberately different neutral rate assumption, say one point higher and one point lower, and record those too.
That last step is the one that makes the exercise worth doing. You end up with a range instead of a point, and the width of the range tells you how much of what you are looking at is economics and how much is your own assumption. When the range straddles zero, the correct conclusion is that you cannot tell which side of the rule policy is on, and that conclusion is worth reaching explicitly rather than by accident.
Reading a distance without turning it into a prediction
Here is the discipline that separates useful from useless.
The gap tells you how far apart two things are today. It does not tell you that the gap will close, how fast it would close, or which side would move. A gap can close because the policy rate changes. It can equally close because inflation falls or the labour market shifts, which moves the rule rate towards the policy rate with nobody at the central bank doing anything at all. That second path is common and it is the one people forget when they read a large gap as a queued sequence of policy moves.
What the distance is good for is calibrating your reaction to news. If your own computation says policy is meaningfully looser than the rule, then a piece of news pointing towards tighter policy is consistent with where the rule already sits, and you should be less surprised by it. If policy is already tighter than the rule, the same news is a bigger deal. That is the whole benefit, and it is a real one, because most retail damage comes from being surprised into a decision.
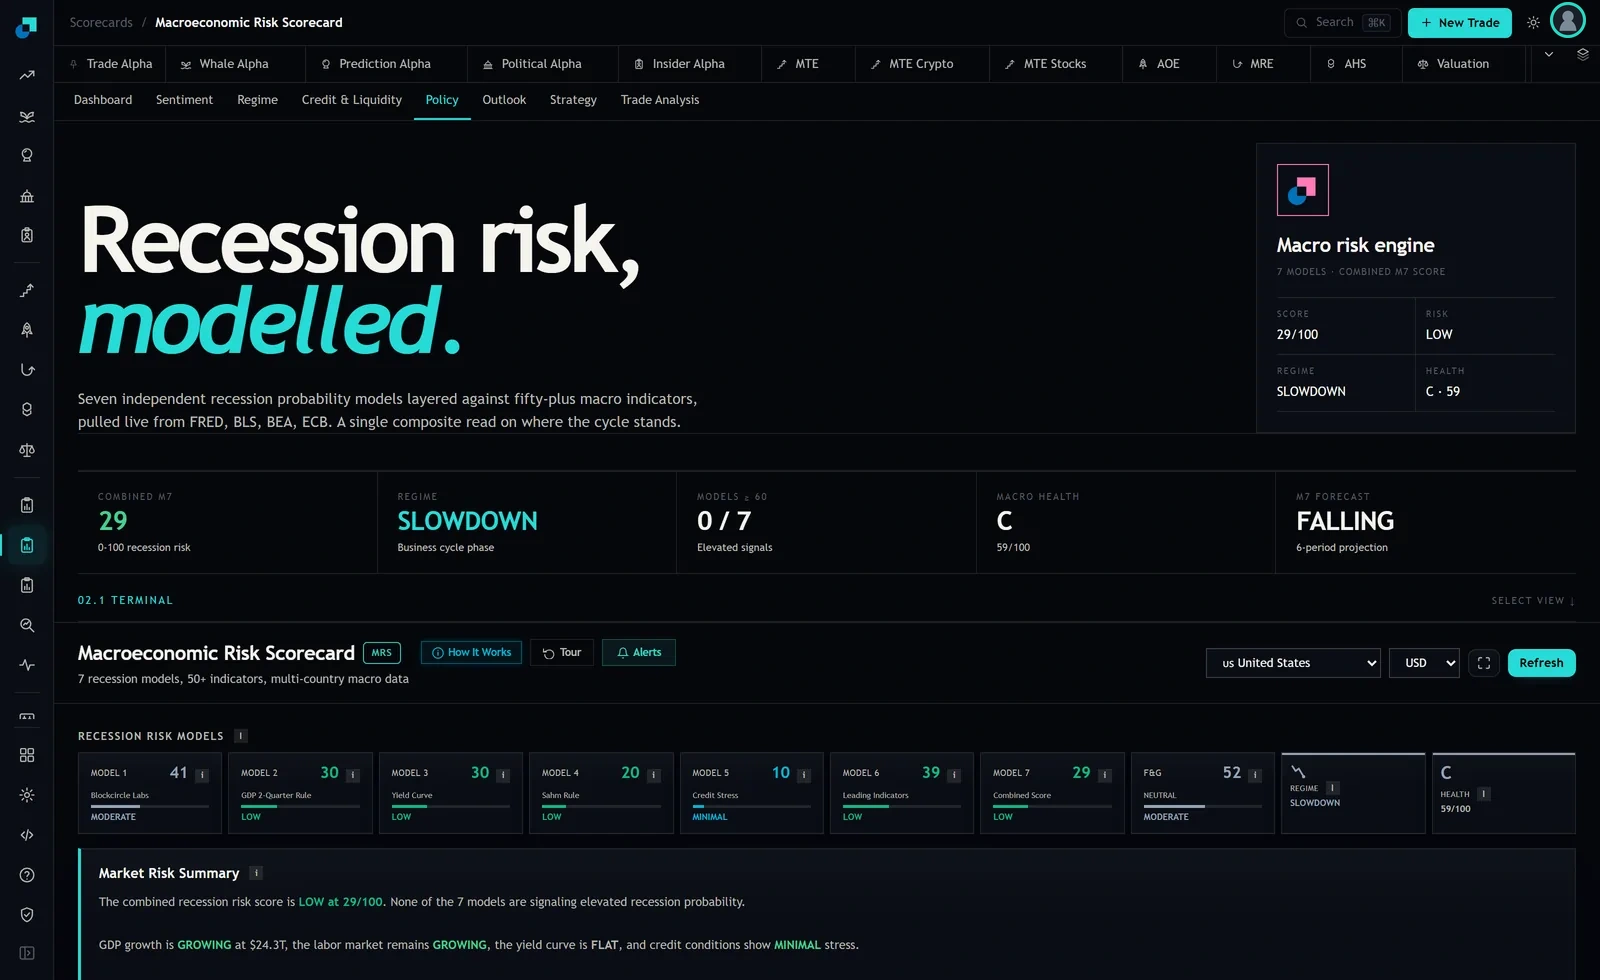
The scorecard's own framing supports reading these things as configuration rather than prophecy. The combined M7 score is presented as a 0 to 100 recession risk reading, currently 29 and labelled LOW, sitting beside a phase label of SLOWDOWN and a health grade of C at 59. Those are descriptions of a state. The tab labelled Outlook and the forecast tile reading FALLING, described as a 6-period projection with the period unit not spelled out on the tile, are separate objects that should not be quietly merged with your gap number into one story.
What the gap cannot see
Three things sit outside the rule entirely, and each of them can matter more than the gap in a given month.
The first is everything a central bank does that is not the policy rate. Balance sheet operations and the words in the statement both move financial conditions and neither appears in a four term formula. A period where the rate is unchanged and conditions tighten sharply is entirely possible and the gap will register none of it.
The second is financial stability. A rule computed from inflation and unemployment says nothing about whether something in the financial system is breaking, and when something is breaking that consideration dominates. The credit inputs on the scorecard are the better place to look for that, and today the Credit Stress model reads 10 and is tagged MINIMAL.
The third is that the rule has no opinion about lags. Policy set today acts on the economy over a period nobody can pin down precisely, which means a rule computed on today's readings is comparing an instrument that works slowly against data that describes the recent past. Anyone who tells you exactly how many months that lag runs to is quoting a range as though it were a constant.
Given all that, the useful posture for a retail portfolio is modest. The gap is one input into how surprised you should be, it costs ten minutes a month, and it should never be the reason for a large change in what you hold. If your own calculation swings your allocation, the calculation has been given more authority than four assumptions and two published statistics can carry.