A discounted cash flow model quietly assumes the company is still around to produce the cash flows. That assumption does more work than all the arithmetic stacked on top of it, and it is the one line nobody writes into the spreadsheet. I have built careful models on businesses that were fine operationally and still lost most of the equity value, because the recovery arrived one refinancing too late and the lenders got paid before I did.
So the sequence I use now is survival first, upside second. Four checks, roughly twenty minutes with the annual report open. If a name fails badly on any of them, I do not build the model at all, because the answer the model gives is not a share price, it is a share price conditional on an event I have not priced.
The order the four checks belong in
Order matters because the checks fail on different timescales and you want the fastest killer first.
Interest coverage is first. It tells you whether the business can pay the rent on its debt out of current operations. A company that cannot cover interest is consuming the balance sheet every quarter it stays open.
The maturity wall is second. Coverage can be fine and the company can still fail, because debt does not amortise politely, it comes due in lumps. What matters is when the lumps land and how large the nearest one is relative to what the business generates.
Cash runway is third, and it only binds for companies burning cash. For a profitable business it is a formality. For a loss-maker it is the whole analysis.
The current ratio trend is fourth and it is the weakest of the four on its own, which is why it goes last. As a trend across four periods rather than a single reading it picks up working capital stress that the other three miss.
What a fundamentals score of 50 does not tell you
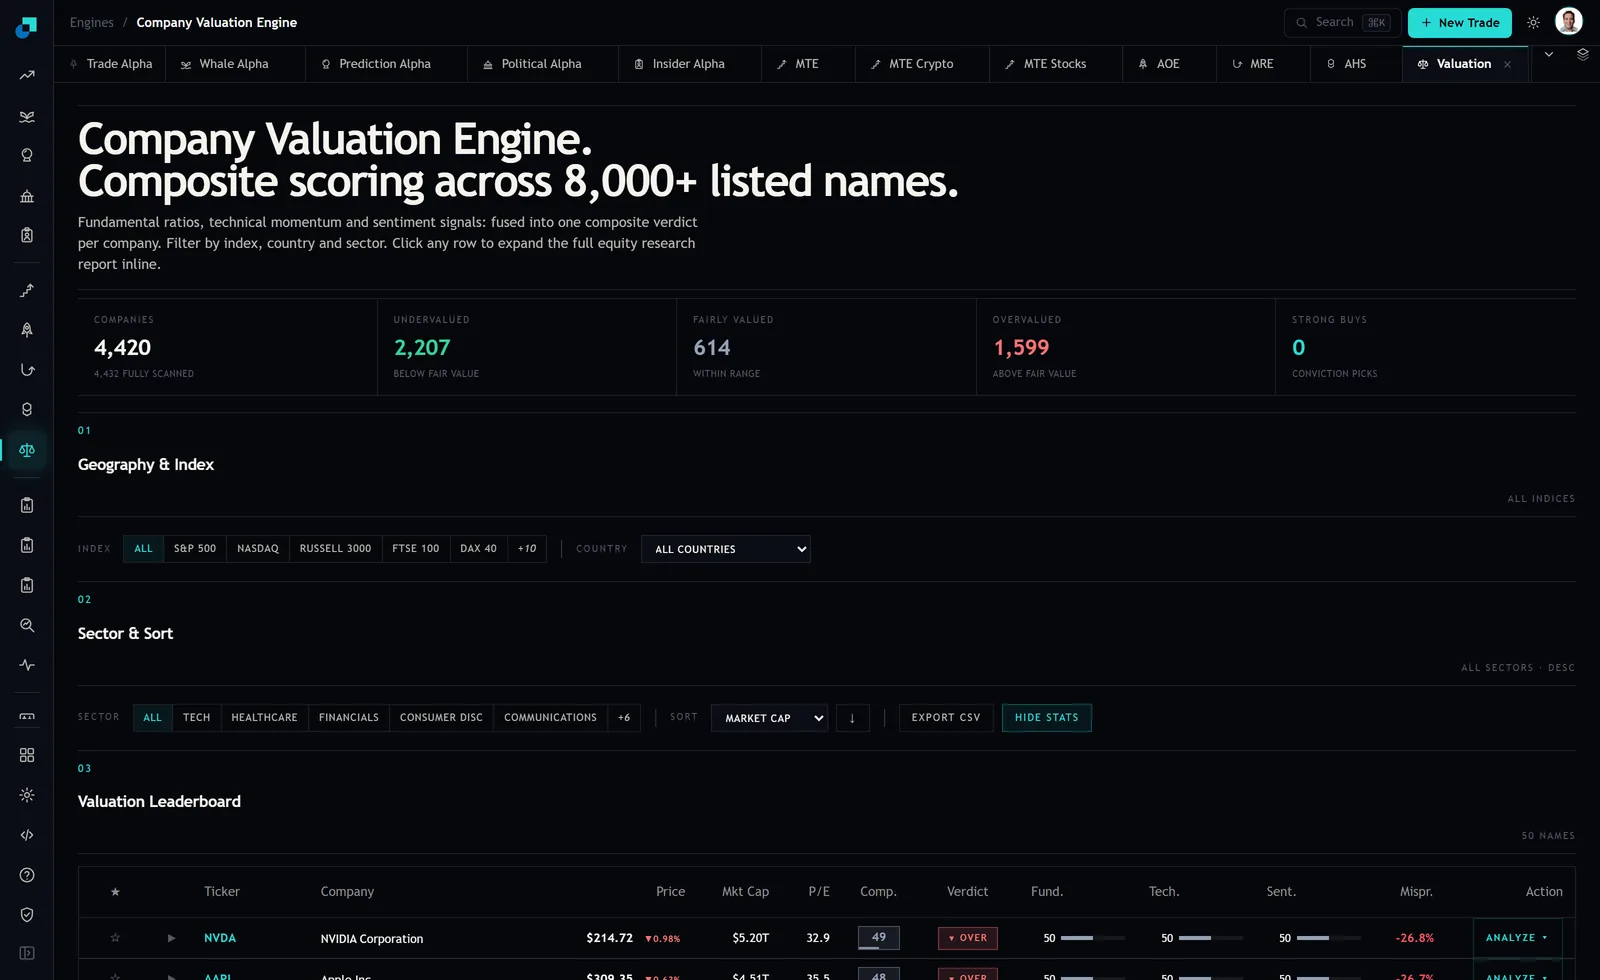
That is the honest shape of the tool. Read across the leaderboard and you get Ticker, Company, Price, Mkt Cap, P/E, a composite, a verdict, three sub-scores, a mispricing percentage and an action control. Twelve columns, and not one of them is a balance sheet. The header counters at capture read 4,420 companies with 4,432 fully scanned, split 2,207 below fair value, 614 within range and 1,599 above, and every one of those verdicts is a statement about price against value, not about survival.
Which is fine, as long as you know it. The board is a shortlisting instrument. It takes a universe you could never read by hand and hands you fifty rows. The four checks below are what you do to those rows before anything else, and they come out of the filings, not out of the screen. Concretely, that means the income statement for interest expense, the debt footnote for the maturity table, and the cash flow statement for the burn. Open those three and you have everything the checks need.
Interest coverage and the maturity wall, with numbers
Interest coverage is operating profit divided by interest expense. Both figures are on the face of the statements. There are more refined versions using cash interest paid from the cash flow statement, and they are worth using once the crude version flags something, but the crude version catches almost everything.
Above about six times, stop thinking about it. Between three and six, note it and move on. Below three, the business has no room for a bad year, because a thirty percent decline in operating profit at three times coverage puts you at two, and at two times coverage the lenders start having opinions. Below one and a half, treat the equity as an option rather than a claim on cash flows, and size it accordingly if you buy it at all.
Then the maturity wall, which is the check most retail investors skip and the one that actually does the damage. In the debt footnote there is a table of principal repayments by year. Read the next three years. What you want to know is the largest single year's maturity as a multiple of annual free cash flow.
Round numbers. A company generates 100 of free cash flow a year, carries 900 of debt, and covers interest four times. Comfortable, on the face of it. Then the maturity table shows 600 of that 900 falling due in eighteen months. The company cannot repay it from operations, so it has to refinance, and whether it can refinance depends on credit markets at that moment rather than on anything in the business. You are no longer underwriting a company. You are underwriting the state of the high yield market in eighteen months, which is not a thing I can forecast and probably not a thing you can either.
The version of this that is fine is the same company with 150 due next year and the rest spread past 2030. Same total debt, completely different risk.
Cash runway and the current ratio trend
Runway is cash and equivalents divided by the quarterly cash burn, where burn is operating cash flow minus capital expenditure when that number is negative. Express it in quarters, not months, because quarters are the unit companies report in.
Under four quarters of runway, dilution is the base case rather than a risk, and you should model the share count going up rather than hoping it does not. Four to eight quarters means a raise is likely but the company has some choice about timing and terms, which is worth a great deal. Beyond eight quarters, the runway is not the binding constraint and you can go back to arguing about the business.
Two adjustments keep this honest. Undrawn revolver capacity counts toward liquidity, but only if the facility has no maintenance covenant tightening in the window, and the footnotes will tell you whether it does. And restricted cash does not count at all, however prominently it appears in the total.
For the current ratio, current assets over current liabilities, the level is close to meaningless across industries. A supermarket runs below one by design because it sells for cash and pays suppliers later. The trend is what carries information. Pull four consecutive year end readings, and if the ratio has fallen in three of them while revenue was flat or growing, working capital is being consumed to fund operations. That is the same signal a lengthening receivable cycle gives, arriving through a different door.
Where a failed check changes the position, not just the model
The point of doing this first is that the outcome is a decision about whether to proceed, and it has three settings.
Pass all four, and the survival question is closed. Build the model, argue about growth and margins, and do not carry a nagging solvency worry into every future decision on the name.
Fail one check, and the model is still worth building, but the failed check becomes an explicit condition attached to the thesis. If the failure is a maturity wall, then the refinancing is the event you monitor and the date is in your calendar, and a successful refinancing on reasonable terms is a genuine piece of good news rather than a non-event. Write the condition down next to the position, because in six months you will remember that you liked the company and not why you were nervous.
Fail two or more, and skip the name. Not because it cannot work out, but because the payoff has stopped being a valuation question. You are now expressing a view on credit markets, on a lender group's patience, and on management's ability to raise money in bad conditions, and a fair value estimate has nothing useful to say about any of those. There are 4,420 companies on that board and no shortage of situations where the arithmetic you are good at is the arithmetic that decides the outcome.