Growth is not a virtue. It is a use of money, and like any use of money it is worth doing when the return beats the cost and worth stopping when it does not. A company growing revenue at twenty percent while earning six percent on the capital it deploys to do so is running a machine that converts your money into less money, faster each year.
This is the single most useful idea in equity valuation and it collapses to one subtraction. Return on invested capital minus weighted average cost of capital. If that spread is positive, growth creates value and a premium is earned. If it is negative, growth destroys value and every point of extra growth makes the company worth less. If it is roughly zero, growth is a treadmill and the business is worth about its current earnings capitalised, no more.
The subtraction, and why both numbers are approximate
Return on invested capital is after-tax operating profit divided by the capital in the business. Take operating profit, multiply by one minus the tax rate, and divide by total debt plus shareholders equity minus cash. Cash comes out because idle cash is not being used to generate the operating profit and leaving it in makes an efficient business look mediocre.
Cost of capital is harder and you should be honest that your estimate is crude. A workable version for a private investor is to blend the after-tax interest rate the company actually pays on its debt with a required return on equity of somewhere between eight and eleven percent, weighted by the size of each. You will not get this right to a decimal. That is fine, because the decision rule below only needs the answer to the nearest few points.
The important discipline is to carry the uncertainty forward rather than pretending it away. If your cost of capital estimate is nine percent plus or minus two, then a company earning ten percent is not clearly above its cost of capital. It is inside your error band, and inside the error band the correct answer is that you do not know.
The rule, written down before you look at a price
Here is the rule I use, and the reason it is written down is that a rule invented after seeing a price is a rationalisation.
Spread under two points, including anything negative. Pay no growth premium at all. Value the business on current earnings with no assumed expansion, because expansion at this spread adds nothing you should pay for in advance. If the company is growing anyway, the growth is free optionality and you have not paid for it.
Spread between two and six points. A modest premium is defensible, and modest means a multiple somewhat above the no-growth case rather than a multiple that assumes a decade of compounding. The reason to stay restrained here is that a four point spread is fragile. One competitor with cheaper capital, one input cost cycle, one pricing change, and it is gone.
Spread above six points and demonstrably durable for at least five years of history. This is where a real premium is earned, and where paying up is a defensible decision rather than a hopeful one. Durability is doing most of the work in that sentence. A six point spread that appeared two years ago is a cycle, not a moat.
Two rows, one point apart, for opposite reasons
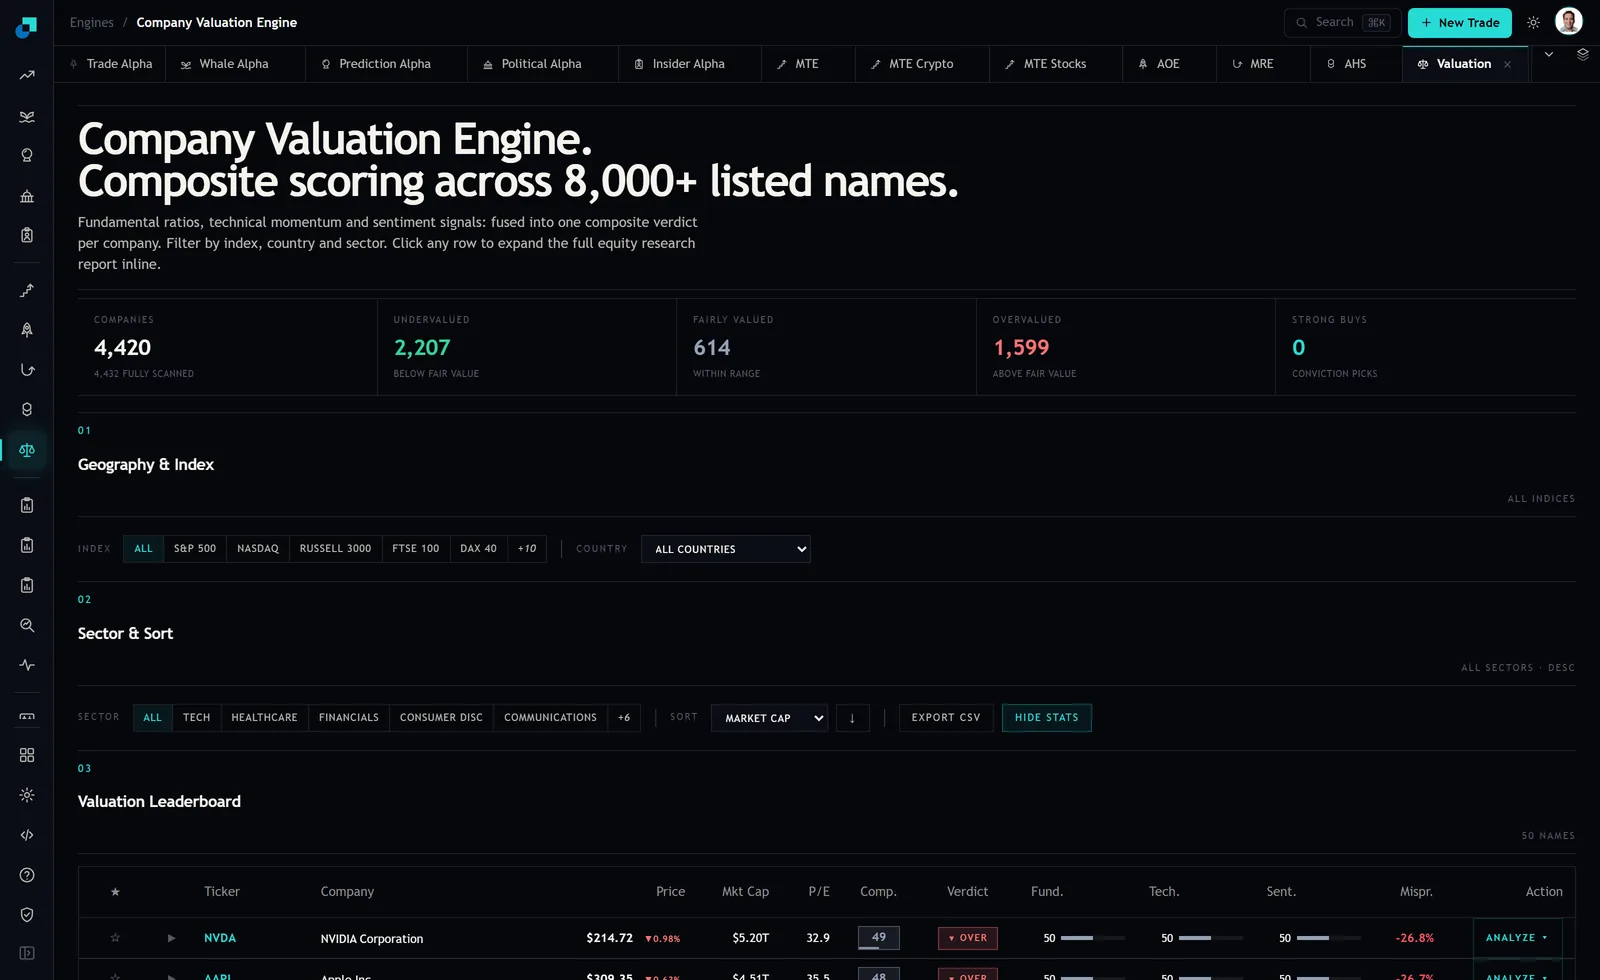
That one point gap is the practical problem with any blended score, and it is not a criticism of the blend. A composite is doing a genuinely hard job, compressing several dimensions into one orderable number across a universe that read 4,420 companies at capture. Compression loses information by definition. What it loses here is exactly the thing the rule above needs.
Two companies can sit a point apart on a composite where one earns fifteen percent on capital against a nine percent cost and grows at six, and the other earns eight percent against the same nine and grows at twenty. The first should trade at a premium and the second should not. Nothing in a single blended figure separates them, and nothing on this board separates them either, because there is no return on capital column and no cost of capital column. Those are not oversights, they are calculations that require inputs the screen does not carry.
Working the two cases through in dollars
Made-up numbers, kept round. Both companies earn 100 of after-tax operating profit today.
Company A earns fifteen percent on capital against a nine percent cost, so a six point spread, and grows at six percent by reinvesting forty percent of profit. Every dollar reinvested comes back as fifteen cents a year against a nine cent cost. The growth is worth paying for and a premium multiple is the correct response.
Company B earns eight percent against the same nine percent cost, so a negative one point spread, and grows at twenty percent by reinvesting almost everything. Every dollar it retains earns eight cents against a nine cent cost. It is growing fast and shrinking your claim. The correct multiple is lower than the no-growth case, not higher, which is the part that feels wrong and is arithmetically true.
If you own 5,000 dollars of Company B on a growth thesis, the reinvestment is not building your position. Over five years of retaining nearly all profit at a one point negative spread, the value transferred away is small each year and steady, and it is entirely invisible in the revenue line you were watching. That invisibility is the whole hazard. Revenue growth is the most prominently reported number a company produces and it is silent on whether the growth was worth having.
When the rule says do nothing
The rule fails in three places and it is better to know them than to apply it blindly.
Financial companies first. Return on invested capital is not meaningful for banks and insurers, where leverage is the business rather than a financing choice. Use return on equity against a cost of equity there, and do not compare the result to an industrial name.
Second, companies whose capital base is understated because their real asset was expensed rather than capitalised. Heavy research spenders and brand-driven businesses show flattering returns on a capital base that is missing the thing they actually built. If you have not adjusted for that, a fifteen percent return may be a nine percent return wearing a costume.
Third, the trough of a cycle. A cyclical business at the bottom shows a compressed spread that will widen without management doing anything at all. Take the average spread across a full cycle where you can identify one, and if you cannot identify one, treat the current spread as uninformative rather than as bad news.
The check worth running this week takes fifteen minutes on your largest holding. Compute the spread from the last annual report, write it on one line alongside the growth rate you have been assuming, and see which band of the rule the name lands in. If the spread is inside your error band and the multiple you paid assumes years of compounding, you are not wrong yet. You are simply holding a position whose thesis has never been stated in a form that could be checked, and stating it is free.