The sector heatmap is presented as a flow report. Here is what politicians bought and sold by sector over the selected window, direction labelled, notional attached. Read that way it is interesting and does nothing for you.
Read backwards it is something more useful. If you are running a sleeve that replicates disclosed political trading in any systematic way, this view is a forecast of the sector weights your book is going to have. Not a description of what other people did. A projection of where your own capital ends up if the constraint set does not stop it. And on the capture in front of me, the projection breaches a normal diversified mandate before the first trade goes on.
The arithmetic on one window
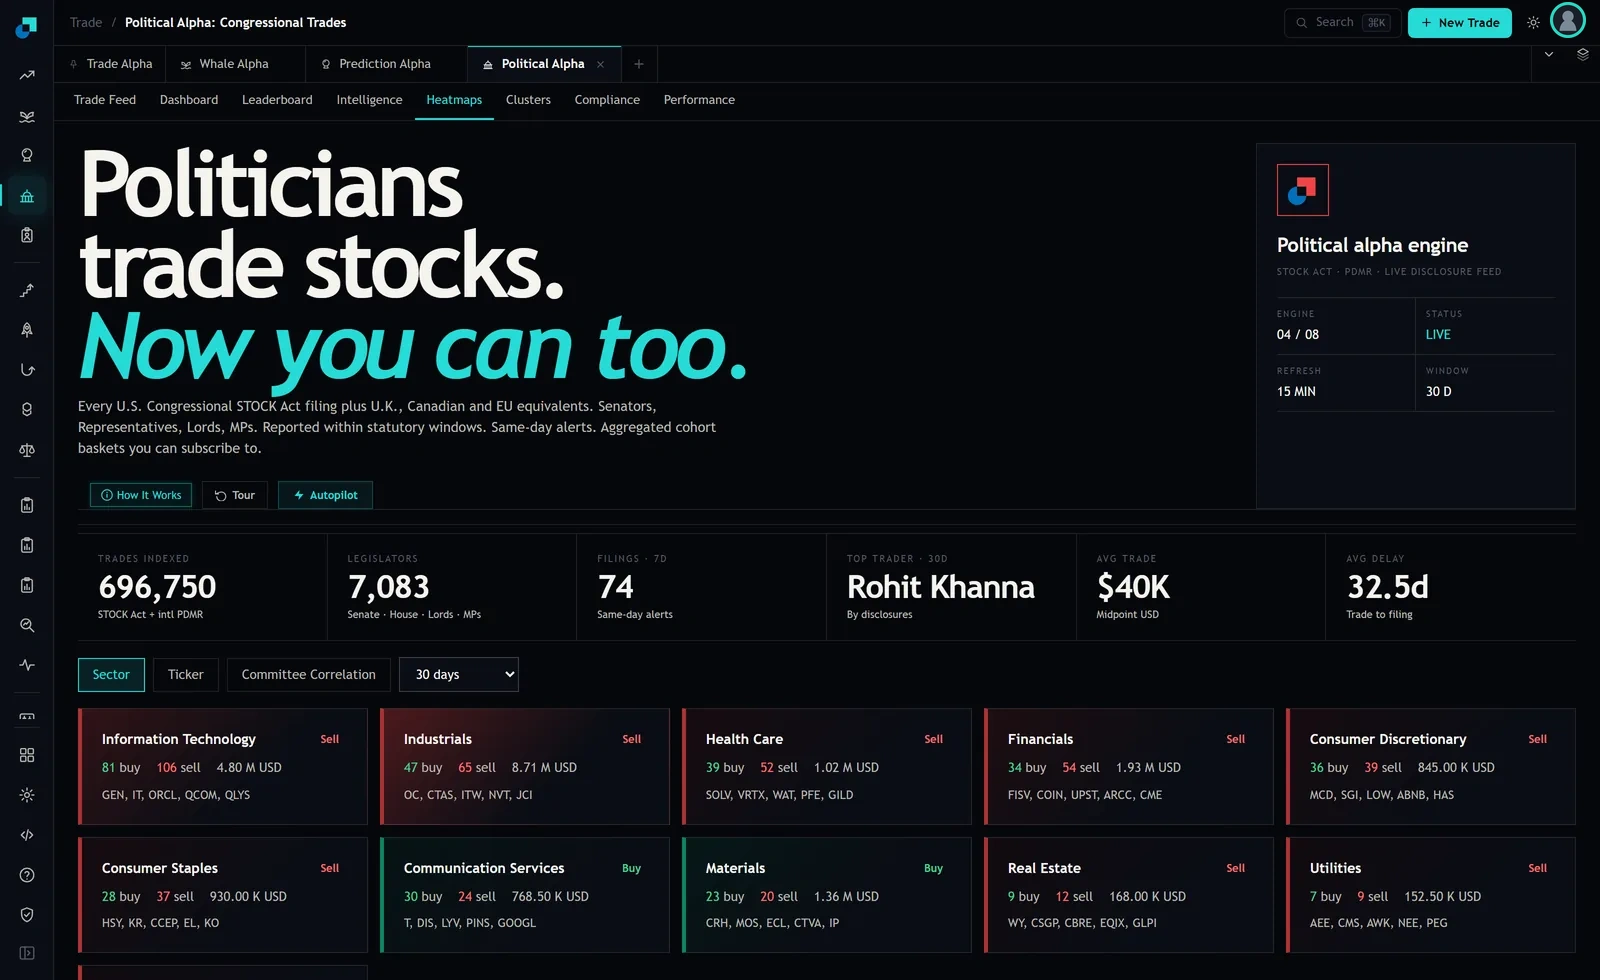
The Heatmaps tab carries three sub-tabs, Sector, Ticker and Committee Correlation, with a window selector reading 30 days. The module documents the sector view as aggregate net flow by GICS sector across all politicians. Each tile carries a direction label, a buy count, a sell count, a notional in USD and five leading tickers.
Ten tiles were visible on my capture. Taking the notionals as they read: Industrials 8.71 M, Information Technology 4.80 M, Financials 1.93 M, Materials 1.36 M, Health Care 1.02 M, Consumer Staples 930 K, Consumer Discretionary 845 K, Communication Services 768.5 K, Real Estate 168 K, Utilities 152.5 K. That sums to roughly 20.7 M USD across the window.
Industrials alone is 42 percent of that. Industrials plus Information Technology is 65 percent. The top three sectors are 75 percent. The bottom two, Real Estate and Utilities together, are 1.5 percent.
Before going further, one caveat about the reading. Ten tiles were visible in my viewport. GICS carries more sectors than that, so a tile may well sit below the fold. Scroll before you conclude that a sector had no flow, and if you are automating this, take the count of tiles from the data rather than from what fits on a screen.
Two replication rules produce two different overweights
This is the observation that makes the view worth reading as a risk map rather than as news.
Count the transactions instead of the notional. Information Technology carries 187 trades, 81 buys and 106 sells. Industrials carries 112. Health Care 91, Financials 88, Consumer Discretionary 75, Consumer Staples 65, Communication Services 54, Materials 43, Real Estate 21, Utilities 16. Around 752 transactions in total across the ten tiles, of which 334 are buys and 418 are sells.
Now put the two rankings side by side. On notional, Industrials leads at 42 percent and Information Technology is second at 23. On count, Information Technology leads at 25 percent and Industrials is second at 15. The order flips, and the magnitude of the leading position roughly halves.
That means the replication rule, which most desks treat as an implementation detail, is the dominant determinant of the sleeve's largest sector exposure. An equal-weight-per-signal book, the simplest and most common construction, concentrates in Information Technology because that is where the transaction count is. A notional-proportional book concentrates in Industrials at a weight no diversified mandate is going to accept. Same data, same window, same signal, two different concentration profiles and two different breaches.
There is a further wrinkle on the notional side that argues against using it naively. Disclosed sizes are brackets rather than amounts, which is why the dashboard reports average trade size as $40K under the explicit subtitle "Midpoint USD". A notional-weighted replication is therefore weighting by a midpoint estimate of a bracketed range, and the sectors that show large notional are the ones where a handful of high-bracket filings landed. That is a thinner basis for a 42 percent sector weight than the number's precision suggests.
A long-only follower ends up in two sectors
Look at the direction labels. On this capture eight of the ten tiles carry Sell. Only Communication Services, at 30 buy against 24 sell, and Materials, at 23 against 20, carry Buy. Every tile labelled Sell has more sells than buys and both Buy tiles have more buys than sells, which is consistent with a count-based label, though the tile does not state the rule.
Follow that mechanically with a long-only sleeve that takes net-buy sectors and you have a two-sector book. Communication Services and Materials, 768.5 K and 1.36 M of notional respectively, together under 11 percent of the window's flow. That is not a diversified sleeve, it is a pair trade with extra steps, and it arrives that way not because anyone chose it but because the window happened to be net-selling.
The generalisable point is that a net-direction filter on top of a sector aggregate produces violently unstable breadth. In a net-buying window you might qualify eight sectors. In this one you qualify two. A sleeve whose effective breadth swings by a factor of four between windows has a risk profile that no static cap set describes, and the fix is to constrain breadth directly, with a minimum sector count and a maximum single-sector weight, rather than to let the filter decide.
Where the cap binds and what happens to the excess
Set the cap first and derive the behaviour, rather than discovering the behaviour at the first rebalance.
Take a diversified mandate with a single-sector limit somewhere in the low twenties of percent, which is a common shape. A notional-proportional replication of this window arrives at 42 percent in Industrials. The cap binds immediately and by a wide margin, roughly twenty points, which means the constraint rather than the signal is determining half of your largest position.
The decision nobody makes explicitly is what happens to the excess, and there are three options with three different costs. Redistribute pro rata across uncapped sectors and your book drifts toward sectors the signal was not pointing at, which quietly turns a political-flow sleeve into something closer to equal weight. Hold the excess in cash and you take a drag proportional to the size of the breach, which in this window is substantial. Scale the entire sleeve down until the largest sector fits under the cap and you preserve the relative shape of the signal at the cost of reducing the sleeve's contribution to the fund.
I would take the third and report the scaling factor as a monthly number, because it is the one option where the book still expresses the signal you said you were running and the cost is visible in a single figure rather than smeared across sector weights. Whichever you choose, write it into the sleeve's construction document, because the choice materially changes what the sleeve is and it should not be made implicitly by whoever coded the rebalancer.
Sector caps do not constrain the exposure most likely to hurt
A sector cap is necessary and it is not sufficient, and the tickers on the tiles show why.
Each tile lists five leading names. The Financials tile lists FISV, COIN, UPST, ARCC and CME. Those are five constituents of one GICS sector with wildly different factor profiles, and a sleeve that fills a Financials allocation from the high-beta end of that list carries a very different risk than one filling it from the exchange and credit end, while both sit identically inside the sector cap. The Information Technology tile lists GEN, IT, ORCL, QCOM and QLYS, again spanning very different size and volatility profiles.
So pair the sector cap with two factor constraints. Cap active beta against the sleeve's benchmark, and cap the active size tilt, because within-sector name selection is where both will move without touching a sector limit. If your risk system produces a factor decomposition, run the projected book through it before the rebalance rather than after, using the heatmap's tile weights as the input.
That is the shape of the whole exercise. Once a month, before you trade, pull the sector view at the window that matches your rebalance frequency, project the sleeve weights under your actual replication rule, and compare them to the cap set and the factor limits. The 30 day window on the selector is the right length for a monthly rebalance and the wrong length for a quarterly one, and reading a window shorter than your holding period gives you a noisier forecast than the book you will actually hold. Match them, and the map stops being a flow report and starts being a pre-trade compliance check that costs five minutes.