Discounted cash flow on a company with a broken balance sheet produces a number, and the number is wrong in a specific and predictable way. It is wrong because it treats the equity as a residual claim on a continuing enterprise, when what the equity has actually become is a levered bet on whether enterprise value at the debt maturity exceeds the face amount of the debt.
The structural framing is old and well understood. Equity is a call option on the assets of the firm, struck at the face value of the debt, expiring at the debt maturity. On a lightly levered company that framing is technically true and practically irrelevant, because the option is so deep in the money that its delta is one and the option value equals the intrinsic value. On a company with net leverage in the mid single digits and a maturity wall inside three years, the framing stops being an abstraction and starts being the only description that fits the price behaviour.
What the framing actually asserts
Four inputs, and it is worth being clear about which of them you can observe and which you are inventing.
The underlying is enterprise value, meaning the value of the whole business independent of how it is financed. You observe a market price for the equity and, if you are fortunate, a market price for the debt, and you back into enterprise value from those. This is the least contentious input.
The strike is the face value of the debt at maturity, not its market value. A bond trading at sixty cents still has to be repaid at par or refinanced at par, and the discount tells you what the market thinks of that, not what the company owes.
The expiry is the weighted average maturity of the debt stack, and this is where most implementations get lazy. A company with a revolver maturing in eighteen months and bonds in seven years does not have a four year option. It has an eighteen month option, because the revolver maturity is the date on which the outcome is decided. Take the nearest material maturity, not the average.
Asset volatility is the input you cannot observe and the one the answer is most sensitive to. Equity volatility is observable and it is not the same thing. On a highly levered company, equity volatility is asset volatility geared up by the capital structure, so plugging observed equity volatility into the model overstates asset volatility badly, which inflates the option value, which flatters the equity. Solve for asset volatility iteratively so that the model's implied equity volatility matches the observed one, or estimate it from a sector peer with a clean balance sheet and accept the error. Doing neither is the most common way this framing gets misused to justify a position.
The screen bucket where these names accumulate
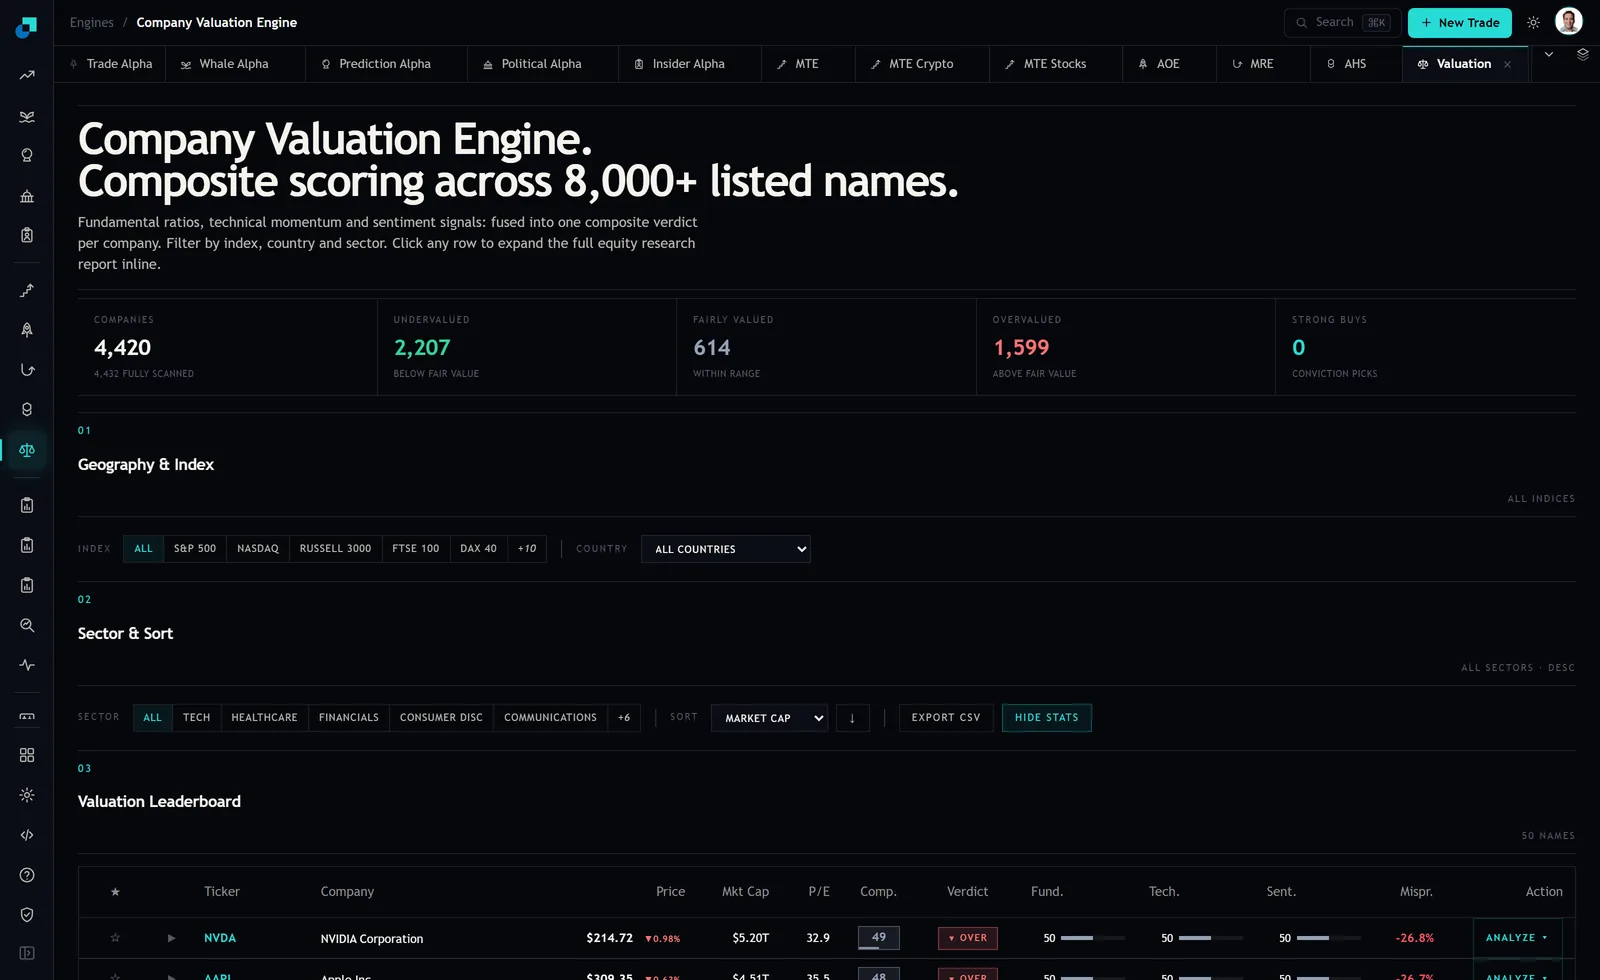
This is the practical reason a distress screen has to sit downstream of a valuation screen rather than being taken from it. The board is a good breadth tool across a large universe and its own method is internally consistent, but no composite verdict is going to distinguish a cheap solvent business from a levered call option, because the two look identical on a price-based discount measure. The filter that separates them is leverage and maturity profile, and neither is a column on this view. Export the population, join it to a debt stack, and the distressed sleeve identifies itself.
What the framing changes about size
This is where the exercise earns its cost, because the sizing implication is sharper than the valuation implication.
An equity valued as a deep out of the money call has a delta well below one, sometimes below a quarter. That means a ten percent move in enterprise value produces a much larger percentage move in the equity, in both directions, and the convexity is real rather than a modelling artefact. Sizing that position as though it were an equity with a beta near one understates the risk contribution by a multiple, and the standard risk system will not catch it because the historical volatility of a name that has only recently become distressed does not yet reflect the new capital structure.
The defensible sizing rule is to work backwards from loss rather than forwards from conviction. Take the probability of the option expiring worthless implied by your own model, apply it to the full position, and require that the probability-weighted loss stays inside whatever single-name loss budget the mandate carries. On a name where the model says forty percent chance of zero, the maximum defensible size is far smaller than the analyst's conviction will suggest, and that gap is the entire point of computing it.
Two further constraints belong in the same calculation. Rescue financing dilutes the existing equity heavily and is the most likely path to a non-zero but very poor outcome, so the model's binary payoff understates the middle of the distribution. And covenant acceleration can bring the effective expiry forward without warning, which shortens the option and reduces its value discontinuously.
The inputs that will be wrong and what to do about it
Capital structure complexity defeats the simple version. A stack with secured and unsecured tranches, structural subordination across subsidiaries, and preferred equity is not one strike, it is a series of them, and the common equity is a call spread rather than a call. Model the tranches separately or state plainly that the single-strike version is an approximation and by how much it could be off.
Value leakage during distress is invisible to the model. A company that is not paying suppliers, deferring maintenance, and losing its best staff is not preserving enterprise value while the clock runs. The model assumes the underlying follows a process. In reality the underlying decays because the firm is distressed, and the decay is not in the volatility parameter.
Recovery assumptions cut both ways. The framing assumes equity gets nothing below the strike, which is a good approximation and not always true, since equity holders occasionally extract something in a negotiated restructuring purely because their consent speeds the process. Treat that as an unmodelled upside rather than building it in.
Documenting it before the outcome is known
The reason to write this up properly is that a distressed equity position has a materially higher chance of going to zero than anything else in the book, and the review after it does is entirely determined by what was written before.
The file needs four things, recorded at initiation. The implied probability of expiring worthless from the model. The asset volatility used and how it was derived. The maturity treated as the expiry and why that date was chosen over the others in the stack. And the maximum size the loss budget permitted, alongside the size actually taken.
With those four lines, a position that goes to zero is a documented probabilistic bet that resolved against you, and the review is about whether the inputs were reasonable at the time. Without them, the same position is an analyst who liked a cheap stock, and no amount of subsequent explanation converts one into the other.