The Bank of Japan reports in yen. Your chart is in dollars. That single sentence is responsible for more wrong conclusions about Japanese liquidity than any actual policy decision, because it means the line you are looking at is two different series multiplied together, and only one of them has anything to do with the Bank of Japan. When that line drops fifteen percent in a quarter, your first question should not be what the BoJ did. It should be what the yen did.
The currency selector is where the problem lives
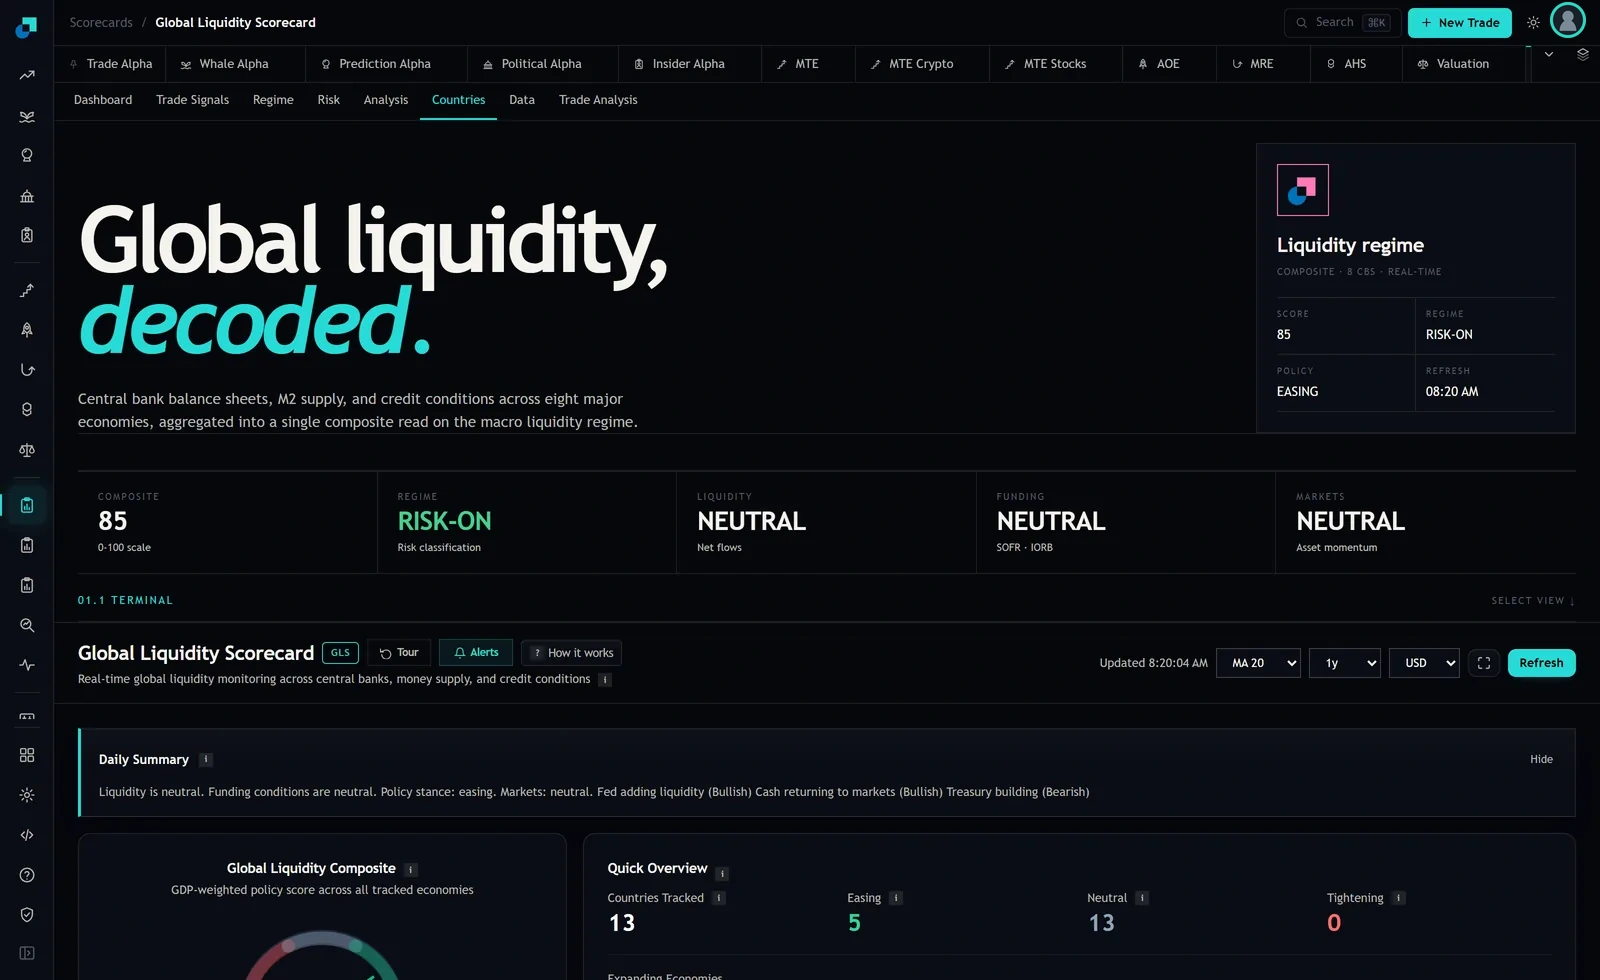
Look at the toolbar on the Global Liquidity Scorecard, along the row that starts with the module name. There are three selectors. One reads MA 20, which is a smoothing choice. One reads 1y, which is a window choice. The third reads USD.
That third one is not cosmetic. It decides the unit every non-dollar central bank in the composite is expressed in. The module tracks eight institutions, being the Fed, ECB, Bank of Japan, People's Bank of China, Bank of England, Swiss National Bank, Bank of Canada and Reserve Bank of Australia. Seven of those eight report in something other than dollars. For a global aggregate to exist at all, seven of them have to be converted, and conversion means multiplying by an exchange rate that moves for its own reasons.
Japan is where this bites hardest, because the yen has been capable of moving a long way in a short time, and because the BoJ's balance sheet is large relative to its economy, so the Japan contribution to any aggregate is meaningful. A big number multiplied by a volatile rate produces a volatile line.
The arithmetic, with round numbers so the shape is obvious
These are illustrative figures, not readings from anything. The point is the mechanic.
Say the BoJ holds 750 trillion yen of assets, and the exchange rate is 100 yen to the dollar. Converted, that is 7.5 trillion dollars. Now the yen weakens to 150 to the dollar and the BoJ does absolutely nothing. Same 750 trillion yen on the books. Converted, it is now 5 trillion dollars.
Your chart just showed a 33 percent collapse in Japanese liquidity. Nothing happened. No assets were sold, no programme ended, no policy meeting produced anything. A currency market moved and a division changed its answer.
Run it the other way and it is worse, because it is more flattering. A strengthening yen makes the Japan line rise while the BoJ is doing nothing or even shrinking its holdings. That version does not prompt anyone to check, because a rising liquidity line agrees with what most people would like to believe.
Three checks that separate translation from policy
None of these take longer than a couple of minutes, and doing all three costs less than one bad position.
Check the yen first. Pull up the dollar against the yen over the same window as the move you are trying to explain. If the currency moved by a similar percentage in the direction that would produce the change you see, you have almost certainly found your explanation and you can stop. This is not a sophisticated test. It is division, and it resolves the large majority of cases.
Check the shape of the move second. Balance sheet changes driven by policy tend to arrive as programmes. They accumulate over weeks and months and they are announced. Exchange rate driven moves are as fast as the currency market, which means they can be violent over days and they can fully reverse. A sharp move that retraces most of the way inside a month is nearly always translation. Policy does not un-happen.
Check the other lines third. If the Japan line moved and the euro area, Canada and Australia lines all moved the same way in the same week, the common factor is not eight separate central banks having simultaneous ideas. It is the dollar. A move in the dollar changes every converted line at once, which makes a broad simultaneous shift a signature of the numeraire rather than of monetary policy anywhere.
Which unit you should actually want
Here is the part people get backwards. Yen is not the correct answer and dollars is not the correct answer. The unit follows the question, and there are two different questions hiding behind the phrase Japanese liquidity.
If you are asking about credit conditions inside Japan, whether Japanese banks are flush, whether domestic borrowing is cheap, whether the domestic economy is being supported, then yen is the right unit. Japanese borrowers borrow in yen and Japanese banks fund in yen. Converting that into dollars only adds noise to a domestic question.
If you are asking how much global buying power Japan represents, then dollars is the right unit and the translation is not an artefact at all. It is the answer. A Japanese institution deciding whether to buy dollar assets genuinely does face a worse exchange rate when the yen is weak. The same pile of yen buys fewer dollar bonds. That is real, it affects real flows, and a chart that suppressed it would be hiding something you want to know.
So the honest position is that the USD-converted line is measuring a real thing, just not the thing most people think they are reading when they look at it. It is a measure of Japan's dollar purchasing power, not a measure of what the Bank of Japan has been doing.
The rules I use so this never costs me anything
Four habits, and the first one matters most.
Set the currency selector once and never mix. If your weekly log has three readings taken in USD and one taken in yen, your history is not a history, it is four unrelated numbers. Pick a base, write it at the top of the sheet, and leave it alone.
Log the setting with every reading. Date, composite, the selector values including the base currency, and the refresh stamp shown in the header. It takes four extra seconds and it means that in six months you can tell whether a change in your log is a change in the world or a change in your settings.
When the Japan line moves, check the yen before you form a view. Not after. Forming the view first and then checking is how you end up looking for reasons the policy interpretation might still be right.
And do not build a position on the translation effect itself unless you can state the mechanism you are trading. A weaker yen mechanically shrinking a dollar-denominated liquidity aggregate is arithmetic. Whether that arithmetic is a reason for any asset to be worth less is a separate claim, and it is one the chart does not make for you.