The check that has saved me the most money is also the least clever one in my process. Before I get interested in any low multiple, I ask whether the earnings underneath it are the earnings this business makes in a normal year, or the earnings it makes in its best year in a decade. For a large group of companies the answer is the second one, and for those companies a low multiple is not a discount, it is a warning that the cycle has run.
This is the value trap in its most common form, and it is not subtle once you have seen it. A chemicals producer at six times earnings after two years of record spreads. A homebuilder at seven times after a refinancing boom. A shipping company at four times when charter rates have tripled. In every case the price to earnings ratio is low because the denominator is temporarily enormous, and the denominator is about to fall much faster than the price.
Why the cheapest rows cluster where they do
The mechanism is arithmetic rather than psychological. Cyclical businesses carry high fixed costs, which means the swing between good and bad conditions lands almost entirely on the profit line. A twenty percent move in selling prices at a producer with a fifteen percent normal margin can take that margin to thirty percent or to nothing at all, because the cost base barely moves in either direction.
So at the top of a cycle these companies report earnings two or three times their own average, and any ratio built on trailing earnings divides by that inflated figure. They sink to the bottom of the multiple ranking as a group, all at once, which is itself the tell. When five names from one industry are all the cheapest things on your list, you have not found five bargains, you have found one industry at a peak.
The market is not being stupid about this. The low multiple reflects a shared expectation that the earnings do not persist. Where retail investors get hurt is in treating the multiple as though the market had missed something, when the multiple is the market's way of saying it has not.
Cyclicality is not one of the chips
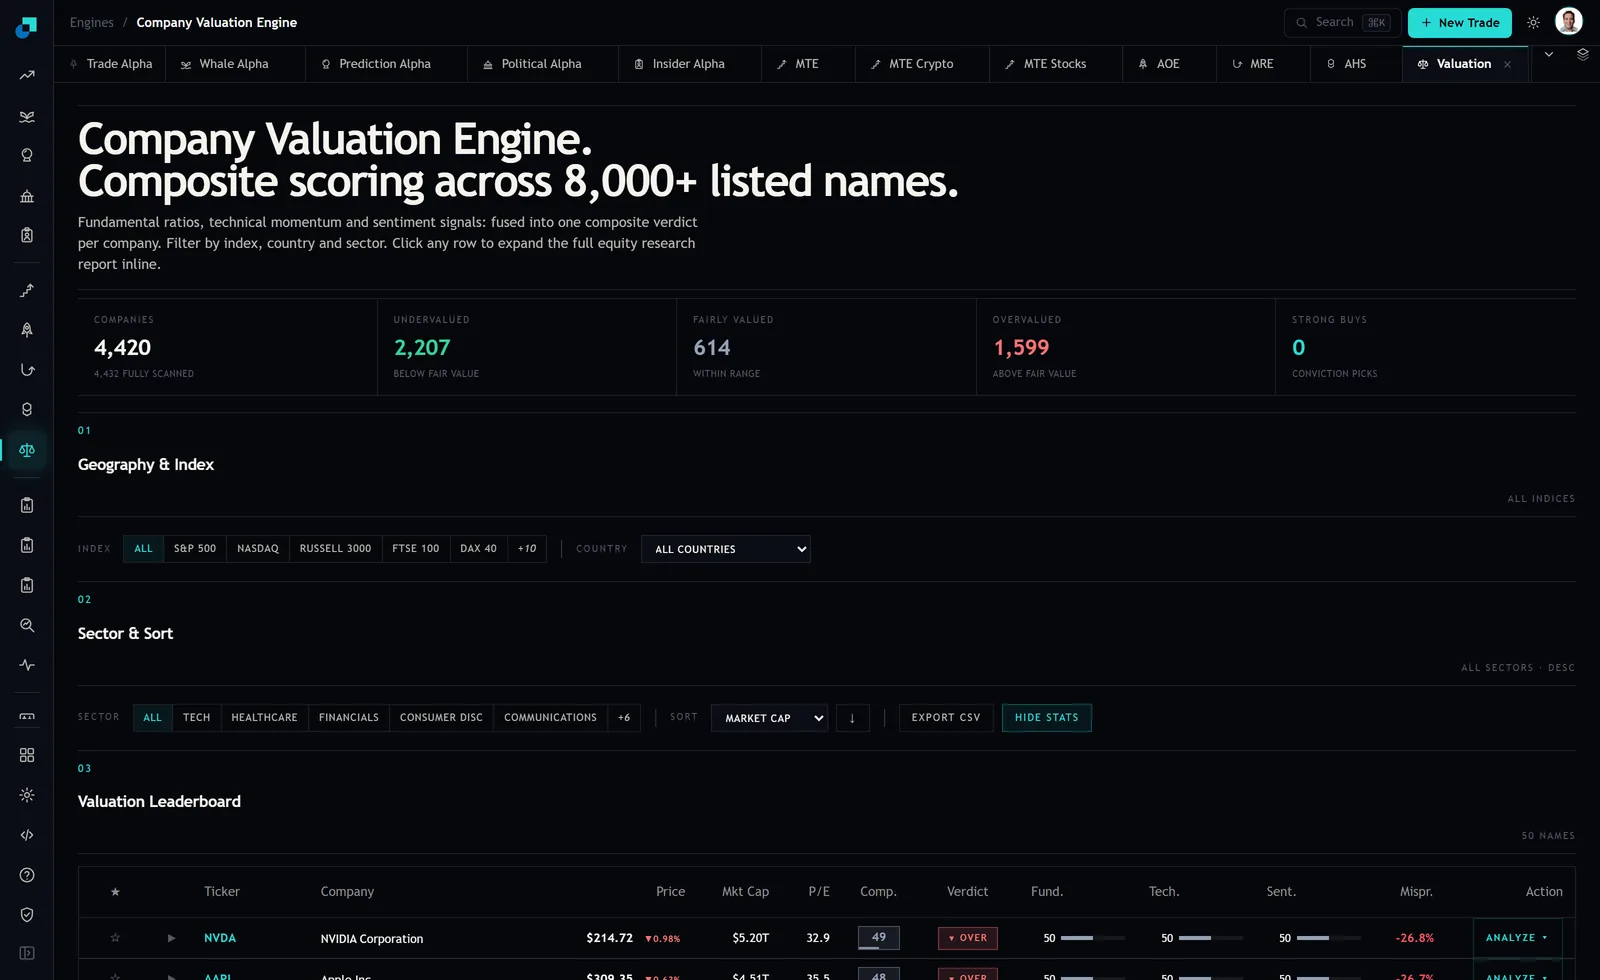
That is worth being precise about, because it changes how you use the tool. Filter to a sector, read down the P/E column, and what you get is a ranking on trailing earnings. It is a genuinely fast way to see a whole industry at once, which is more than most private investors can otherwise assemble. It is not a ranking on value, because nothing on the view has established whether any given denominator is normal.
The same applies to the verdict column and the mispricing percentage. Those are conclusions about price against a fair value estimate, and any fair value estimate anchored to recent earnings inherits the same problem at exactly the same moment. This is not a flaw peculiar to one platform. Every screen ever built has it, and the only fix is the one below.
The two-line fix
Replace the trailing margin with a mid-cycle margin and recompute. That is the entire method.
Pull ten years of revenue and operating profit for the company. Both are in the annual reports and both take about fifteen minutes to gather for a single name. Compute the operating margin for each year, and take the median rather than the mean, because the mean is dragged around by one or two extreme years.
Now take the current year's revenue and multiply it by that median margin. That is normalised operating profit. Apply the company's normal tax rate, subtract net interest, divide by the share count, and you have normalised earnings per share. Divide the current price by that figure and you have a normalised multiple.
Two refinements that are worth the extra minutes. Use current revenue rather than average revenue, because the company has probably grown, and averaging revenue would penalise it for existing longer. And if the company has made a large acquisition inside the window, the pre-deal years describe a different business, so either restate or start the window after the deal and accept a shorter history.
The ranking flips, in round numbers
Two companies, invented, kept simple. Company A is a cyclical producer with current revenue of 1,000 and current operating profit of 280, so a twenty eight percent margin. Its ten year median margin is eleven percent. Company B is a mundane industrial with revenue of 1,000, current operating profit of 120, and a ten year median margin of eleven and a half percent, which is to say it earns roughly the same in every year.
On trailing figures A looks like the better business by a wide margin and, at any given price, much the cheaper of the two. Suppose both trade on eight times trailing operating profit. A is priced at 2,240 and B at 960.
Normalise. A at its median margin makes 110 on today's revenue, so the market is paying 2,240 for a normal-year profit of 110, which is twenty times. B at its median makes 115, and the market is paying 960, which is eight and a third times. The cheap one and the expensive one have swapped places, and nothing about either company changed. Only the denominator did.
That gap is not a rounding difference or a matter of taste. It is the difference between paying twenty times and paying eight times for the same normal-year earning power, and it was invisible on the trailing figures both screens and brokers quote by default.
Where this applies and where it will mislead you
Run the check on any company whose profits depend on a price it does not set. Energy, mining, chemicals, shipping, steel, paper, autos, homebuilders, semiconductor equipment, capital goods with long order cycles, and lenders whose provisions swing with the credit cycle. If the annual margin series moves by more than about eight percentage points between its best and worst year, treat the name as cyclical regardless of which chip it sits under.
Three situations where the median margin is the wrong anchor and applying it mechanically will cost you.
A genuine structural change in the industry, meaning something you can name and size. Consolidation from a dozen producers to four changes pricing power permanently, and the low margin years before consolidation describe an industry structure that no longer exists. The test is whether you can state the change and roughly quantify it. If you cannot, it is a story, and stories at cycle peaks are abundant.
A company that has genuinely repositioned, having sold the commodity division and kept the specialty one. Its own history now describes a different mix. Use only the years since the change, even if that leaves you with four.
And the reverse case, which is the profitable one. A cyclical at the bottom of its cycle shows a terrifying multiple on trailing earnings, or none at all because it is loss-making, and it screens as the most expensive thing in the sector. Normalise it and it can be the cheapest. That asymmetry is the reason to do this exercise at all. The same two lines of arithmetic that stop you buying at the top are what let you look at a name everyone else's screen has thrown out at the bottom.
The practical version this week is short. For every low-multiple name on your list, find the ten year margin series before you find anything else. If the current margin is more than about one and a half times the median, the multiple you were looking at is not the multiple you are paying.