Any ranked list of companies is an assertion that the inputs are comparable. Most are not. Before an analyst forms a single view, five accounting choices have already decided a meaningful part of the ordering: how share-based pay is expensed, how leases sit on the balance sheet, whether development spending is capitalised, how pension obligations flow through the income statement, and which items were labelled non-recurring. Rank on EBITDA or on an earnings multiple without touching those, and you have produced a ranking of disclosure policy with a valuation label on it.
The answer is not more analyst judgement per name. It is a fixed adjustment layer, written once, applied to every company in the universe including the ones you have no interest in, and versioned like code.
The five adjustments that reorder a ranking
Take them in the order they do damage.
Share-based compensation. The failure is not that firms ignore it, it is that they handle it in two places and net it to zero. Stock comp is added back in the cash flow statement as non-cash, then excluded again from adjusted earnings, and the diluted share count is projected flat. Policy: treat it as an operating expense in every margin and multiple, and separately project diluted shares forward from grant run rate net of buyback. Two adjustments, not one, because the expense and the ownership dilution are different events.
Leases. Reporting regimes differ in how lease costs split between operating expense, depreciation and interest, so EBITDA for two retailers or two airlines with identical economics can differ by a wide margin purely on filing standard. Policy: pick one treatment for the whole universe, either capitalise leases consistently and carry the liability in net debt, or strip lease capitalisation out consistently and compare on a rent-inclusive operating measure. Both work. Mixing them within one ranked list does not.
Research and development. Expensing research understates the asset base of the companies that invest most heavily in it, so return on capital looks flattering exactly where capital is being consumed fastest. Policy: capitalise and amortise over a life fixed by sector, add the unamortised balance to invested capital, and apply it to every company in the sector regardless of whether the resulting number helps your thesis.
Pensions. Two things need separating. The service cost is compensation and belongs in operating expense. The interest and return components are financing and belong below the operating line. The funded status, net of tax, belongs in net debt, which changes enterprise value directly. Firms that skip this systematically favour companies with large legacy schemes.
One-off items. The most abused category on the list, because it is the only one where the analyst chooses. Policy handles it later in this piece.
One list, several accounting regimes
Any screen that lets you widen the universe across jurisdictions makes this problem concrete rather than theoretical.
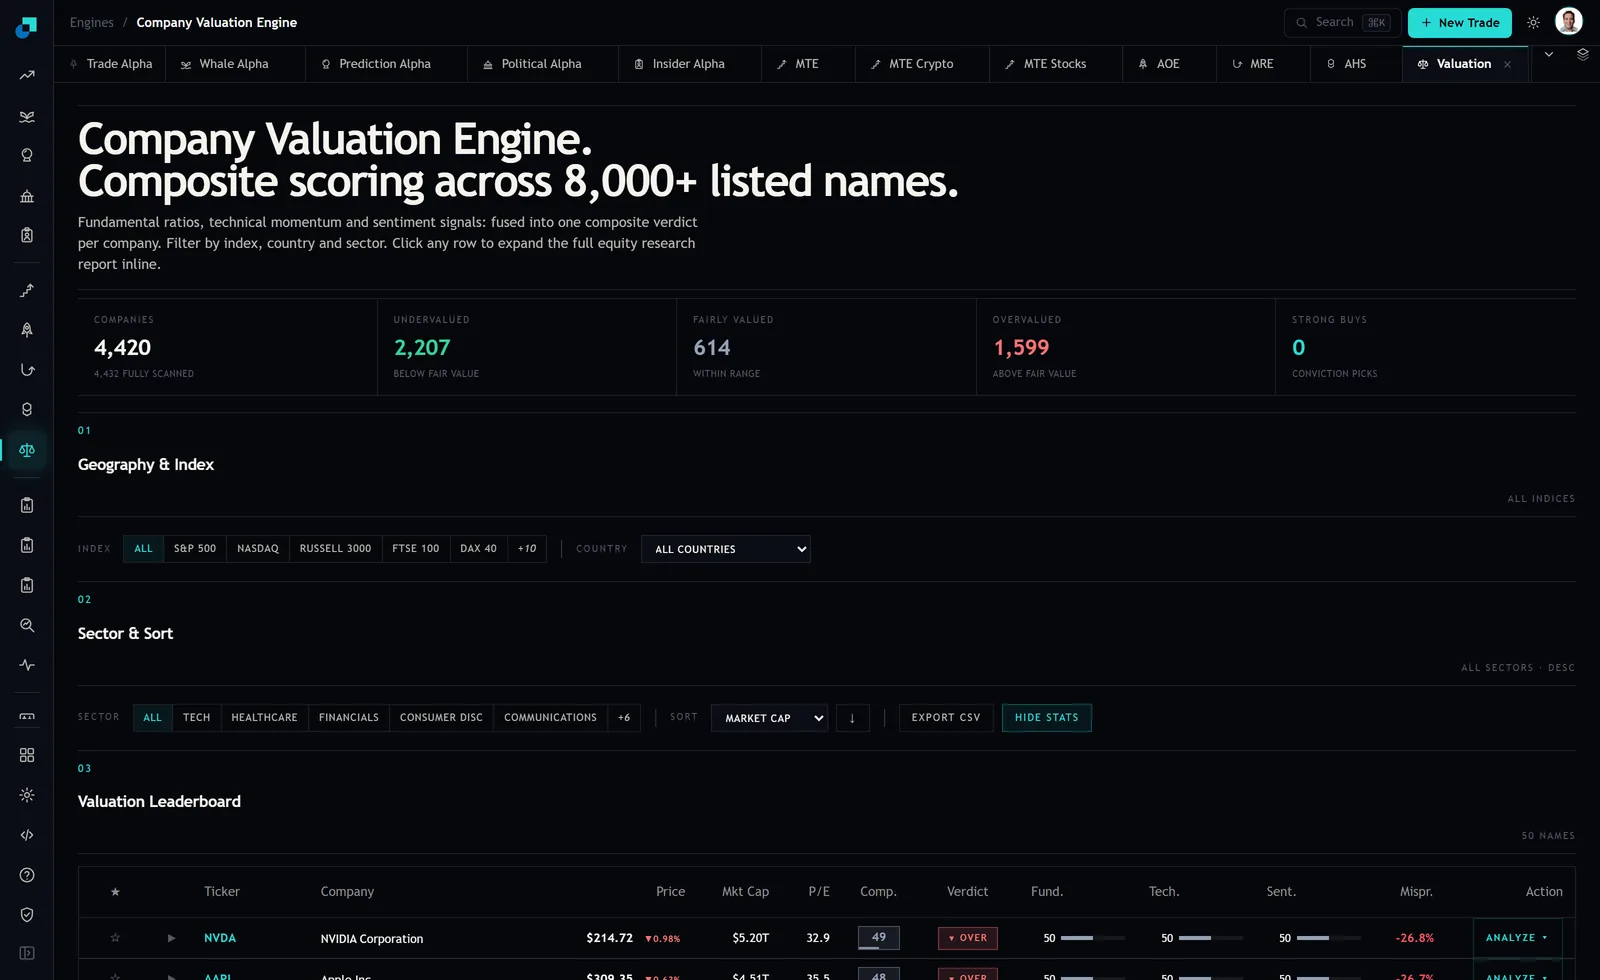
The engine scores across a large universe, 4,420 companies on the board at capture with 4,432 fully scanned, and the ranking it returns is internally consistent by its own method. That is a different guarantee from the one you need. Your ranked list has to be consistent under your house policy, which means the normalisation layer sits between any vendor output and anything a portfolio manager reads. Where the vendor number and your restated number diverge, the divergence itself is worth logging, because a persistent gap on one sector usually means an adjustment is misfiring rather than that the vendor is wrong.
Fixing the parameters so the layer is not re-argued per name
An adjustment policy that leaves parameters open gets re-litigated on every contested name, and the analyst who argues hardest wins. Fix them in advance and record them in one document.
| Adjustment | Fixed parameter | What it touches |
|---|---|---|
| Share comp | Expense in full, project shares from trailing grant rate | Margins, multiples, per-share value |
| Leases | One treatment universe-wide, stated discount basis | EBITDA, net debt, enterprise value |
| Development spend | Amortisation life per sector, set once a year | Operating profit, invested capital, returns |
| Pensions | Service cost operating, funded status after tax in net debt | Operating profit, enterprise value |
| One-offs | Look-back window and symmetry rule | Earnings base, every multiple built on it |
Set the amortisation lives annually and not in the middle of a decision. The moment a life is chosen while a specific name is on the table, the parameter is an opinion about that name wearing a policy costume.
The symmetry test that catches the analyst thumb
One-off adjustments fail asymmetrically. Charges get added back, gains rarely get taken out. Two rules close most of the gap.
The look-back rule: if an item classified as non-recurring has appeared in a majority of the last five years, it is recurring, whatever the label says. Restructuring in five consecutive years is an operating cost with good public relations. Apply the rule mechanically from the data, not from the narrative in the release.
The symmetry rule: for every add-back of a charge, run the search for the corresponding gain. Disposal gains, insurance recoveries, legal settlements received, one-time tax benefits. Then report, per analyst and per quarter, the ratio of charges added back to gains removed. Nobody needs to be accused of anything. A ratio that runs consistently one-sided across a coverage list is a process finding, and it is far easier to discuss as a number than as a character judgement.
Measuring what the layer did
An adjustment layer that nobody measures becomes folklore. Run the universe twice, once as reported and once restated, and report three things to the investment committee each quarter.
- Median absolute rank change across the universe. This is the size of the effect in one number.
- Top decile survival, meaning the share of names in the as-reported top decile that remain in the restated top decile. If that number is high the layer is decorative on this universe. If it is low the layer is doing the work and the as-reported screen should not be circulated at all.
- The five largest single-name rank moves with the adjustment responsible for each. These are the cases where the layer is either most valuable or most likely to be mis-specified, and they are worth an analyst hour.
Keep both versions retrievable. When a position is reviewed after the fact, the question is what the screen said at the time under the policy in force at the time, and that is answerable only if the as-reported and restated outputs were both stored with the policy version stamped on them.
The names where the layer should be switched off
Uniformity has limits and pretending otherwise costs credibility. Lease capitalisation is meaningless for banks and insurers, where the balance sheet is the business. Development spending capitalisation applied to a company that capitalises internally developed software already will double count unless you strip its own capitalisation first. Pension adjustments on companies with defined contribution schemes only are noise generation.
So the policy needs an explicit exclusion list by sector, written down alongside the parameters. An exception you have documented is a policy. An exception applied quietly at the analyst's discretion is the exact problem the layer was built to remove.