Ask three analysts on the same desk for a mid-cycle margin on the same steel producer and you will get three answers separated by several hundred basis points, all defensible, all derived from the same public history. The dispersion does not come from the arithmetic. It comes from the window each one picked, and the window is almost never justified in writing. It is chosen, usually after the analyst has formed a view, and the number that emerges is then presented as the objective anchor against which the current price looks wrong.
The remedy is not a better window. There is no correct window. The remedy is a rule fixed before the output is visible, a capacity assumption held separately from the margin assumption, and a band reported instead of a point.
Where the discretion actually enters
Three decisions sit inside every normalisation and only the first is usually discussed.
The window length and its endpoints. Ten years is the convention and it is a convention rather than a finding. Ten years starting in 2011 and ten years starting in 2013 span different fractions of a cycle for most commodity-linked businesses, and the difference in the average margin between those two windows is routinely larger than the entire equity risk premium debate.
The variable being averaged. Averaging margin assumes the cost structure was comparable throughout. Averaging return on capital assumes the asset base was comparable. Averaging absolute earnings assumes size was comparable, which for any company that has made an acquisition it was not. These three give materially different answers on the same history.
The treatment of the current period. An analyst who ends the window at the last reported quarter is averaging in the present, which is exactly the period whose representativeness is in question. That is a circularity worth naming, because it is the mechanism by which a peak gets normalised into the base.
The board's only time axis is one day long
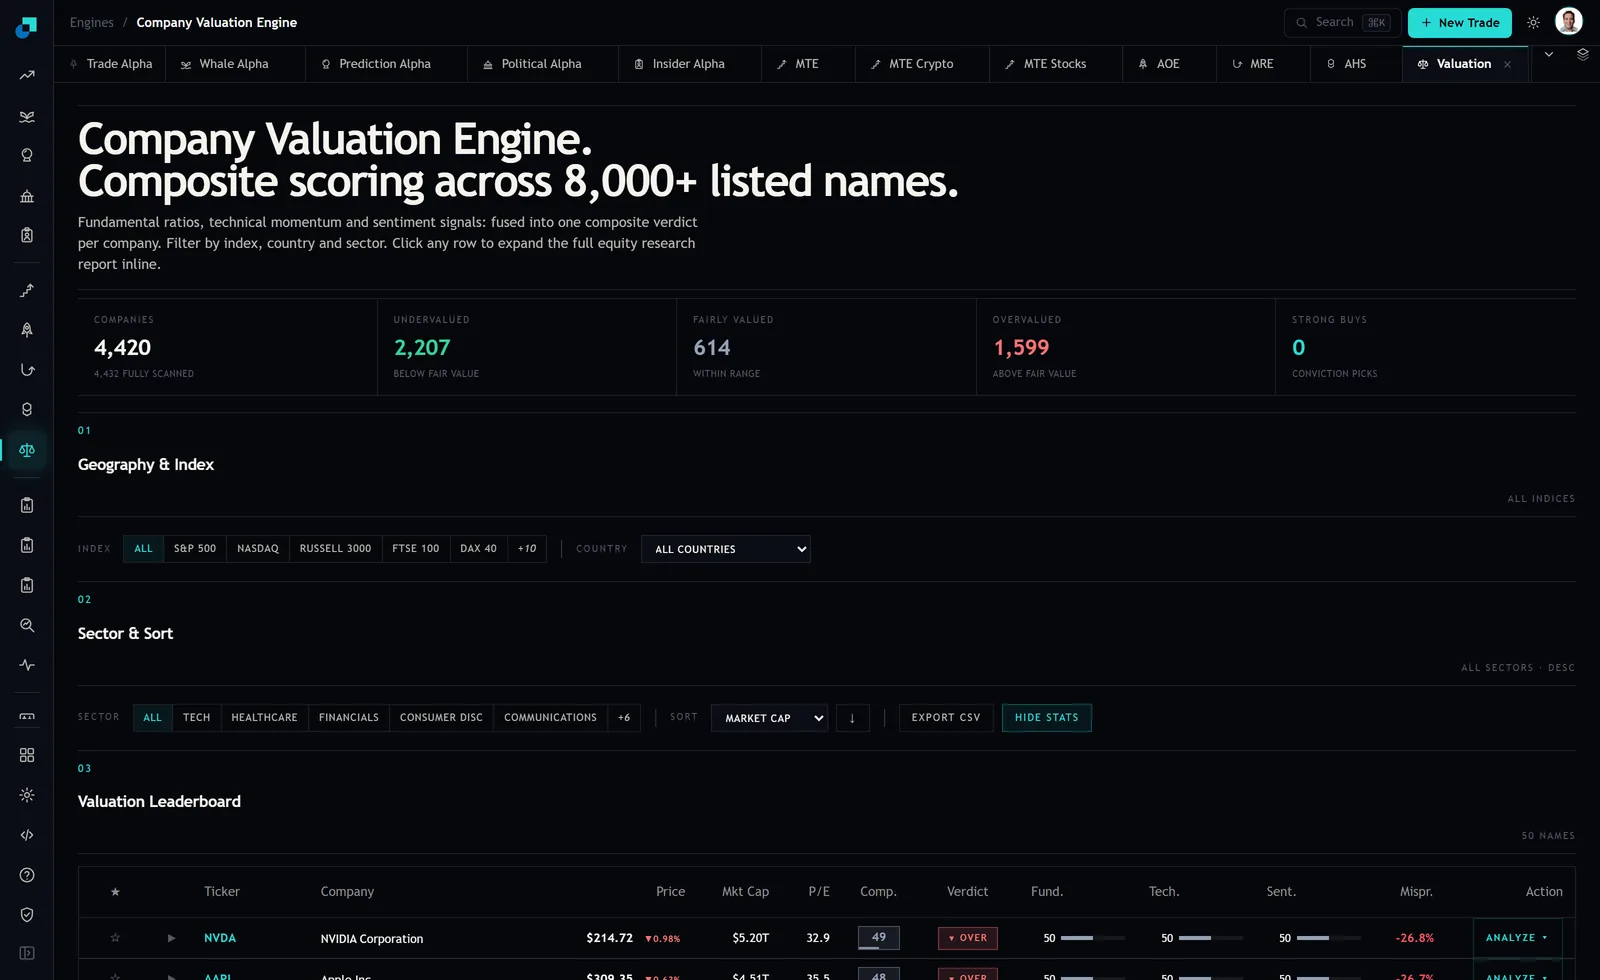
Being precise about that division of labour matters for process documentation. What the engine supplies is a consistently scored universe filterable by index, country and sector, which is a real contribution to the search problem and to the reproducibility of the starting list. What it does not supply, and does not claim to, is the time series the normalisation runs on. Any procedure note that blurs the two will not survive contact with a reviewer asking where a mid-cycle margin came from.
A window rule you can write down before you look
The rule that has held up for me has four clauses and takes about a page.
Endpoints are set on an exogenous cycle variable, never on the company's own margin. Capacity utilisation for industrials, a rig or drilling count for energy services, a freight rate index for shipping, housing starts for building products. Choose the variable per sector once, at the house level, and record it. Setting endpoints on the company's own results is how the window gets fitted to the answer, because the analyst can see both at the same time.
The window spans a full peak to peak movement in that variable, whatever number of years that turns out to be. Seven years for one sector, thirteen for another. A fixed ten years is a rounding of convenience that happens to be uncorrelated with the actual periodicity of any real industry.
The variable averaged is the margin on revenue restated for acquisitions and disposals, so that the series describes a comparable business. Where restatement is not possible, the segment is excluded from the average and the exclusion is stated.
The last four quarters are reported alongside the average but excluded from it. This costs a little information and removes the circularity entirely, which is a trade I would make every time.
Capacity is a separate assumption and it is usually the bigger one
The habitual error is to normalise revenue by averaging historical revenue. That embeds the historical asset base, and cyclical companies spend the cycle changing their asset base, usually adding capacity into the peak and writing it off into the trough.
Build normalised revenue as two independent terms. Current productive capacity, taken from the operating disclosure in physical units where they exist, tonnes, barrels, room nights, installed megawatts, and a mid-cycle utilisation or price realisation drawn from the window. Multiply. The result answers a different and better question, which is what this asset base earns at average conditions, rather than what a different asset base earned on average.
This separation is also what lets you handle a structurally different previous cycle, which is the case the assignment of a simple average always fails. The test is whether a mechanism can be named and sized. Industry consolidation from nine participants to four is a mechanism, and its effect on pricing power can be bounded. A technology cost curve that has moved the marginal cost of new supply down by a stated percentage is a mechanism. Demand substitution with a measured penetration rate is a mechanism. What is not a mechanism is the belief that this time is structurally different, unaccompanied by the thing that changed. Where a mechanism is named, adjust the utilisation or realisation term explicitly and show the unadjusted number next to it. Where none is named, do not adjust, and say in the memo that you considered it.
Report the band, because the band is the finding
A single mid-cycle margin presented to a committee invites a discussion about whether it is the right number, which is unanswerable and therefore unproductive. The interquartile range of the margin across the window, translated into equity value, invites a discussion about position sizing, which is the decision actually on the table.
Run the valuation at the twenty fifth percentile, the median and the seventy fifth percentile of the windowed margin, holding capacity and everything else fixed. Report the three values. Where the current price sits inside that range, the honest conclusion is that the name is not mispriced on this analysis, whatever a point estimate would have said.
Two disciplines keep the band from being decorative. The band is set before the current price is placed on it, and the width is not adjusted after the fact because it looked embarrassing. And the width itself is a reportable output, since a business whose margin ranges from four to nineteen percent across a cycle is telling you something about its capacity for damage that no point estimate transmits.
What a reviewer should be able to reconstruct
The file for each cyclical name needs five things, and if it has them the work is defensible even when it turns out wrong.
The cycle variable used for endpoints and the date the choice was made. The window in dates and the peak to peak movement it corresponds to. The restatement adjustments applied to the margin series, itemised. The capacity figure in physical units with its source disclosure. And the named mechanism behind any structural adjustment, with the unadjusted figure retained alongside.
The point of that file is not compliance. It is that eighteen months later, when the position is down forty percent and someone asks whether the thesis broke, you can answer by checking whether the cycle variable moved outside the historical range or whether the margin simply came in below your median. Those are different failures with different responses, and without the file they are indistinguishable.