Someone on the desk will eventually put the sector heatmap next to a sector ETF flow series and announce that Congress rotated into Industrials three weeks before the money did. It is an easy chart to make and it is almost always wrong, not because the correlation is absent but because the two series are stamped with different clocks and nobody checked which one the tile is using.
This is a test worth running properly, because the answer changes what the sleeve is. If disclosed political trading genuinely leads sector flows, you are buying an early signal and capacity is your binding constraint. If it is coincident, you are buying a confirmation tool and it belongs in the risk process rather than the alpha process. If it lags, you are paying for a slow proxy of a flow series you can already licence, and the honest thing to do is say so in the investment committee memo.
Resolve the date semantics before you compute anything
The header on the module reports average delay from trade to filing at 32.5 days. That single number decides the shape of the whole exercise, and it means the disclosure feed carries two dates per event that sit a month apart on average.
So the first question is which of those two dates the heatmap window is keyed on. If the tiles aggregate by transaction date, the 30 day window shown in the selector describes trades that happened over the last month, of which the recent ones are systematically under-reported because their filings have not landed yet. That produces a right-hand edge that fills in over the following weeks and a lead-lag estimate that drifts every time you rerun it. If the tiles aggregate by disclosure date, the window is complete the moment you look at it, but every observation in it refers to a trade that happened roughly a month earlier, and a lead over fund flows measured on that basis is a lead you could never have traded.
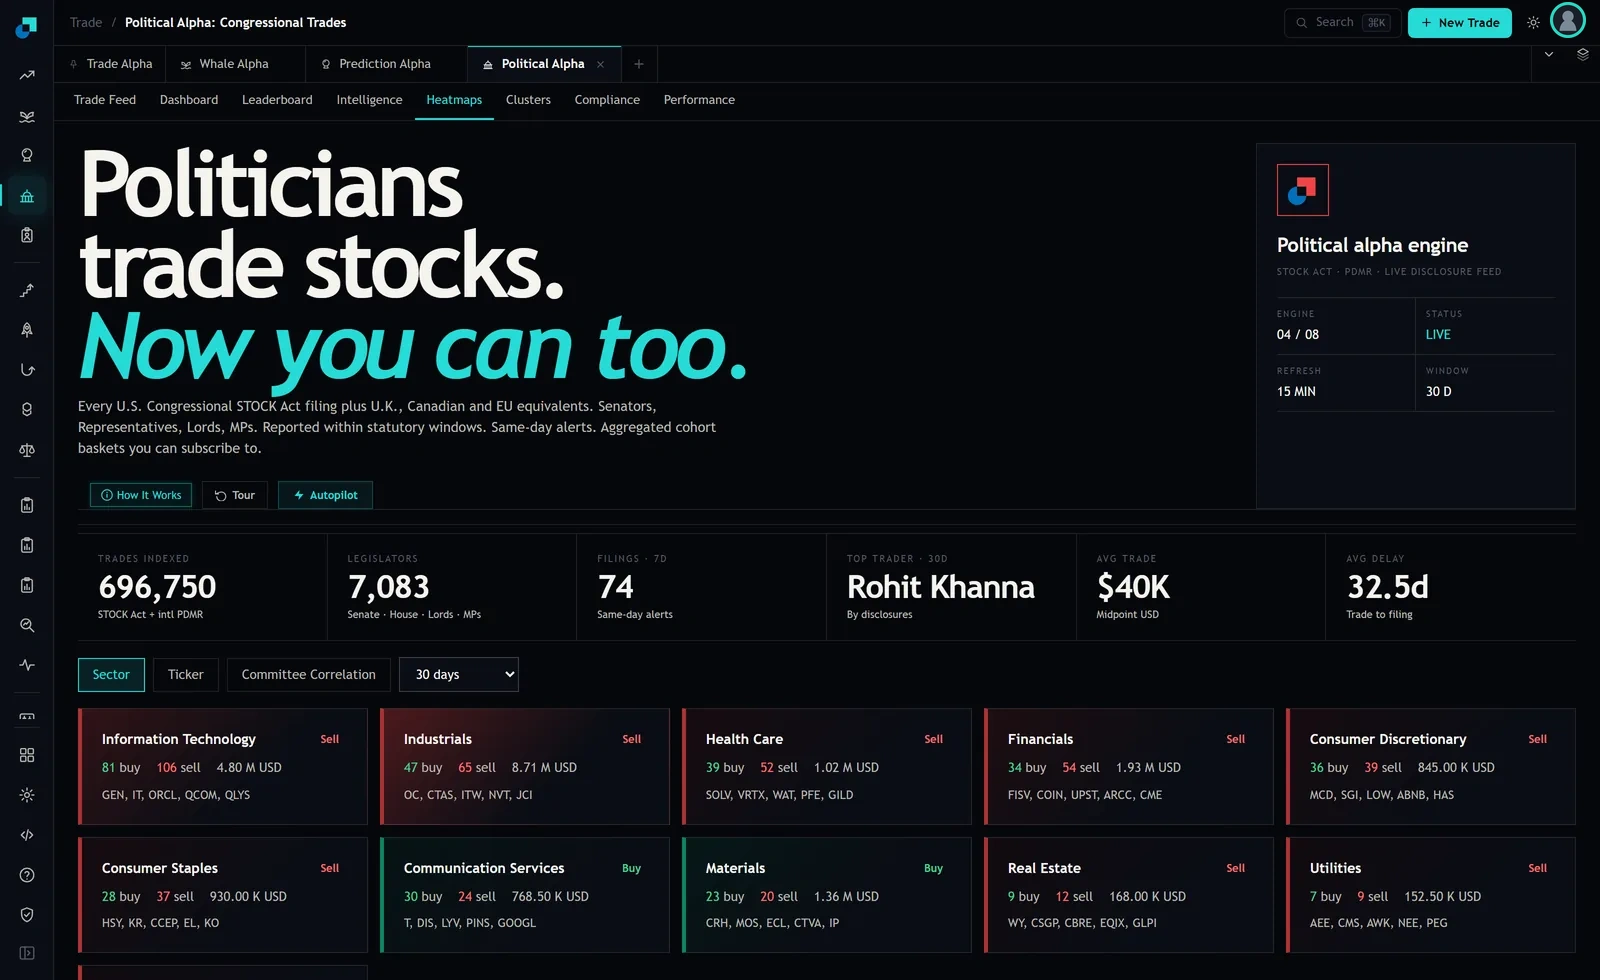
I do not treat this as a detail to sort out later. Until you can state which date stamps the tile, the correlation you compute has an unknown constant offset of up to about a month, and the sign of your conclusion sits inside that offset. Establish it against the underlying rows rather than by inference from the tile, and record the answer in the research note, because whoever repeats the study in a year will otherwise re-derive it wrongly.
What the sector view gives you and what it does not
The Heatmaps tab carries three views, Sector, Ticker and Committee Correlation, with the window selector alongside. On the capture in front of me the sector view showed ten tiles, each with a direction label, a buy count, a sell count, a USD notional and five leading tickers.
The numbers are the raw material for the study. Information Technology showed 81 buys against 106 sells on 4.80 M USD. Industrials 47 against 65 on 8.71 M. Financials 34 against 54 on 1.93 M. Materials 23 against 20 on 1.36 M. Health Care 39 against 52 on 1.02 M. Consumer Staples 28 against 37 on 930 K, Consumer Discretionary 36 against 39 on 845 K, Communication Services 30 against 24 on 768.5 K, Real Estate 9 against 12 on 168 K, Utilities 7 against 9 on 152.5 K. That is 752 transactions and roughly 20.7 M USD of disclosed notional across the whole window.
Twenty million dollars is the number to keep in front of you. Sector ETF flows are measured in hundreds of millions to billions per week per sector. You are correlating a series built from a few hundred transactions against a series built from institutional allocation, and the political series is not a subset of the flow series in any meaningful proportion. Whatever relationship you find is informational, not mechanical, which is a stronger claim and needs a correspondingly stronger test.
Note also that the notional is built from bracket midpoints. The header reports average trade size as $40K with the explicit subtitle Midpoint USD, so tile notional is an estimate assembled from ranges, and a handful of high-bracket filings can move a sector's dollar figure without moving its transaction count. That argues for running the study on counts as the primary series and notional as the robustness check, not the other way round.
The specification I would take to a research meeting
Build the political series as weekly net transaction count by sector, buys minus sells, standardised within sector so a large sector does not dominate. Build the flow series as weekly net creations in the sector ETF complex, in dollars, standardised the same way. Cross-correlate at lags from minus eight weeks to plus eight weeks, sector by sector, and keep the per-sector results rather than pooling them, because pooling ten sectors with different breadth hides the fact that Utilities contributed sixteen transactions and Information Technology contributed 187.
Then apply the corrections that decide the answer. Shift the political series by the filing delay if the tiles are disclosure-stamped, and use the per-trade delay rather than the 32.5 day average, because the average is a mean over a distribution that includes same-day filers and very late ones. Exclude the incomplete right edge if the tiles are trade-stamped. Difference both series, since a level correlation between two persistent series will produce a confident number out of nothing.
Set the decision rule before you look at the output. My threshold is that a lead has to appear in at least six of the ten sectors, at the same sign, with the peak correlation at the same lag or the adjacent one, and it has to survive dropping the largest single filing week. Anything short of that is one sector doing the work, and one sector doing the work over a few hundred transactions is not a rotation signal.
Why a real lead would probably still be untradable
Suppose the test comes back clean and the political series leads sector flows by two to three weeks on the transaction date. That result is interesting and it is not yet a position, because you did not see the transaction date until the filing landed.
The chain runs like this. Trade happens. Roughly a month passes on average. Filing lands and you see it. If the lead over flows is shorter than the filing delay, the informational lead is real and entirely consumed before you can act, and the strategy that exploits it is not available to anyone reading disclosures. Only the residual matters, which is the part of the flow response that occurs after the filing date, and that is the quantity the test should be estimating in the first place. I would specify it directly as the correlation between the disclosure-dated political series and forward sector flows, and treat the trade-dated version as a descriptive exercise about how the world works rather than as a signal study.
Reading the three possible answers into the mandate
If disclosure-dated political flow leads sector flows even modestly, the sleeve has an allocation case, and the constraint becomes capacity and crowding, since the same filings are visible to everyone and the small and mid caps in the tiles absorb very little. Size the sleeve against that rather than against the strength of the correlation.
If it is coincident, the honest use is confirmation. A sector tile that flips to net buying at the same time your flow model does raises the confidence of an existing view slightly and starts nothing on its own. That is a legitimate role and it belongs in the risk report, not in the alpha attribution, and saying so protects you when someone asks what the sleeve contributed in a quarter when it contributed nothing.
If it lags, write that down and keep the module for a different job. The Committee Correlation view and the compliance and punctuality fields carry per-filer information that has nothing to do with sector rotation, and a negative rotation result does not touch them. The failure mode I want to avoid is the one where a desk quietly keeps a sector-rotation narrative alive because the study was never specified tightly enough to kill it.