Every congressional-trading list you have ever seen circulated on social media was ranked by activity. Most trades, most disclosures, most filings this quarter. It is the ranking that produces headlines, and it is close to the least useful ordering available, because the quantity it measures has almost nothing to do with the quality of the information behind any individual trade.
The Political Alpha Leaderboard opens the same way, and I want to walk through what happens when you actually look at what the sort produced, because the top of that list makes the argument better than I can.
The default sort is total trades, and the control is right there
Open the Leaderboard tab and the filter bar reads left to right: a search box, a chamber filter set to All with House and Senate beside it, a status filter set to All with In Office and Former beside it, and a sort dropdown. On my capture that dropdown reads Total Trades. To the right of it, the population count: 7083 politicians.
So the list you are looking at on arrival is 7,083 filers ranked by how many transactions they have disclosed. Nobody chose that as an analytical decision. It is a default, and defaults are where most retail research quietly ends.
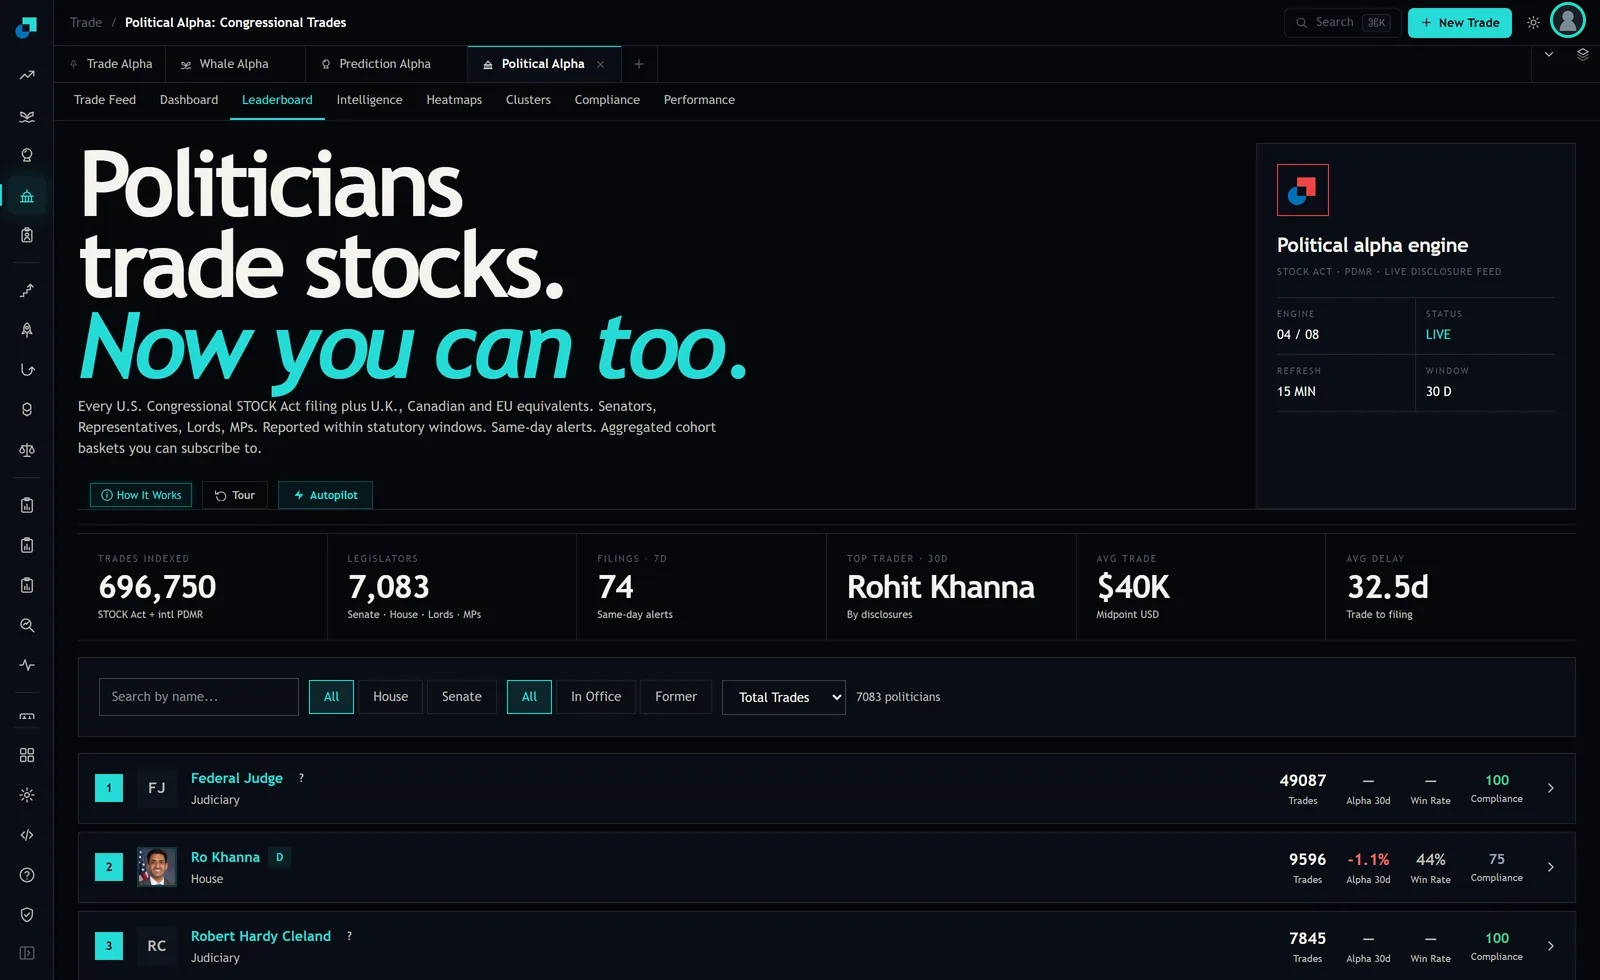
The top of the count-ranked list cannot be scored
Rank one on my capture is not a senator or a representative. It is an entry labelled Federal Judge, filed under Judiciary, carrying 49,087 disclosed trades. The Alpha 30d column is empty. The Win Rate column is empty. Both are drawn as a dash.
Rank three is another judiciary filer, 7,845 trades, and the same two columns are empty again. Rank two is the first legislative row, a House member with 9,596 disclosed trades, and that one does carry numbers: Alpha 30d reading minus 1.1 percent, win rate 44 percent.
Take that in for a second. On the ranking the page hands you by default, two of the top three rows are filers whose forward performance the module does not compute, and the one row that is scored is showing negative 30 day alpha and a win rate below half. If you had opened this page, looked at the top, and gone looking for names to follow, you would have spent your first five minutes on rows that carry no performance information whatsoever.
Trade count measures account structure, not conviction
Why would one filer disclose 49,087 transactions while thousands of others disclose a handful? Not because they are trading forty-nine thousand ideas.
Disclosure regimes report transactions, and a transaction is generated by any movement in a covered account. A portfolio held in managed accounts with periodic rebalancing, a set of funds with regular distributions, dividend reinvestment across a wide book, an advisor running the money with a systematic process: all of these produce a very high transaction count with essentially zero directional information from the person whose name is on the filing. A member who buys three individual stocks a year because they have a view produces three rows.
Those two profiles sit in the same column, and the high-count one wins every time. So the count ranking is, in practice, a ranking of how mechanically active someone's accounts are. It reliably sorts to the top exactly the filers whose disclosures you least want to read, because volume-generating account structures are the ones where the named individual is furthest from the trading decision.
This is also why the count-ranked list is dangerous for a retail follower specifically. If you decide to shadow the most active name, you are signing up to a stream of dozens or hundreds of rows a year, each disclosed weeks after the fact, each in a size bracket rather than a size, and each carrying commission and spread on your side if you act on it. Fifty trades a year at even a few dollars of friction and a bracket you cannot size against is a guaranteed cost against an unmeasured edge.
The columns that would rank something useful are on the same row
Everything you need to re-rank is already visible. Each row carries four numbers to the right of the name: Trades, Alpha 30d, Win Rate, Compliance. Only the first is being used by the default sort.
Alpha 30d is the forward measure, and the module documents performance analytics computed at 30, 60, 90 and 180 days by politician, party and chamber, so the 30 day figure on the row is the shortest of several horizons available in the Performance tab. Win Rate is the hit rate. Compliance is a punctuality score on the filer's disclosure behaviour rather than a performance number.
The re-rank I would actually do takes about fifteen seconds and starts with the filters rather than the sort. Set the chamber filter to House or to Senate. That single click removes the judiciary entries, which is what put an unscoreable 49,087 row at the top in the first place, and leaves you with a population where the performance columns are more likely to be populated. Then work down the visible rows reading Alpha 30d and Win Rate rather than Trades, and ignore any row where both are empty, because an empty performance cell means the platform is declining to score that filer and you should decline too.
What a sensible shortlist looks like instead
The list you want is short, and building it is subtractive rather than additive.
Start from a chamber filter so you are looking at legislators. Drop every row where the performance columns are blank. From what is left, ignore the extreme high-count rows, not because activity is disqualifying but because a filer producing thousands of rows is producing them from account mechanics, and you have no way to separate the three decisions that mattered from the nine hundred that did not. What survives is a middle band: filers with enough disclosed trades that a win rate means something, and few enough that individual filings plausibly reflect individual decisions.
Then apply the arithmetic that decides whether any of this is actionable for an account your size. A 44 percent win rate is not a defect on its own, since a strategy with a 44 percent hit rate and asymmetric payoffs can work perfectly well, but you would need to know the payoff distribution to say so, and a leaderboard row does not carry it. Negative 30 day alpha on the most-scored high-activity row in the list is a straightforward warning that following the busiest names is not a free option.
The reason this ordering problem persists is that count ranking is the only ranking that is trivially computable from disclosure data alone. Returns need prices, matching, and a horizon convention. Counts need nothing. So every free tracker publishes the count list, the count list gets shared, and the noisiest filers in the dataset become the famous ones. The fix is one click on a filter and reading two columns to the right of the name you were about to write down.