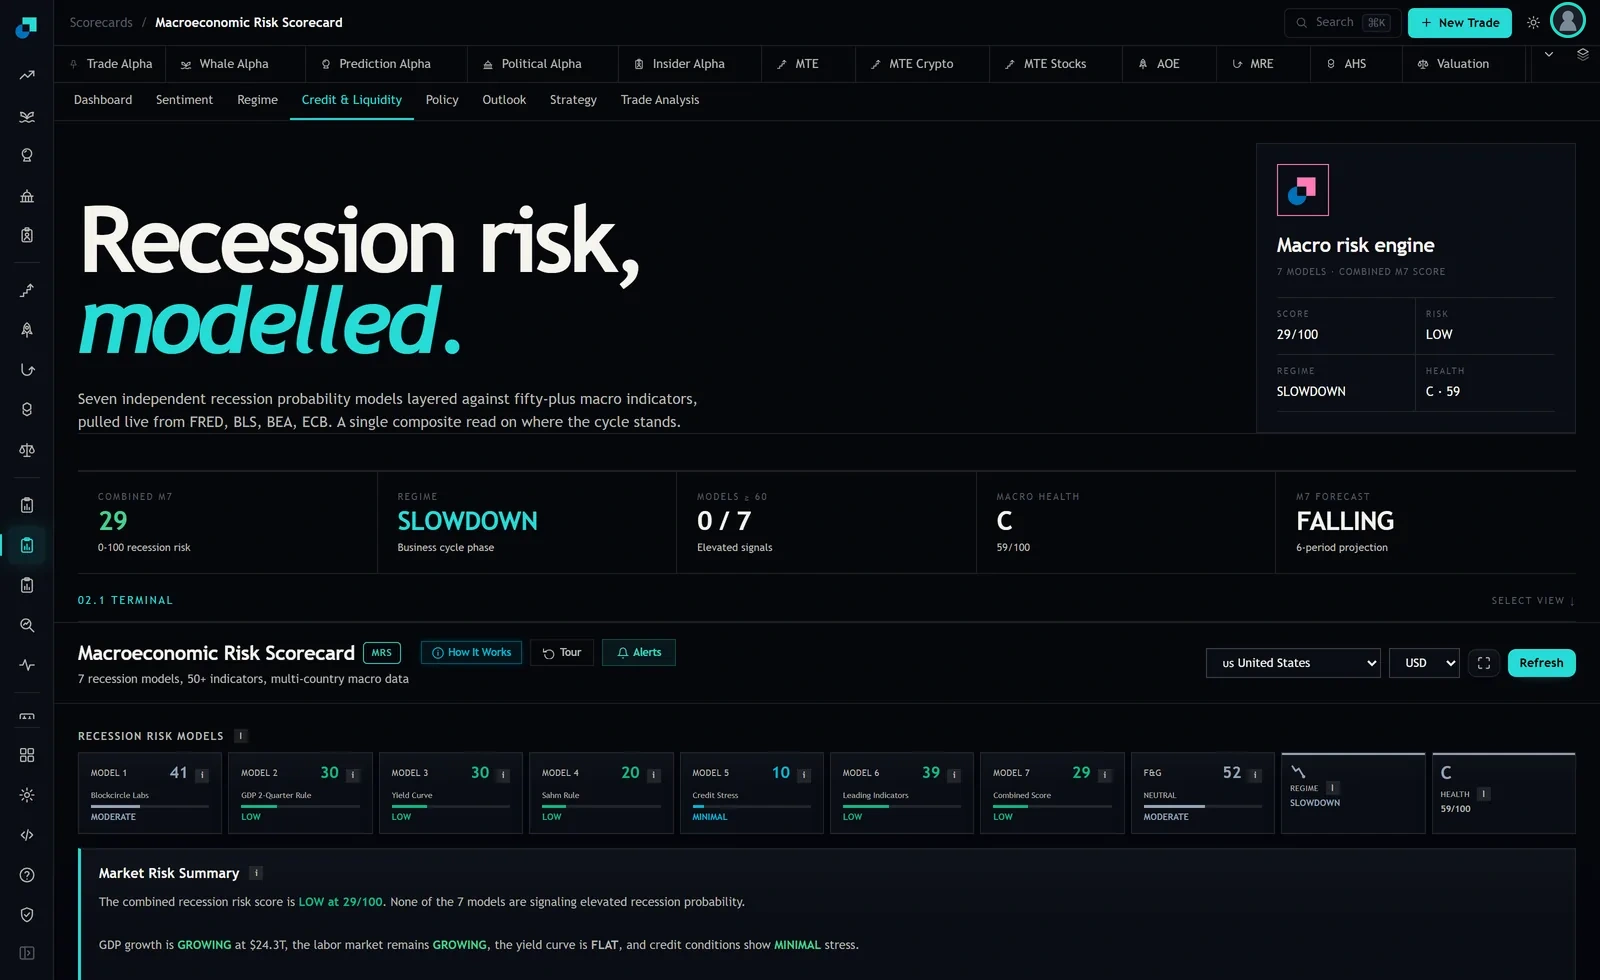
The credit node on the Macro Risk Scorecard resolves to a single number. Model 5, Credit Stress, reads 10 out of 100 and is tagged MINIMAL, and the module describes its credit coverage as monitoring credit default swap spreads and high yield spreads. That is a defensible design for a composite that has six other models to accommodate, and it is also a collapse, because the two questions credit can answer have been averaged into one answer.
Say plainly what follows from that. If you want quality dispersion inside high yield, the gap between the weakest tier and the middle of the market, you are building and maintaining that series yourself. It is not a tab you open, and this article is about the reader's construction rather than a panel on the page. What the scorecard gives you is a consistent, dated credit reading to reconcile your own series against, which is more useful than it sounds.
Two mechanisms, one average
An index spread widens for two structurally different reasons and reports them identically.
The first is a change in the price of risk. Financing conditions tighten, dealer balance sheet gets more expensive, the marginal buyer of credit demands more compensation for the same expected losses. This moves everything, and it moves everything roughly in proportion. Nothing about any borrower's prospects has changed.
The second is a change in expected losses. The market revises its view of who will actually pay. This does not move everything. It concentrates in the names and tiers where the revision applies, which in high yield means the weakest cohort moves several times as far as the strongest.
The average cannot distinguish these, which matters because they have opposite implications for the book. A funding-driven repricing is, mechanically, a better entry point for a credit allocation. A default-driven repricing is a warning that your recovery assumptions are the next thing to be tested. Treating them the same way is how a credit sleeve gets added to at exactly the wrong time and defended afterwards with the phrase "spreads were attractive".
Why the ratio behaves better than the difference
The obvious construction is the arithmetic difference between the weak tier spread and the middle tier spread. It is the wrong one to lead with, and the reason is a scaling problem you will hit immediately.
Spread differences are mechanically wider when the whole market is wide. In a stressed market a difference of several hundred basis points between tiers may represent ordinary proportionality. In a tight market the same absolute difference would be extreme. A series built on the difference therefore drifts with the level of the market and will tell you that dispersion is elevated whenever spreads are elevated, which is the confound you were trying to remove.
The ratio of the weak tier to the middle tier is close to scale free. When the price of risk moves and expected losses do not, both tiers move roughly proportionally and the ratio is stable. When the market starts discriminating, the ratio expands. That is the signal, and it is the one to put in the risk report.
Run both if you like, since they answer slightly different questions, but the ratio is the one that goes in front of a committee, because it is the one that will not embarrass you when somebody points out that everything looks stressed when everything is stressed.
Constructing the series without importing three known distortions
The data is available from public and vendor sources at daily frequency and the construction takes an afternoon. Keeping it honest takes longer, and three specific problems account for most of the trouble.
- Composition drift. The industry mix of each ratings tier is not constant. Sector concentration inside the weak tier means an industry shock can expand your ratio without any broad change in default expectations. The fix is to compute the ratio within a few major sectors as well as at the index level, and to distrust the headline whenever the sector versions disagree.
- Ratings migration. Names move between tiers. A wave of downgrades pushes weak names out of the middle tier and into the bottom one, which changes the average spread of both tiers without a single bond repricing. Your series moved and nothing happened. Track the tier populations alongside the spreads so that a compositional move is visible rather than being read as a signal.
- Survivorship at the bottom. Defaulted issues leave the index. The weak tier spread is therefore an average over the names that have not yet failed, which understates stress precisely when stress is highest. This is not fixable with index data. It is a limitation to write down, and it means your dispersion measure is conservative in the tail.
Add one more discipline. Fix the construction in advance and version it. A dispersion series whose definition is adjusted after a surprising reading is not a measurement, it is a narrative device, and the adjustment always looks reasonable in the moment.
Folding it in without double counting the same information
The temptation is to add the dispersion series as a new input to the composite. Resist it, because the level of high yield spreads is already in the credit model, and dispersion is correlated with the level. Adding it as an input increases the weight of credit in the score without anyone deciding to do that, and it does so through a channel nobody will remember when the attribution is reviewed a year from now.
The better architecture keeps the two separate by job. The scorecard's credit tile answers how much stress. Your dispersion series answers what kind. Kind is a conditioner on the response, not a component of the level.
In practice that means writing the response rule as a pair. When the credit reading rises and dispersion is flat, the interpretation is a repricing of risk appetite, and the appropriate response is about the entry price of credit exposure and about financing, not about defaults. When the credit reading rises and dispersion expands with it, the interpretation is that the market is revising who gets paid, and the response is about recovery assumptions, about the weakest holdings in the book, and about the second-order exposure sitting in equities of leveraged issuers.
Both of those are sentences you can put in a memo before the fact and be judged on afterwards, which is the property that distinguishes a process from a view.
Where the tell fails and what to do about it
Three conditions degrade this measure, and knowing them in advance is the difference between an input and a superstition.
The weak tier universe is small and concentrated. A handful of large capital structures can dominate it. When they do, the ratio is reporting an issuer story in the language of a systemic one, and the only defence is to look through to the constituents, which requires holdings-level data and is the reason this is an institutional exercise rather than a retail one.
Index eligibility rules distort both ends. Bonds enter and leave on criteria that have nothing to do with credit quality, including size and maturity thresholds, and those flows fall unevenly across tiers.
And the measure is quiet when it is least useful. In a market where the weak tier has already stopped trading in size, quoted spreads reflect indications rather than transactions, so dispersion can look stable while the actual price of moving risk has gone. Cross-check against issuance, since a period in which weak issuers cannot raise money at all is one where the spread series has stopped being informative regardless of what it prints.
None of that makes the dispersion series optional. It makes it an instrument with a known failure envelope, which you document alongside the number, the same way you document the credit tile it sits next to.