Two rows land in the feed on the same morning. Both are purchases. Both are the same size bracket. Both are in mid-cap industrials. One of them is the first time that filer has ever disclosed buying that company. The other is the eleventh top-up on a position they have been adding to steadily for four years.
In the feed those two rows are indistinguishable. They carry the same fields, they sort the same way, they trigger the same alert. And they are not remotely the same event. The first one is somebody deciding that a company they did not own is now worth owning. The second one is a schedule.
Why the distinction carries the weight
An initiation requires a decision that a top-up does not. To buy something for the first time, somebody had to look at a company that was not in the book, form a view, and act on it. That is a discrete event with a cause, and the cause is exactly the thing you are trying to infer.
A top-up has a much wider set of explanations, and most of them are boring. Cash came in and got deployed across existing positions. An advisor rebalanced toward target weights. A distribution reinvested. A regular contribution schedule bought the same names it bought last quarter. Every one of those produces a purchase row that looks like conviction and contains none.
This is the general intuition behind reading any insider or disclosure feed, and it is not specific to politicians: an initiation is a cleaner expression of a view than an increment, because the increment is compatible with a process that involves no view at all. The corollary is worth stating too. A sale of an entire position is the mirror image and carries similar weight, whereas trimming is as noisy as adding.
The only place the distinction is visible
Nothing in a feed row tells you which of the two you are looking at, because a purchase row describes a transaction and the distinction lives in the filer's history rather than in the transaction.
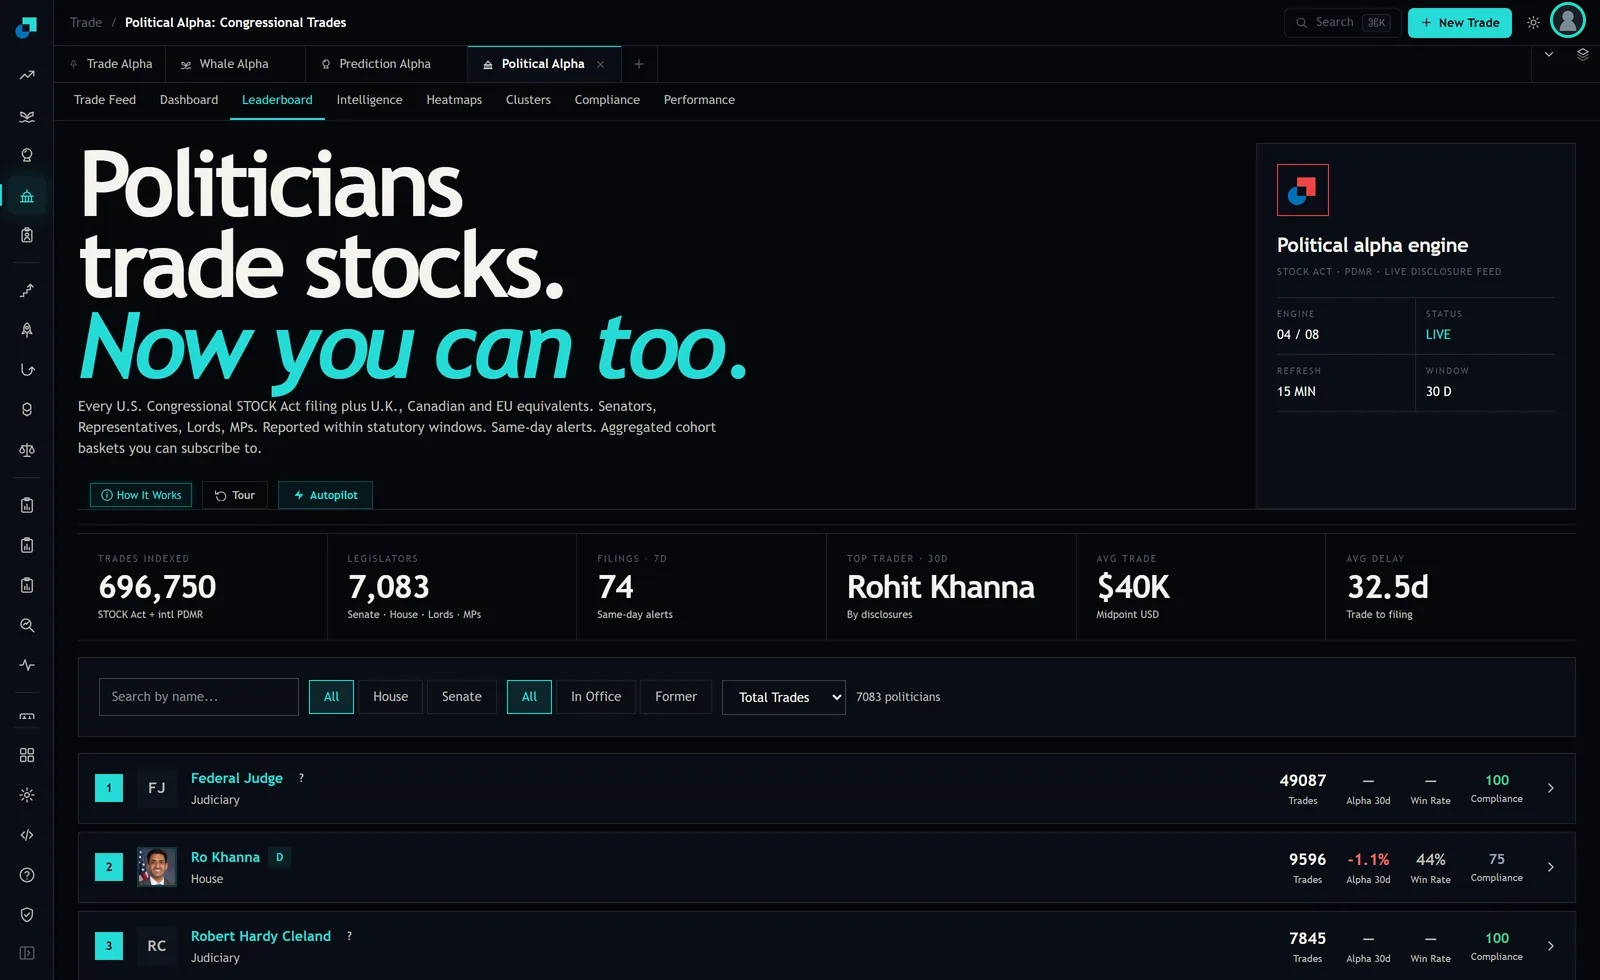
So you go to the filer. On the Leaderboard tab, the filter bar starts with a search box reading "Search by name..." against a population of 7083 politicians, and each row ends in a chevron that opens that filer. The module documents per-politician profile pages carrying full trade history, and that history is where the answer is. You are looking for one thing: every prior appearance of that ticker in that filer's record.
Three outcomes. If the ticker appears repeatedly across previous years, you are looking at an add, and you can stop. If it appears once or twice recently, you are looking at someone building a position, which is more interesting than a routine top-up but is not an initiation. If it does not appear at all, you may have an initiation, and the word may is doing real work in that sentence, which brings us to the trap.
First disclosed is not first ever
An empty search result means the ticker does not appear in the history you can see. It does not mean the filer has never owned the company.
Disclosure regimes report transactions, not holdings. Anything acquired before the filer entered the covered population produces no transaction row and therefore never appears in any history you can read. A position bought fifteen years ago and held ever since is invisible. So a purchase that looks like an initiation might be a top-up on a long-held stake whose original purchase predates coverage entirely.
There is a second version of the same problem at the platform boundary. The dashboard header reports 696,750 trades indexed, and the tile below it reports 695,258 total trades, which is a gap of about 1,500 rows between two counters of nominally the same universe. That gap is small in percentage terms and it is a useful reminder that any archive has inclusion rules you do not control. An absence in a history panel is weaker evidence than a presence.
How much does this matter in practice? Most for long-serving filers, least for recently arrived ones. If someone entered the covered population two years ago, their disclosed history is close to their whole relevant history and an empty ticker search is strong. If they have been filing for two decades, an empty search is much weaker, because their pre-coverage holdings are a large and completely invisible set.
The five minute version, and when to skip it
Here is the check as a routine. Note the ticker and the filer from the feed row. Open the filer from the Leaderboard. Search their history for the ticker. Count prior appearances and note the earliest date. Then note how far back the filer's history runs in total, because that is what tells you how much an absence is worth.
Two conditions make it worth doing at all, and both are checkable before you start. First, the filer has to be a low-cadence one. A filer disclosing tens of thousands of transactions, and the top row of the Leaderboard carries 49,087 of them, is running account machinery rather than making decisions, and inside that volume an initiation is just as likely to be an advisor adding a new fund as a person forming a view. The check only means something for filers whose whole record is small enough that individual trades are individual choices.
Second, the size bracket has to be above the bottom of the range. An enormous share of disclosed activity sits in the $1,001 to $15,000 bracket, which is why the live ticker shows row after row carrying exactly that string. The bottom bracket is where routine account activity lives. An initiation reported in a higher bracket is a stronger observation simply because fewer mechanical processes produce one.
And when the check passes, be clear about what you have won. You have established that a filer appears to have bought something they did not previously own, roughly a month ago, in a size you can only bound to a bracket. That is a reason to spend twenty minutes on the company. It is not a reason to buy it, and if the stock has already moved across the disclosure window then the initiation has told you something about the past rather than about the price in front of you now.
The reason I still run it is subtraction. Most of what arrives in a disclosure feed is machinery, and the initiation test is the cheapest filter I know for throwing the machinery away. Five minutes to discard nine rows out of ten is a good trade against the alternative, which is reading all ten as though they meant the same thing.