The opening long form filing gets all the attention. It is the one that shows up in headlines, moves the stock for a day, and gets forwarded around. It is also the least informative document in the sequence, because at that point the filer has done exactly one thing, which is buy shares.
Everything that follows arrives as an amendment. Board seats demanded, stakes added to, letters sent, agreements signed, positions cut. If you want to know whether a campaign is going anywhere, you read the amendment stream, not the original. The Activists tab makes that possible because it treats 13D/A as its own filing type rather than folding amendments in with the filings they amend.
Why the amendment is where the campaign actually happens
A long form filer has a continuing obligation. When something material changes in what they disclosed, they amend. That covers changes to the stake, changes to the stated purpose, new agreements, changes in the source of funds, and changes to the plans they described.
The stake part has a usable benchmark. An acquisition or disposition of an amount equal to one percent or more of the class is deemed material, so a filer moving through that much is going to file. That gives you a resolution on the position. You are not going to see every hundred shares, but you will see moves of a size that mean something.
The purpose part has no benchmark at all, which is what makes it interesting. A filer who was reserving rights in the original and who now names a slate of directors has crossed from optionality into commitment, and there is no threshold that forced them to. They chose to.
Setting the filter so you see a stream and not a snapshot
Set FORM to 13D/A and push WINDOW out to 90d or 1y. This is the one screen where the 30d default actively works against you. A campaign runs for quarters. One month of amendments is a fragment of a sentence, and you will draw conclusions from it that the full sequence would contradict.
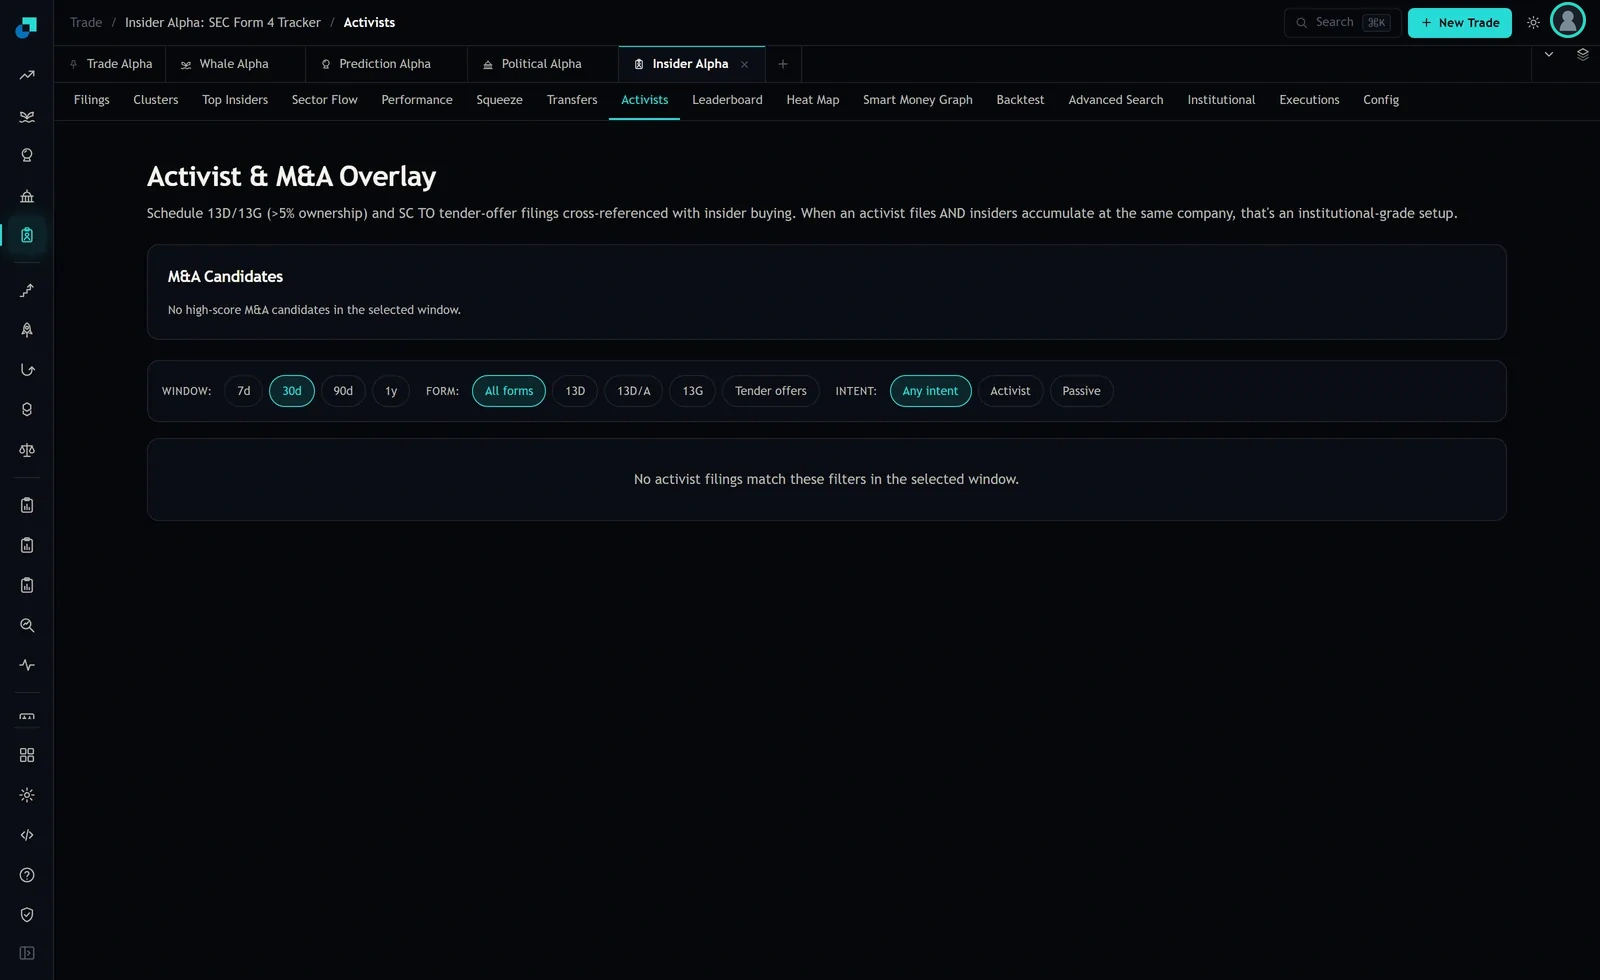
Leave INTENT on Any intent while you are doing this. Filtering to Activist before you have looked at the raw stream throws away the cases you most want, which are filers whose behaviour is changing. A filer in the middle of changing their mind is exactly the one a static tag is most likely to get wrong.
Three shapes an amendment stream takes
Once you have a name's amendments laid out in order, they tend to fall into one of three patterns.
Escalating. Amendments get closer together. The stake rises through successive filings. The purpose language moves from general concerns to specific demands, and exhibits start appearing, letters to the board, presentations, nomination notices. This is a filer spending money and reputation, and the cadence is a rough proxy for how much of each.
Stalling. Amendments are sparse and mostly administrative. The stake is flat. The purpose section reads the same as it did in the original, sometimes word for word. This is the most common shape and it is the one people misread most often, because the position is still there and still large and it looks like something is happening. Nothing is happening.
Winding down. The stake declines across amendments. Purpose language gets shorter rather than longer. Eventually there is a final amendment reporting the holding has fallen below five percent, which ends the reporting obligation. That last one is a real event and worth catching, because the market often has not noticed that the reason it was interested in this company has left.
Cadence is a weak signal on its own
Two cautions, because amendment counting is easy to overfit.
First, not all amendments are about the campaign. Changes to a credit facility behind the position, changes to the entities holding the shares, pledges, and corrections all generate filings. A month with four amendments where three are structural and one is a two line stake update is a quieter month than the count suggests. Weight by what changed, not by how many landed.
Second, silence is ambiguous. An amendment stream that stops could mean the filer has gone quiet, or it could mean nothing material has happened, or it could mean the campaign has moved into a negotiation that neither side wants disclosed until it concludes. Settlements are frequently invisible until the day they are announced. Do not read a gap as an exit unless you have seen the amendment that reports the stake going below the line.
Third, a rising stake is not automatically conviction. A filer can be adding because the position is working and they want more of it, or because the position has fallen and they are averaging down into something that has not gone their way. The share count alone does not distinguish those, and the amendments will not tell you which it is. Put the filing dates against the price chart before you decide that somebody buying more is somebody being proved right.
What to do with a name whose stream just accelerated
Suppose you own something and its amendment stream has picked up, with the stake rising and a letter attached to the most recent filing. What is the decision this week?
The one I would resist is adding to the position because a campaign is heating up. The escalation is public. It is priced. You are not early to a document that everyone with a filing feed received at the same moment you did.
The useful decisions are about risk rather than size.
- Re-read your exit thesis against the filer's demands. If the campaign succeeds and the company does the thing being demanded, does your position still make sense, or were you long something that is about to be sold, split or levered?
- Check your time horizon against theirs. Campaigns that get anywhere take quarters, often longer. If you cannot hold through that, the campaign is not your catalyst regardless of how right the filer is.
- Decide in advance what a settlement means to you. A campaign that ends with two board seats and a buyback is a common outcome, and the stock frequently gives back the campaign premium on the announcement because the uncertainty that supported it is gone.
And if the stream on a name you own has gone flat for two quarters with a stake that has not moved, treat the activist as scenery. They are a large holder with an opinion, which is a normal condition for a public company, not a catalyst. The position has to stand on its own.