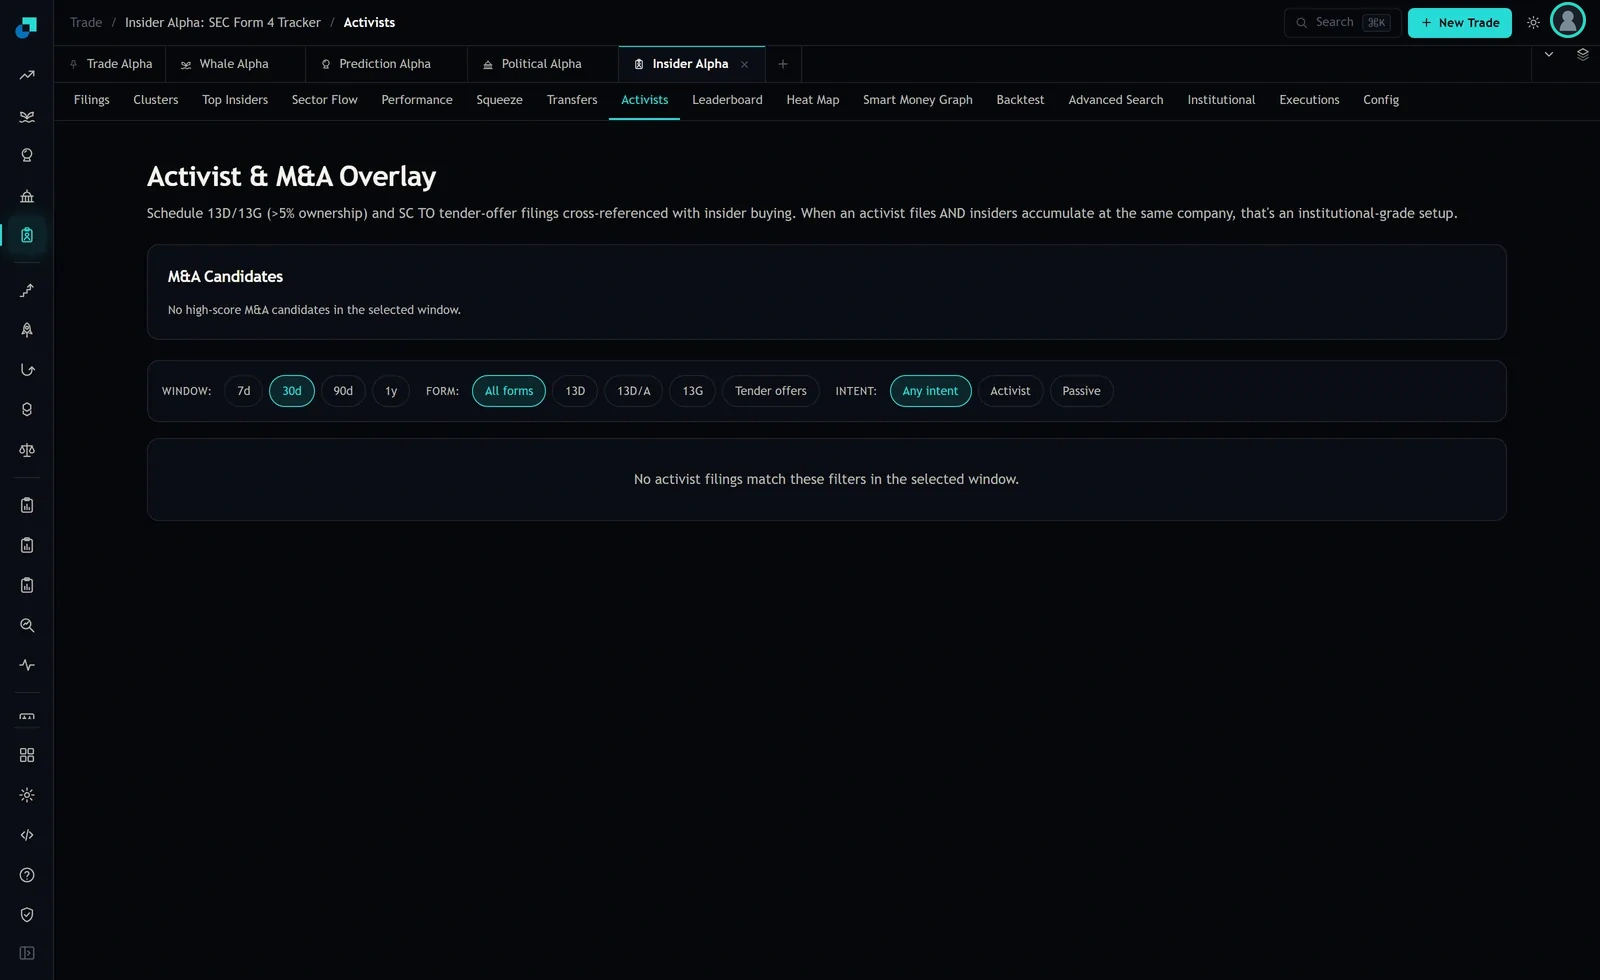
The INTENT row on the Activists tab offers three states, Any intent, Activist and Passive. It is a useful triage control and it encodes a distinction that most ownership data carries in one form or another. It is also the field I see misread more consistently than any other in this dataset.
The misreading is not in the data. It is in what people believe the word passive predicts. Nothing about a short form filer's behaviour is determined by the schedule they filed, and building a process that assumes otherwise produces a specific and repeatable class of surprise.
The tag records an election, not a disposition
The short form schedule is available to particular categories of holder above the five percent line. Qualified institutional investors acquiring in the ordinary course of business qualify. Certain exempt holders qualify. Passive investors below a size threshold qualify, on the condition that the securities are not held with a purpose or effect of changing or influencing control of the issuer.
Read that condition carefully, because it is narrower than the everyday meaning of passive. The certification concerns control. It does not say the holder will not vote its shares. It does not say the holder will not meet management. It does not say the holder has no view on strategy, will not express that view, or will not support somebody else who does. A holder can do all of those things and remain properly on the short form, because none of them amounts to a purpose of changing or influencing control.
So the tag is a fact about a legal filing made by counsel against a defined standard at a point in time. Treating it as a behavioural forecast is a category error, and the error belongs to the reader rather than the filer.
Three ways a short form holder ends up acting like an owner
These are ordinary situations, not edge cases, and none of them implies anything improper by anyone.
The institution that votes its book. Large asset managers publish stewardship policies and voting guidelines, and they apply them across thousands of positions. A holder can vote against a compensation plan, against a director, or in favour of a dissident slate, entirely as a matter of published policy. That is not a control purpose, it is a fiduciary function performed at scale. But if your model reads passive as supportive of incumbent management, this holder will surprise it, and they will surprise it in the exact meetings where the vote is close.
The staged position. A holder can accumulate over months with a genuinely passive thesis, file the short form correctly, and later reconsider as circumstances change. Management misses a plan, an asset sale falls apart, a competitor makes an offer. The certification described the purpose at the time it was made. When the purpose changes, the holder moves to the long form schedule. Everything about that sequence is normal, and the holder was not misclassified before the switch. They were correctly classified under conditions that no longer hold.
The index sleeve. A firm can hold the same name in a passively managed vehicle and in an actively managed one, with different decision makers and different mandates. The aggregated filing is a legal aggregation and it tells you very little about how any individual pool of that money behaves. Reading a single tag across a position assembled from several distinct mandates is reading an average of things that do not average.
Tests that reclassify without accusing anyone
The question worth answering is not whether a filer is really passive. It is how likely this holder is to engage, and that is estimable from public behaviour without making any claim about anyone's certification.
- Concentration in the holder's own book. A five percent stake that represents a meaningful share of the manager's total assets is a different animal from the same five percent sitting inside a broad portfolio of hundreds of names. Position weight in their book, not in the issuer's register, is the best single proxy for how much attention this holder can afford to pay.
- Published voting record. Many institutions disclose how they voted. A holder with a documented pattern of voting against management on contested items has told you something concrete about their disposition, in public, in their own filings.
- History of form transitions. Has this manager moved from the short form to the long form at other issuers, and how often? That is a checkable, dated, public fact and it is the strongest available base rate for whether they might do it again.
- Vehicle type. Whether the holding sits in index tracking vehicles, where voting follows policy, or in discretionary mandates, where it follows a manager's view.
Every one of these is public, checkable and dated. That is deliberate. It matters for what you are allowed to write down.
Writing the reclassification into the file
Replace the binary tag with two fields, and keep them separate in the record.
The first is the filing election, taken from the form type. It is a fact, it has a source document, and it should never be overwritten by anyone's judgement. This is the field that appears in anything a compliance officer, an auditor or a client reads.
The second is an engagement propensity estimate. It is yours, it is derived from the tests above, and it should carry a date and a named owner. A subjective field with an owner and a date is a defensible input. The same field with neither is how a desk ends up unable to explain its own process a year later.
One rule about language, and it is not optional. Never write an accusation into a research file. "This manager has moved from the short form to the long form at four issuers in three years" is a verifiable statement about public filings. "This filer is secretly running a campaign" or "this filer's certification is inaccurate" are claims about someone's compliance with a legal standard that you cannot substantiate, and they will be read back to you in circumstances of somebody else's choosing. The analytical point survives the careful phrasing entirely. The careless phrasing adds nothing except exposure.
The practical outcome of all this is a screen you use differently. INTENT set to Passive is a way to pull a review set quickly. It is not a way to conclude that a set of holders will sit still, and any risk model that assumes a passive register cannot become an active one has assumed away the situation it most needs to survive.