Earnings are an opinion and cash is a fact. That line gets repeated so often it has stopped meaning anything, which is a shame, because the practical version of it is one subtraction you can do in ninety seconds and it is the earliest warning most companies give before a bad quarter.
Take net income for the period. Take cash flow from operations for the same period. Subtract. In a healthy business the second number is usually larger than the first, because depreciation is a real charge against profit that takes no cash out. When net income starts running ahead of operating cash flow, and keeps doing it, something is being recognised as profit that has not arrived as money.
The subtraction, and what a healthy answer looks like
Both figures are on the face of the statements and neither requires adjustment. Net income is the bottom of the income statement. Cash flow from operations is the subtotal at the end of the first section of the cash flow statement.
For a mature business with modest growth, operating cash flow typically runs somewhere between one and a quarter and two times net income, and the gap is mostly depreciation. A ratio persistently below one is the thing to notice. It means the company reported profit that has not converted to cash, and the difference is sitting somewhere on the balance sheet as a receivable, as inventory, or as a capitalised cost.
One year of that means nothing on its own. A company that won a large contract with ninety day payment terms will show exactly this pattern and be in perfect health. What makes it informative is persistence and direction, which is why the rule at the end of this piece is built on two consecutive periods rather than one reading.
The cycle underneath the gap
The gap tells you cash is stuck. The cash conversion cycle tells you where.
Three components. Days sales outstanding is receivables divided by revenue times the days in the period, and it is how long customers take to pay. Days inventory outstanding is inventory divided by cost of goods sold times days, and it is how long goods sit before selling. Days payable outstanding is payables divided by cost of goods sold times days, and it is how long the company takes to pay its own suppliers. The cycle is the first plus the second minus the third.
Compute all three for the last four periods and look at which one is moving. Rising receivable days with flat inventory means customers are paying more slowly, which is either a deliberate concession to win business, a sign of stress in the customer base, or revenue booked on terms that flatter the current period. Rising inventory days means product is not selling at the rate production assumed, and inventory that is not moving becomes a write-down eventually. Rising payable days is the company financing itself off its suppliers, which works until a supplier tightens terms.
Each of those has a different implication and the aggregate cycle figure hides all of it. Look at the components.
The multiple that sits on top of the number in question
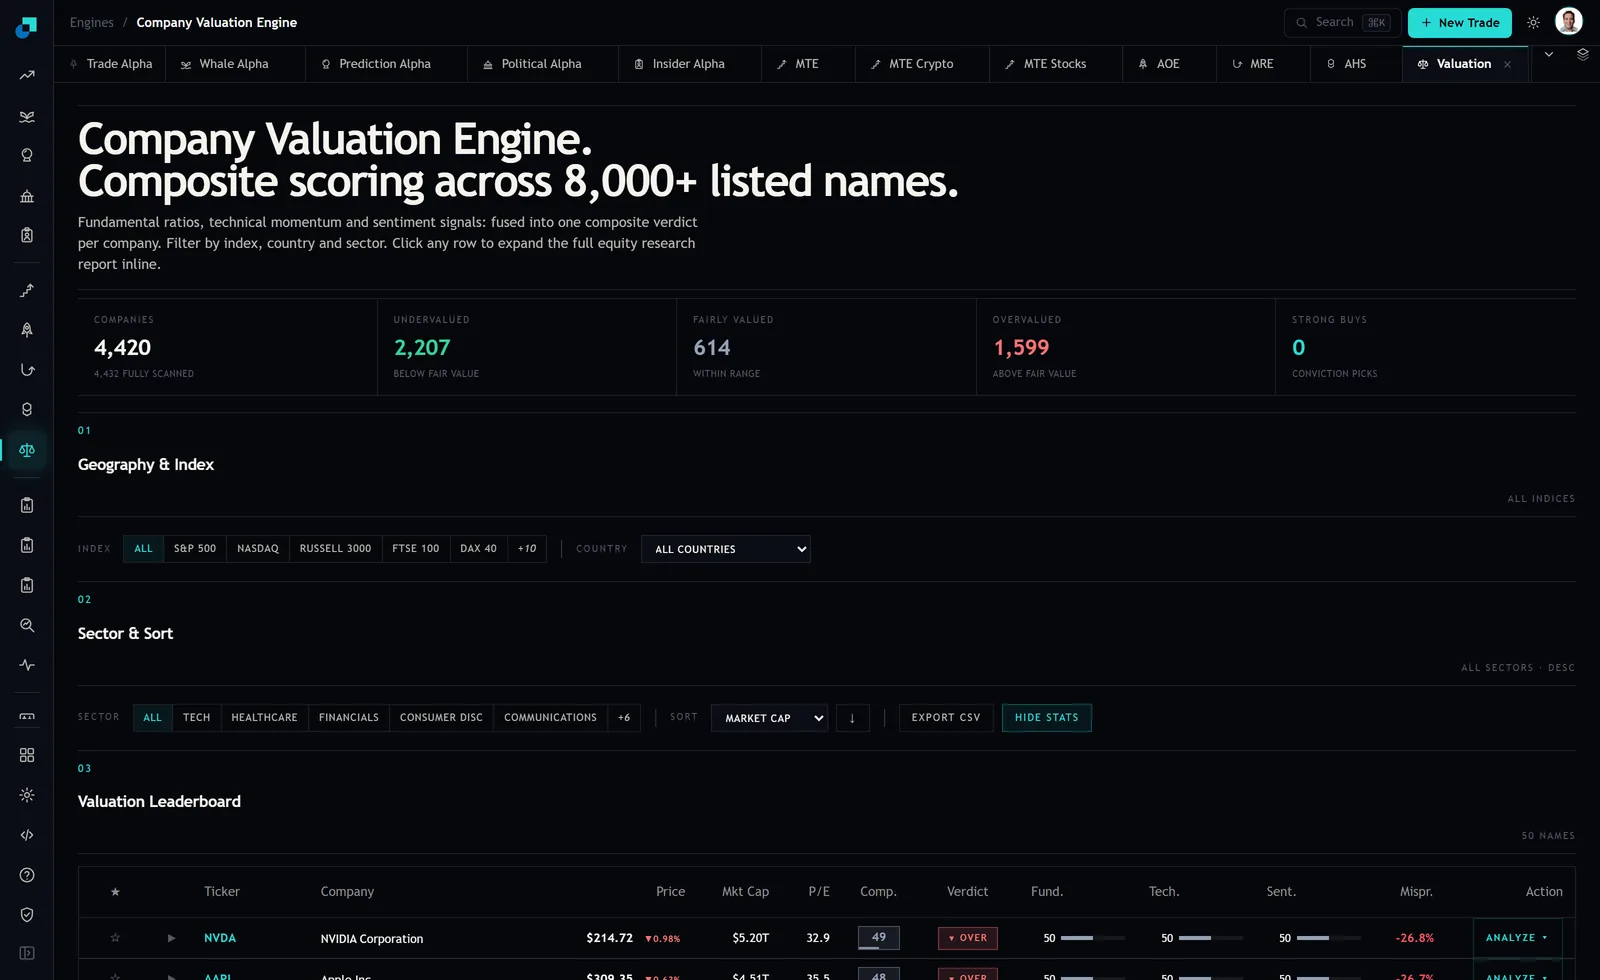
That absence is the practical point for anyone using a screen this way. A board like this can rank a universe that read 4,420 companies at capture and hand you a shortlist in seconds, which is genuinely more than a private investor can do by hand. What it cannot do is tell you whether the earnings underneath the multiple converted to cash, because the cash flow statement is not among the columns. The screen narrows the field. The subtraction is yours.
A gap that precedes a miss, in numbers
Made-up figures, kept round. A company reports 200 of net income in a year and 240 of operating cash flow, a ratio of 1.2, which is unremarkable. Receivable days sit at 55.
The next year net income is 240 and operating cash flow is 210. The ratio has fallen below one. Receivable days have gone to 72. Revenue grew fifteen percent and receivables grew thirty five percent.
Nothing has been reported as bad news. The earnings line grew twenty percent and the headline is a good year. But the company has recognised roughly 30 more of profit than it collected, and receivables are growing at more than twice the rate of sales. Whatever those extra receivables are, one of three things happens to them. They get collected late, which delays cash and shows up as another weak year. They get collected never, which shows up as a bad debt charge against a future quarter. Or the terms that created them get withdrawn, which shows up as a revenue slowdown the moment the concession stops.
All three of those land in the following twelve to eighteen months, and all three are visible now, in figures the company published itself, without any special access or insight.
The gaps that are not warnings
Four situations produce this pattern in healthy companies and you will misread all four if you apply the rule mechanically.
Fast growth. A company growing revenue at forty percent has to fund receivables and inventory ahead of collecting, so operating cash flow lags net income structurally. Check whether the working capital growth is roughly proportional to revenue growth. Proportional is fine. Materially faster is not.
Seasonality. Comparing a fourth quarter to a third quarter on a business with a concentrated selling season produces nonsense. Compare the same quarter year on year, always.
Acquisitions. An acquired business arrives with its own receivables and inventory, and the balance sheet jumps while the income statement only includes the period since closing. Use the year after the deal as your baseline rather than trying to adjust.
Deferred revenue models. Subscription businesses collect in advance, so their cash flow runs ahead of earnings and the ratio is high. When it falls toward one at such a company, that is a much stronger signal than the same movement elsewhere, because it means the advance collection is slowing.
The two-quarter rule worth adopting
For each name you hold, one line in a file, updated when results are published. Net income, operating cash flow, the ratio between them, and receivable days.
The threshold I use is two consecutive quarters where the ratio is below one and receivable days have risen year on year in both. One quarter is noise and acting on it will have you selling good businesses on timing effects. Two consecutive quarters of both conditions is rare in a healthy company and common in a company about to disappoint.
What you do when it triggers depends on the position, but the minimum is that any thesis resting on the reported earnings figure now needs a different support, because the reported earnings figure is the number the pattern is questioning. If you cannot restate the case for the position using cash rather than earnings, you are holding on the strength of a number that the company's own cash flow statement has stopped confirming.