The screen is full of companies that have never earned a cent, several of them large, and the ordinary tools stop working on all of them at the same point. There is no price to earnings ratio because there are no earnings. There is no earnings yield to compare against a bond. The one shortcut left is a revenue multiple, and a revenue multiple is not analysis, it is a way of copying what someone else paid.
What you can do instead takes an afternoon and it is not sophisticated. You build the company back up from one customer, or one subscription, or one delivery, and you ask what that unit earns once the business stops growing. Everything else follows from that.
The column that goes blank
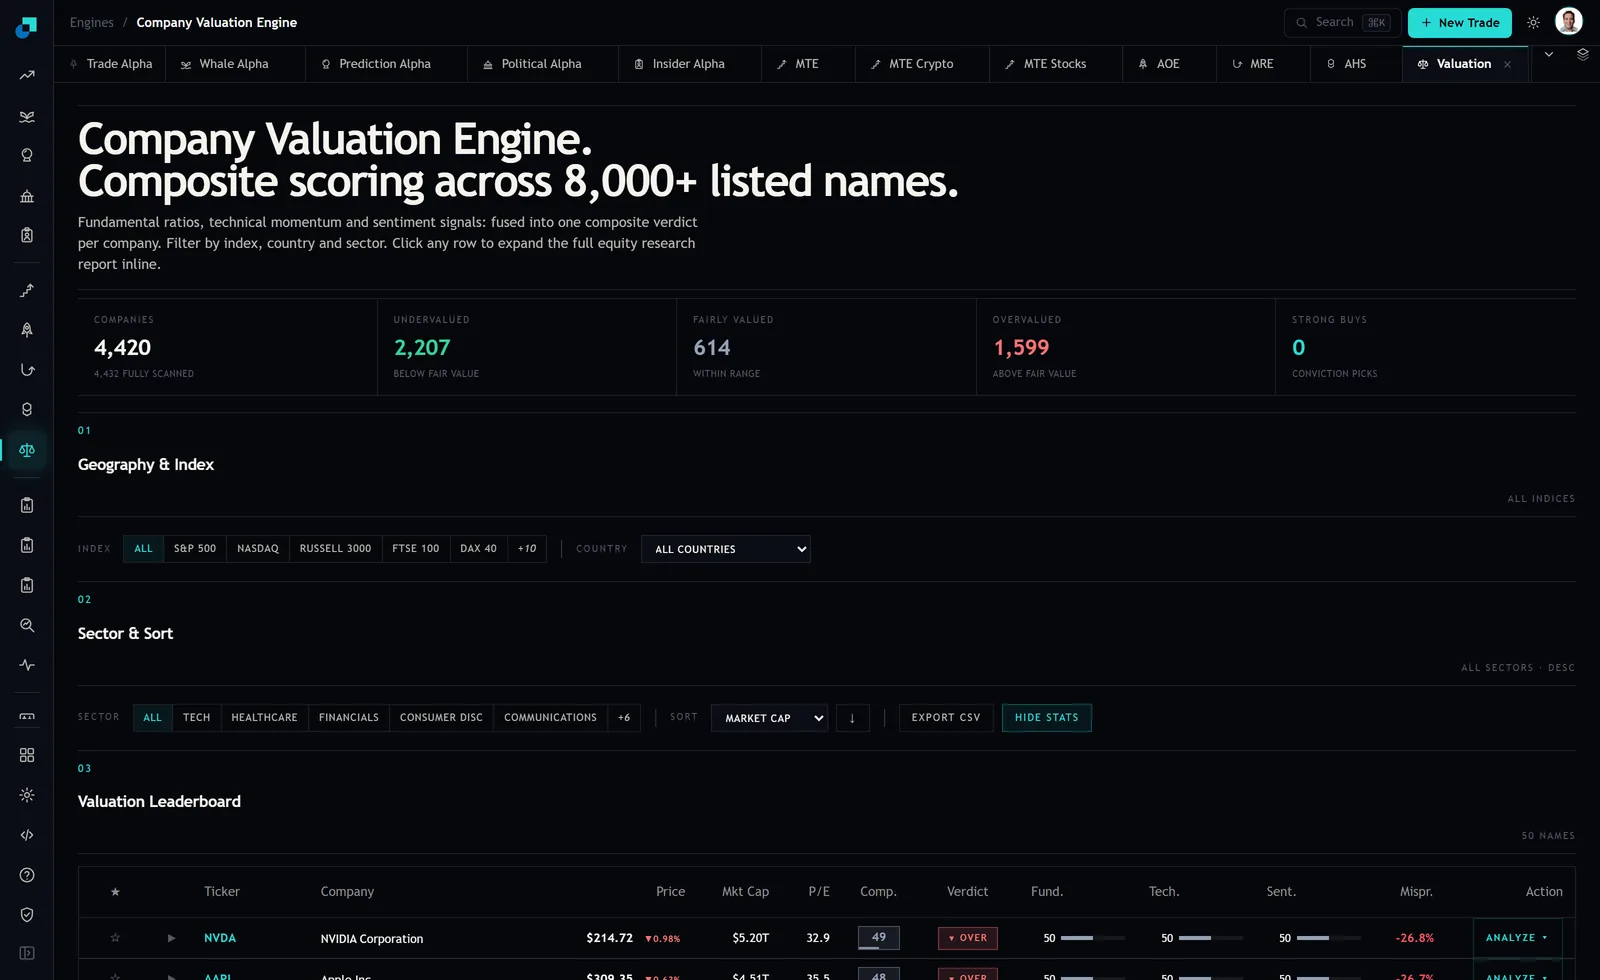
Notice what the rest of the row still gives you. Price, market cap, a composite score, a verdict, three sub-scores and a mispricing percentage, across a board that read 4,420 companies at capture with 4,432 fully scanned. All of that continues to function for an unprofitable company. Only the earnings ratio drops out, and it drops out precisely for the companies where the valuation question is hardest.
So use the board for what it does well, which is narrowing several thousand names to a list you can actually read, and accept that the number you need for a loss-maker is not on it. There is no revenue line, no gross margin and no customer count anywhere on the view. Those come out of the quarterly report, and the good news is that you only need three figures from it.
Start with one customer, not with the company
Three numbers, and all of them are either disclosed or derivable from disclosed figures.
Revenue per customer per year. If the company reports customer or subscriber counts, this is division. If it does not, use the closest available unit, which might be revenue per store, per vehicle, per active account or per delivery. The unit does not need to be perfect, it needs to be stable enough that you can track it.
Gross margin. Revenue minus cost of revenue, as a percentage. Take it straight from the income statement and do not adjust it.
Cost to acquire a customer. Total sales and marketing spend for the year divided by net new customers added. This overstates the true cost when marketing also supports existing customers, and understates it when growth is coming from a backlog signed years ago. It is still the most useful crude number available, and consistency over time matters more than precision in any single year.
From those three you get payback in months, which is acquisition cost divided by monthly revenue per customer times gross margin. Under twelve months and growth funds itself reasonably quickly. Beyond twenty four and every new customer is a call on the balance sheet, which means the share count is going up and your stake is going down.
Contribution margin is the number that has to scale
Gross margin flatters most loss-makers, because the genuinely variable cost of serving a customer sits partly below the gross profit line in support, hosting, payment processing and logistics. Contribution margin is revenue minus everything that varies with volume, before any share of head office.
Estimate it, do not agonise over it. Take gross profit and subtract a reasonable slice of the operating cost lines that clearly move with customers. If support headcount has grown in step with accounts, that cost is variable no matter which line it is reported on.
Then look at the trajectory over three or four years, which is where the answer actually is. A company whose contribution margin has climbed from twenty two to thirty one percent while revenue tripled is demonstrating something real. A company whose contribution margin has been thirty percent for four straight years while revenue tripled has demonstrated the opposite, and the profitability case now depends entirely on spreading fixed costs, which is a slower and much smaller effect than most narratives around these names assume.
A path to profitability in round numbers
Made up figures, kept simple. A company has revenue of 500 and an operating loss of 150. Contribution margin is thirty percent, so contribution is 150. Fixed costs, meaning research and development plus general and administrative expense plus the non-variable part of sales and marketing, come to 300. That is the whole model, and it explains the loss exactly.
Now the question is no longer a vague one about the future. It is arithmetic. To break even at a thirty percent contribution margin, the company needs contribution of 300, which means revenue of 1,000, which means doubling. If fixed costs grow ten percent a year while revenue doubles over three years, fixed costs reach roughly 400, break-even revenue rises to about 1,333, and the company needs to grow 167 percent rather than 100 percent to get there.
That is the entire trick. Fixed costs are not fixed over a three year horizon, and pretending otherwise is what makes break-even dates slip year after year in exactly the pattern these companies exhibit.
Then push it one step further. At revenue of 1,500, contribution is 450 and fixed costs are perhaps 450, so operating profit is around zero. At revenue of 2,500 with fixed costs at 550, operating profit is 200, a terminal operating margin of eight percent. That eight percent, not a revenue multiple, is the assumption your valuation actually rests on, and now it is written down where you can be wrong about it visibly.
Apply tax, apply a discount rate, discount the whole path back, and divide by a share count that you have adjusted upward for the dilution the payback calculation implied. The output is a number with a derivation attached, which means when the price moves you can tell whether the case changed or only the quote did.
Where this goes wrong for people who hold these names
Three failures, and I have made all three.
Using management's adjusted profitability measure as the target. Companies with no profits report a measure that excludes stock compensation, and stock compensation for these businesses is a real cost paid in your ownership rather than in cash. If the adjusted figure is positive and the share count is rising six percent a year, the cost did not disappear, it moved onto your side of the ledger. Model the share count explicitly and the adjusted number stops mattering.
Extrapolating the growth rate that produced the break-even date. The arithmetic above needs the company to double. If growth is decelerating, the doubling takes longer, fixed costs grow through the extra years, and the target moves away faster than you approach it. Test the model at the growth rate of the last two quarters annualised, not at the three year average.
Treating the terminal margin as an input you are entitled to choose. Eight percent and eighteen percent produce valuations that differ by more than double, and there is a strong temptation to pick the one that supports the position you already hold. The defence is to write the terminal margin down before you look at the share price, then not move it. If you cannot make the case at the margin you wrote down first, the position is too big.