Every revenue multiple contains an implied terminal margin. Eight times forward sales at a twenty five times exit earnings multiple implies a terminal net margin of thirty two percent, and if you did not intend to assert that, you asserted it anyway by choosing the multiple. The reason revenue multiples survive in memos is not that they are informative. It is that they let the analyst avoid writing down the assumption that is doing all the work, which means the committee cannot argue with it and the attribution afterwards cannot test it.
Cohort economics is the alternative, and its real advantage is procedural rather than analytical. It relocates the argument from a multiple, where disagreement is aesthetic, to three quantities that can be tracked quarterly and either confirmed or falsified inside the holding period.
Define the population before you define the method
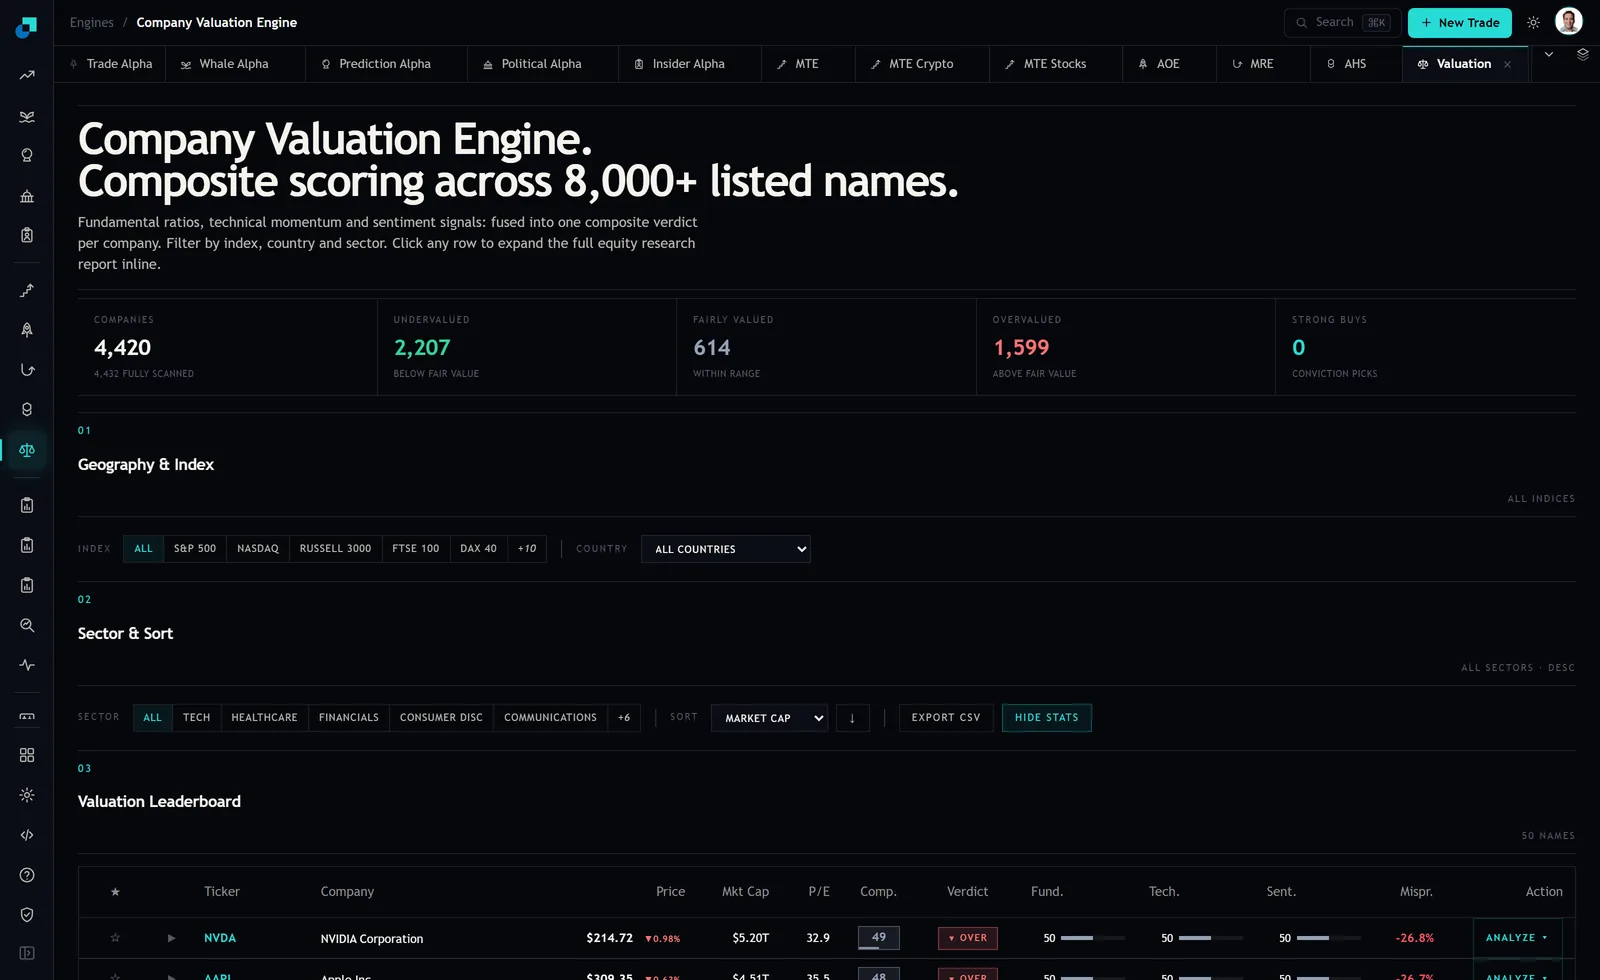
That distinction is not a criticism of the tool, it is the ordinary condition of any scored universe and the reason population definition belongs at the top of the memo rather than in an appendix. The board carries Price, Mkt Cap, P/E, a composite, a verdict, three sub-scores and a mispricing percentage. There is no revenue line, no gross margin, no customer count and no cohort disclosure anywhere on the view, and the only earnings-based ratio present is a price to earnings ratio, which for a company with negative trailing earnings conveys nothing whatever it renders as.
So the workflow is a two stage one and should be described that way in writing. The platform supplies a filtered, consistently scored candidate list across index, country and sector, exportable as a file. The cohort layer is built by the analyst from filings, supplemental disclosure and investor day material, keyed to the same identifiers. Anyone reviewing the process later needs to see that boundary drawn explicitly, because the failure mode is an analyst quoting a platform verdict and a hand-built cohort model in the same paragraph as though they came from one system.
The three quantities, and what each one constrains
Retention first, measured on revenue rather than logos. Gross revenue retention tells you what the cohort keeps before any expansion, and it is the number that determines whether the business is a leaky bucket. Net revenue retention includes expansion and is the one management prefers to quote, frequently above one hundred percent, which is genuinely impressive and also compatible with churning a third of customers if the survivors expand hard enough. Underwrite gross retention and treat net retention as upside, because in a downturn expansion stops first and churn arrives second.
Payback period second. Fully loaded customer acquisition cost divided by gross-margin-adjusted monthly revenue per new customer. Fully loaded means all of sales and marketing, not the portion management attributes to new logos, because the split is an internal allocation you cannot audit. Payback is what converts growth into a cash requirement. A twelve month payback growing at forty percent is self-funding within a couple of years. A thirty month payback at the same growth rate is a financing plan wearing a growth narrative, and the equity underwriting has to include the dilution.
Contribution margin third, meaning revenue less cost of revenue less the variable cost of serving the customer, before any allocation of central overhead. This is the quantity that scales, and it is the anchor for everything downstream. If contribution margin is thirty percent today and has not moved in three years while revenue tripled, the terminal margin case has to rest on operating leverage over fixed costs alone, which is a much narrower argument than the one usually presented.
Building a terminal margin you can defend line by line
The construction is deliberately mechanical. Start from the current contribution margin. Add whatever expansion in it you can attribute to a specific mechanism, with the mechanism named. Hosting cost per unit falling as committed spend discounts step up is a mechanism. Support cost per account falling as self-service deflects tickets is a mechanism. Scale is not a mechanism, it is a word people use when they do not have one.
Then subtract the fixed cost base at maturity as a percentage of terminal revenue. Research and development does not go to zero at scale and neither does general and administrative expense, and the honest way to set these is to take the same lines from three mature businesses with comparable delivery models and use the range rather than a point.
What comes out is a terminal operating margin with an explicit derivation. When it lands materially above the mature comparables, that is not automatically wrong, but it now requires a stated reason that survives being read aloud. In my experience the derivation itself does most of the work, because an assumption that has to be built from named components in front of other people tends to arrive lower than the same assumption chosen as a round number.
Add a sensitivity on the two inputs the outcome is most exposed to, which are gross retention and terminal margin, and present the equity value across the grid rather than as a point estimate. A committee that sees the grid asks better questions than one that sees a single number and a confident tone.
When the disclosure is not there, which is most of the time
Cohort tables are voluntary disclosure and most listed companies do not provide them. The memo has to be explicit about which of the three quantities is measured, which is estimated, and which is assumed, because that distinction is what a reviewer will want eighteen months later when the position has gone wrong.
Gross retention can often be bounded rather than measured. Total revenue growth minus disclosed new customer contribution gives an implied same-customer growth rate, which is a floor on retention if you are careful about the timing of when new cohorts start contributing. Payback can be estimated from sales and marketing spend against net new annual recurring revenue, which overstates efficiency where there is a long sales cycle, so state the direction of the bias rather than pretending there is none. Contribution margin is the one you can usually get closest to, since cost of revenue is disclosed and the variable service cost can be bounded from headcount and support metrics.
Where a quantity cannot be bounded at all, the honest response is to size the position for that uncertainty rather than to fill the gap with a comparable. A number imported from another company's disclosure is not evidence about this company, and it will not read as evidence in a review.
The quarterly test that makes this different from a multiple
The reason to prefer this construction is that it produces falsifiable checkpoints, and a thesis with checkpoints can be exited on process rather than on price action.
Each quarter, three readings. Has gross retention moved outside the band underwritten. Has payback lengthened by more than a stated tolerance. Has contribution margin progressed along the path assumed, or flatlined. Two consecutive quarters outside band on any of the three triggers a written re-underwrite, not a discussion.
Tie the exit to those readings in the original memo, with the thresholds fixed in advance. The alternative, which is where most pre-profit positions end up, is holding a name whose price has halved while arguing that the multiple is now cheap, having never written down what the multiple was supposed to represent in the first place.