Companies that hold digital assets on their balance sheet and fund those holdings by selling new shares have produced an unusually confusing argument for retail investors. One side says issuing shares is always dilution. The other says the company is buying more coins so holders end up with more. Both are wrong as stated, because whether it helps or hurts you depends entirely on one price, and that price is calculable in about a minute.
Above that price, every share the company sells leaves you with more coins behind each share you own. Below it, every share sold leaves you with fewer. There is no ambiguity and no need to have an opinion about the narrative, the treasury strategy, or what management said on the call. It is a single comparison.
Where the premium comes from, and why it does not enter the calculation
These companies typically trade above the market value of the coins they hold. People explain that premium in various ways, some of them reasonable. The company provides access through an ordinary brokerage account. It can borrow in ways an individual cannot. It has an operating business attached. Some of the premium is simply enthusiasm.
You do not need to adjudicate any of that. The premium is an input to the arithmetic below, not a thing to have a view on, and treating it as a fact to be measured rather than a claim to be argued about is what makes this exercise quick.
What you do need is three figures. The number of coins the company holds, which is disclosed in filings and usually announced when it changes. The number of shares outstanding, which appears on the cover page of the quarterly report as of a stated date. And the current coin price. From those three, net asset value per share is one division, and net asset value per share is the threshold.
Price is on the board and the share count is not
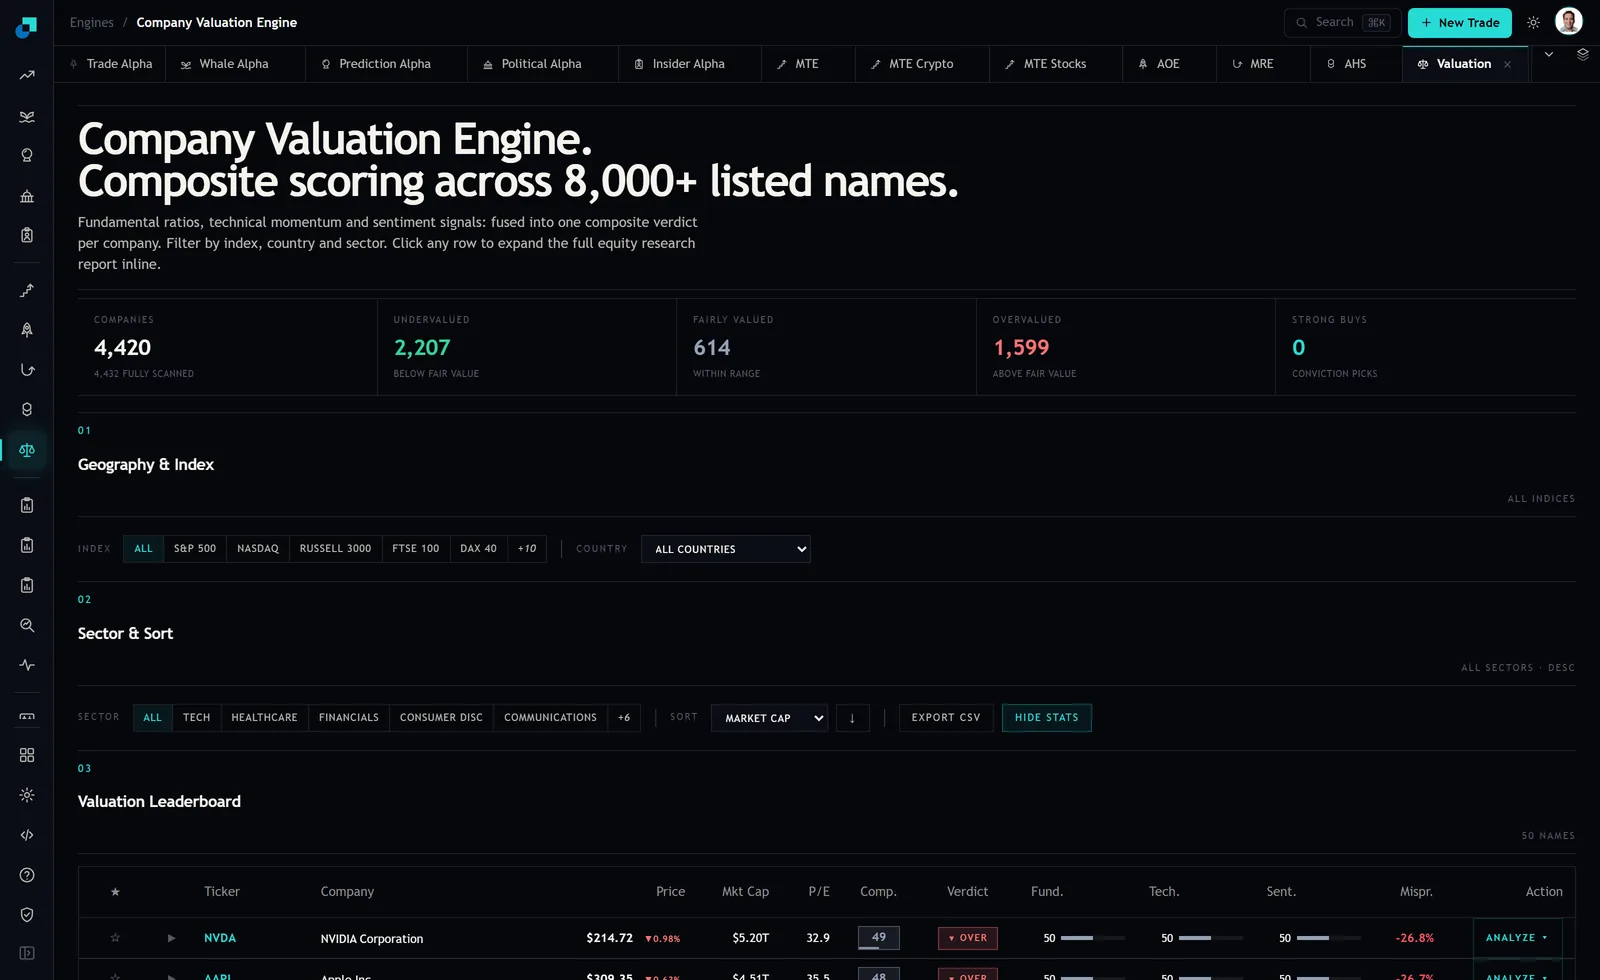
That inference is worth knowing about because it is the one shortcut available on the view. Market capitalisation divided by price gives shares outstanding on the platform's basis, which gets you one of the three figures without opening a document. It will be a basic rather than a fully diluted count, and for a company with convertible notes outstanding the difference is large, so treat it as a starting point rather than an answer.
For everything else the board is doing a different job. It scored 4,420 companies at the time of capture and hands you a filtered, ranked list across index, country and sector, which is a genuinely useful way to find the names in this category in the first place. The coins per share question is arithmetic you run afterwards, on data the screen does not carry.
One formula and the threshold it produces
Write it once and reuse it. Let n be the number of new shares as a fraction of shares already outstanding, and let m be the share price divided by net asset value per share, which is the premium expressed as a multiple.
The change in net asset value per share is n times m minus one, all divided by one plus n.
Everything follows from that. When m is greater than one, meaning the shares trade above the value of the coins behind them, the expression is positive and issuance raises your coins per share. When m is less than one it is negative. When m equals one, issuing shares changes nothing at all for existing holders, whatever the size of the programme.
So the threshold is net asset value per share exactly. Not a comfortable margin above it, not a range. The premium is what creates the accretion, and the size of the premium is what determines how much.
Round numbers to see it move. A company holds 10,000 coins at a coin price of 60,000, so a coin position worth 600 million. It has 50 million shares, giving net asset value per share of 12.00. The stock trades at 18.00, so m is 1.5.
It issues 5 million shares, ten percent of the count, at 18.00, raising 90 million and buying 1,500 more coins. Now 11,500 coins against 55 million shares, a coin position of 690 million, and net asset value per share of 12.545. Existing holders are up 4.5 percent in coins per share without buying anything. The formula gives the same figure directly, since 0.1 times 0.5 divided by 1.1 is 4.5 percent.
The same programme running below net asset value
Nothing about the company, the strategy or the announcements needs to change for this to invert. Only the share price does.
Same company, same 10,000 coins, same 50 million shares, but the stock has fallen to 9.00 against net asset value per share of 12.00, so m is 0.75. The board issues the same 5 million shares, raising 45 million, buying 750 coins.
Now 10,750 coins against 55 million shares. Net asset value per share is 11.73, down 2.3 percent. The press release still says record total holdings, because total holdings did rise from 10,000 to 10,750. Your claim on those holdings shrank.
This is the specific mechanism that catches people, and it catches them because total coins held is the headline number these companies report and coins per share is not. The headline rises in both scenarios. Only one of them was good for you.
The series to keep, and the three things that break it
Keep one line per quarter for any name you hold. Total coins, fully diluted share count, coins per thousand shares, and the coin price on the reporting date. The third column is the one you actually watch, and its direction over four quarters tells you more about management's capital discipline than any presentation will.
Three complications to handle deliberately rather than ignore.
Convertible notes. If the company has convertibles outstanding, the shares that would appear on conversion are already effectively there for this purpose. Use a fully diluted count that includes them, and expect it to be materially higher than the cover page figure. Using the basic count flatters coins per share for exactly as long as the notes remain unconverted.
Coins bought with borrowed money. Debt funded purchases raise coins per share immediately and add a claim ahead of yours. Track net coins per share as well, meaning the coin position less debt at face value, divided by shares. When the two series diverge, the divergence is leverage, and leverage cuts both ways with a violence that the accretion arithmetic alone does not convey.
Issuance you cannot see yet. Programmes are announced with a total capacity and drawn down over time, and the drawdown appears in the next quarterly report rather than when it happens. Between reports, assume the programme is being used if the stock is above net asset value, because that is when using it is in existing holders' interest and management generally knows it.
The practical rule this leaves you with is short enough to remember at the point of purchase. Work out net asset value per share, compare it to the quoted price, and know which side of the line you are standing on. Buying above it means future issuance works in your favour and you are paying a premium for that. Buying below it means the opposite, and any issuance that follows is coming out of your position.