Management quality is the most commonly asserted and least commonly measured input on a research desk. It appears in memos as a paragraph, it survives review because nobody can falsify it, and it does real work in position sizing without ever being tested. The reason is not laziness. It is that the obvious measurements are annoying to construct and the obvious shortcuts are worthless.
Capital allocation is the part of management quality that is actually measurable, because every dollar of discretionary cash goes to one of a small number of destinations and each destination leaves an auditable trail. What follows is a scorecard that produces one comparable number per name across a coverage list, using a decade window, with the components kept visible so a disagreement is about a component rather than about a person.
Three uses of a dollar and one comparable unit
Strip out the compulsory spending and what remains goes to buybacks, to acquisitions, or back into the existing business beyond maintenance. Dividends sit outside this framework deliberately, since a dividend policy is a signalling decision that is rarely reversed and tells you more about the shareholder register than about judgement.
The comparable unit for all three is a spread in percentage points against a specific, named alternative. Not a return, a spread. This matters because a ten percent return on acquisitions in a period when the cost of capital was six is a good outcome, and the same ten percent in a period when the company's own shares were yielding fourteen is a bad one. Every component below resolves to the same question, which is what the alternative was and by how much the chosen path beat it.
Buyback timing against the dumbest possible programme
The benchmark for repurchases is not zero and it is not the market. It is a constant-dollar programme, meaning the same amount spent every quarter regardless of price, which is what a company with no view would do and which mechanically buys more shares when the price is low.
Compute the dollar-weighted average repurchase price over the decade from the cash flow statement and the share count movement. Compute the simple average price over the same period. The difference, expressed as a percentage of the simple average, is the timing spread. A company that consistently bought below its own decade average price scores positive. A company that bought heavily at highs and stopped during drawdowns scores negative, and this pattern is extremely common because buyback capacity correlates with cash flow, which correlates with the top of the cycle.
Two adjustments keep this honest. Net the repurchases against issuance, since a company buying five percent of shares while issuing four percent to employees is running a payroll settlement, not a return of capital. And exclude any repurchase executed under an accelerated structure with a fixed price, since the timing decision was not the company's.
The coverage list this scorecard has to attach to
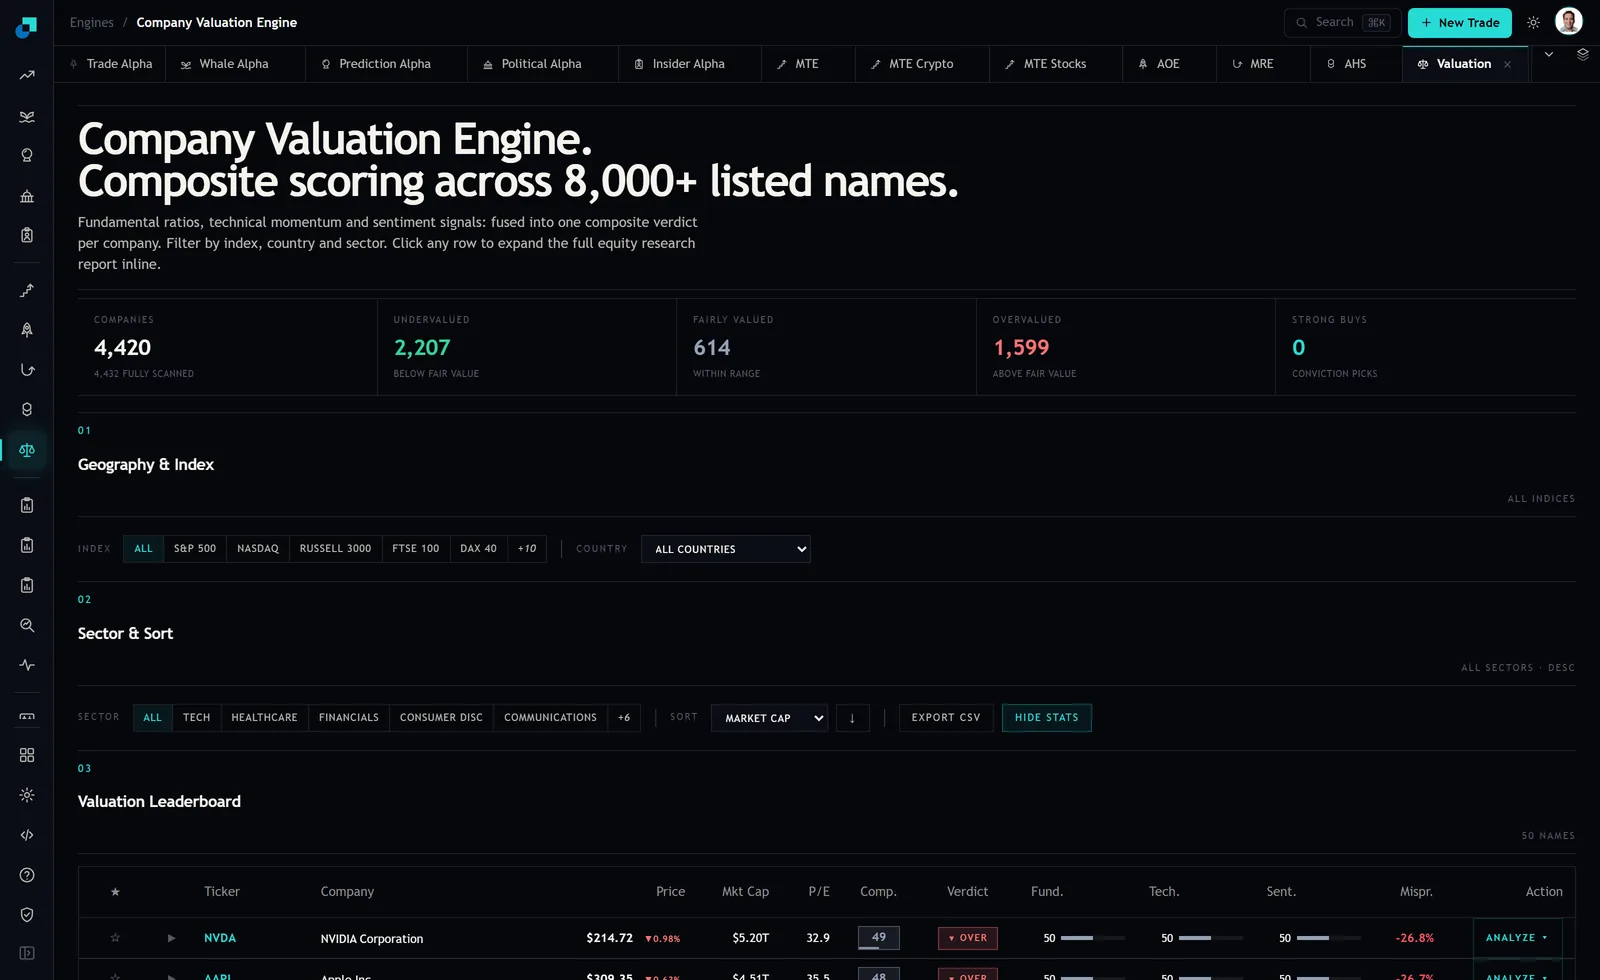
The screen itself will not produce any of the numbers below. There is no repurchase column, no acquisition history, and no capital expenditure line on this view, so the scorecard is entirely an offline construction fed by filings. What the board is good for is defining the population and doing it reproducibly, since the sector and index filters give you a stated universe you can write down in a policy document. The scorecard then runs against the starred subset, and the version of the subset in force at any date is what makes a later attribution review answerable.
Acquisitions without the goodwill excuse
The standard defence of a bad acquisition record is that goodwill impairments are non-cash and backward looking. Both statements are true and neither is relevant, because the cash left the building at closing.
Measure it as an incremental return. Take the cumulative cash consideration paid for acquisitions over the decade, including assumed debt, and treat it as invested capital deployed. Then measure the change in consolidated after-tax operating profit over the same window, net of an estimate of what the organic business would have produced without the deals. That last term is the hard one and there is no way to avoid making an assumption about it. State the assumption explicitly, use the same one for every company in the list, and the cross-sectional comparison stays valid even if the level is arguable.
Divide incremental profit by cumulative consideration. Subtract the company's cost of capital averaged over the window. That spread is the acquisition score. Lag it, since a deal closed in year nine has not had time to produce anything, so the numerator should only include deals with at least three years of ownership and the denominator should exclude the rest.
Expect the distribution to be unflattering. Serial acquirers with a positive spread over a decade are a small group, and identifying them is most of the value of running this exercise at all.
Organic reinvestment yield, which nobody computes
The third destination is the existing business, and it is the one where the scorecard is most informative because it is least discussed. Take cumulative capital expenditure above depreciation plus cumulative research and development over a rolling three year window, which is the discretionary reinvestment. Take the change in after-tax operating profit from the end of that window to two years later. Divide.
That ratio is the incremental return on organic reinvestment, and comparing it to the acquisition spread computed above answers a question a portfolio manager asks constantly and usually cannot support. When a company with a fourteen percent organic reinvestment yield buys a business at an implied seven, the scorecard has caught management preferring size to return, and it has caught it with a number rather than an adjective.
Collapsing to one figure, and the four traps in doing so
Convert each of the three spreads to a within-sector z-score across the coverage list, cap them at plus or minus two standard deviations, and weight them by the share of discretionary cash that actually went to that destination over the decade. A company that never made an acquisition should not be scored on acquisitions, and a fixed equal weighting would score it on nothing. Weighting by deployment means the composite answers what management did with the money it had.
Four traps, each of which has spoiled a version of this scorecard.
- Tenure boundaries. A decade window frequently spans two or three chief executives. Either cut the window at the tenure boundary and score the incumbent only, or accept that the score describes the company rather than the person, and never let a memo silently switch between the two readings.
- Survivorship in the coverage list. Scoring only names currently held guarantees a flattering distribution. Run the scorecard on every name that entered the list at any point in the decade, including those exited at a loss.
- The cyclical denominator. Reinvestment yields measured from a trough to a peak look extraordinary and mean nothing. Anchor windows to a full cycle where the sector has one, or report the score alongside the position in the cycle at each endpoint.
- Score inflation on refresh. Once the number is in a memo template, the temptation is to recompute it whenever a name is being defended. Refresh annually on a fixed calendar date for the whole list at once, and stamp the version.
What this buys you in a review meeting is narrow and real. When a position goes wrong and the question is whether the thesis rested on management judgement, the answer is a number computed before the position existed, with three components anyone can dispute individually, on a list assembled by rule. That is a different conversation from defending a paragraph, and it is the only version of the management quality discussion that has ever survived one of those meetings intact in my experience.