An allocation to a listed company that holds digital assets on its balance sheet is frequently presented internally as a proxy for the asset itself, sometimes with a leverage kicker attached. That framing survives about twenty minutes of document work. What the shareholder owns is a residual claim on an operating entity, behind whatever debt sits above it, subject to whatever the custody arrangements actually say, and diluted by whatever issuance authority the board already has in hand.
Four questions decide how much of the coin exposure genuinely reaches you, and none of them appear in the headline holdings figure that these companies market on. All four are answerable from filed documents in an afternoon, and the answers vary far more across issuers than the uniform pitch would suggest.
Owning the coin versus being owed the coin
The first question is what the entity holds and where. There is a real difference between an asset held in the reporting entity's own name at a regulated custodian, an asset held in a subsidiary, an asset held on an exchange, an asset held through a fund wrapper, and a receivable against a counterparty who holds the asset. All five get described as holdings in a press release. Only some of them are bankruptcy-remote from a failure at the counterparty.
Read the custody discussion for four specifics. Whether the custodian is a qualified custodian under a named regulatory regime or a commercial counterparty with a service agreement. Whether the arrangement permits rehypothecation or lending of the assets, which converts a holding into a credit position. Whether any portion is pledged as collateral against borrowings, since pledged coin is not free exposure and it is the first thing to leave in a drawdown. And what the stated insurance actually covers, which is almost always operational failure at the custodian and never price.
Note also what a proof of reserves attestation is and is not. It evidences control of addresses at a point in time. It does not evidence the absence of offsetting liabilities, and it is not an audit opinion. Where an issuer offers one in place of audited disclosure, that substitution is itself a finding.
A composite with a sentiment channel in it
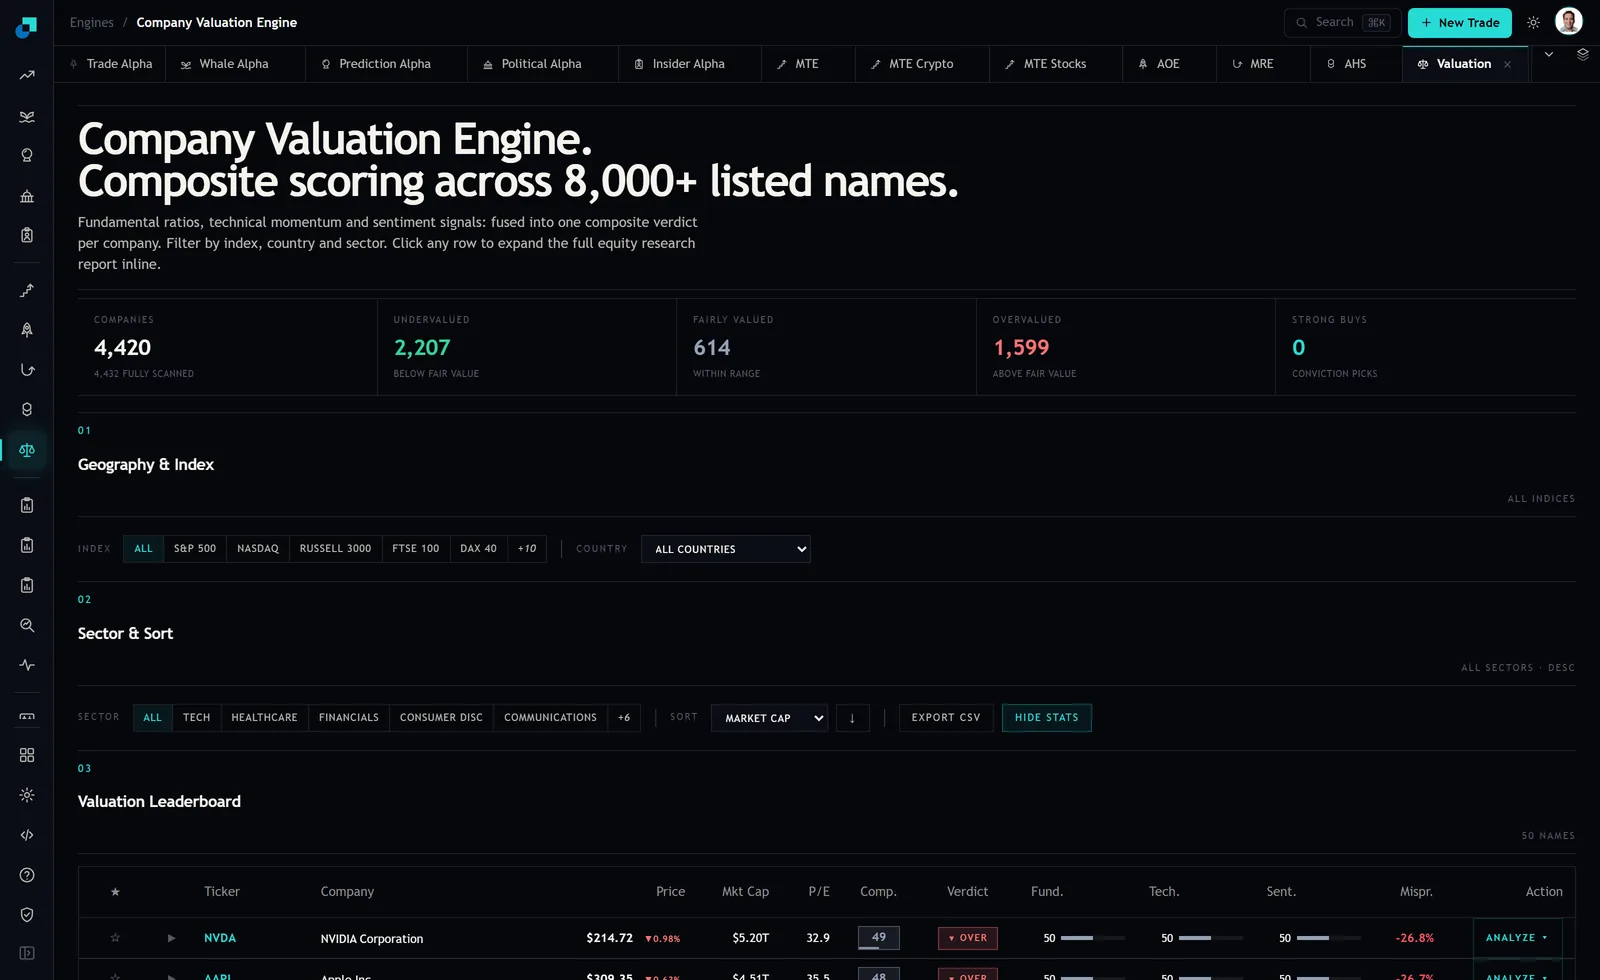
That absence is not a shortcoming to work around, it is the ordinary division between a screening layer and a diligence layer, and the allocation memo should say so in as many words. The engine defines and filters a scored universe, 4,420 companies at the time of capture with 4,432 fully scanned, across index, country and sector, and exports it. The four checks here are built from the annual report, the convertible indentures and the shelf documents, keyed to the same identifiers, and maintained by whoever owns the position.
The accounting basis is not the exposure
Reported numbers on these companies have to be read against the policy note rather than taken at face value, because two different treatments have been in circulation and they produce almost opposite distortions.
Under an intangible asset model with impairment, the carrying value ratchets downward only. It marks to the lowest price observed since acquisition and never recovers on the way back up, so book value understates the position, sometimes enormously, and reported losses appear in quarters where the asset actually rose. Under a fair value model, the carrying value tracks the market and the income statement absorbs the full price swing, so reported earnings are dominated by an asset move that has nothing to do with the operating business.
Neither basis is wrong and neither is informative about the exposure. Find the policy note, establish which basis applies, and then discard the reported earnings line for valuation purposes entirely. The quantity that matters is coin held per fully diluted share, marked at the current price, alongside the operating business valued separately on its own cash flows. Everything else, including the market's premium to that net asset value, is a second question that only makes sense once the first is measured.
The convertible ladder is where the risk actually sits
Most of these balance sheets are funded partly with convertible notes, and the marketing describes them as low coupon and therefore cheap. Coupon is the least interesting term in the document.
Build the ladder from the indentures with five columns per instrument. Principal outstanding. Stated maturity. Investor put date, which is frequently years earlier than maturity and is the real date, because holders will exercise it whenever the conversion option is out of the money. Conversion price against the current share price, which tells you whether the instrument is behaving as equity or as debt. And settlement mechanics, meaning whether the issuer may settle in shares, must settle in cash, or elects a combination, since a cash settlement obligation at a put date is a hard liquidity event and a share settlement is dilution instead.
Then run the ladder against a drawdown. If the coin price falls by half, the conversion options move out of the money together, every put date becomes live, and the company faces cash obligations at precisely the moment its only liquid asset has halved and its ability to issue equity has evaporated. That correlation between the funding stress and the asset stress is the structural feature of these vehicles, and it is what separates them from holding the asset directly. Write the scenario out with dates and amounts, because it is not visible from any summary metric.
Standing issuance authority and your per-share claim
The fourth check is the one most often skipped, and it is the cheapest to run.
Establish how many shares the board can issue tomorrow without asking anyone. That means the remaining capacity under any at-the-market programme, the size of any effective shelf registration, the authorised but unissued share count, and any standing shareholder authority to disapply pre-emption rights. The total is the dilution that requires no further approval.
Then apply the only test that matters for accretion. Issuing shares above net asset value per share raises coin per share for existing holders. Issuing below it lowers coin per share, whatever the total holdings figure does. A company that keeps announcing record total holdings while issuing at a discount to net asset value is transferring value away from you and reporting it as growth, and the total holdings figure will never reveal it. Track coin per fully diluted share as a time series and the answer is immediate.
The document set and the refresh trigger
Five documents cover all four checks. The latest annual report for the accounting policy and custody description. Each convertible indenture for the ladder. The most recent shelf and any at-the-market programme filing for issuance capacity. The proxy or equivalent for standing authorities. And the quarterly holdings updates for the coin per share series.
Refresh on filing events rather than on a calendar. A new indenture, a new shelf, an amendment or a change in custodian each triggers a re-run for that name, and the position sizing should be revisited on the same trigger. These structures change faster than a quarterly review cycle, and a diligence file that is three amendments out of date is not a diligence file, it is a record of what was true once.