A full-sample correlation is an average over every state of the world in the estimation window. That is a reasonable summary and a poor risk input, because a book does not lose money in the average state. It loses money in a specific state, and the only question a risk process should be asking of a correlation matrix is what the relationships look like conditional on that state having arrived.
The standard tool is exceedance correlation. Condition on one variable, usually the market factor, being in a defined tail, then compute the correlation of the pair within that subsample. In an alt book the natural conditioning variable is Bitcoin, and the natural threshold is the worst decile of daily returns over the window. What comes back is frequently a different matrix, and the gap between it and the headline is the thing worth reporting.
What the panel prints, and what it leaves open
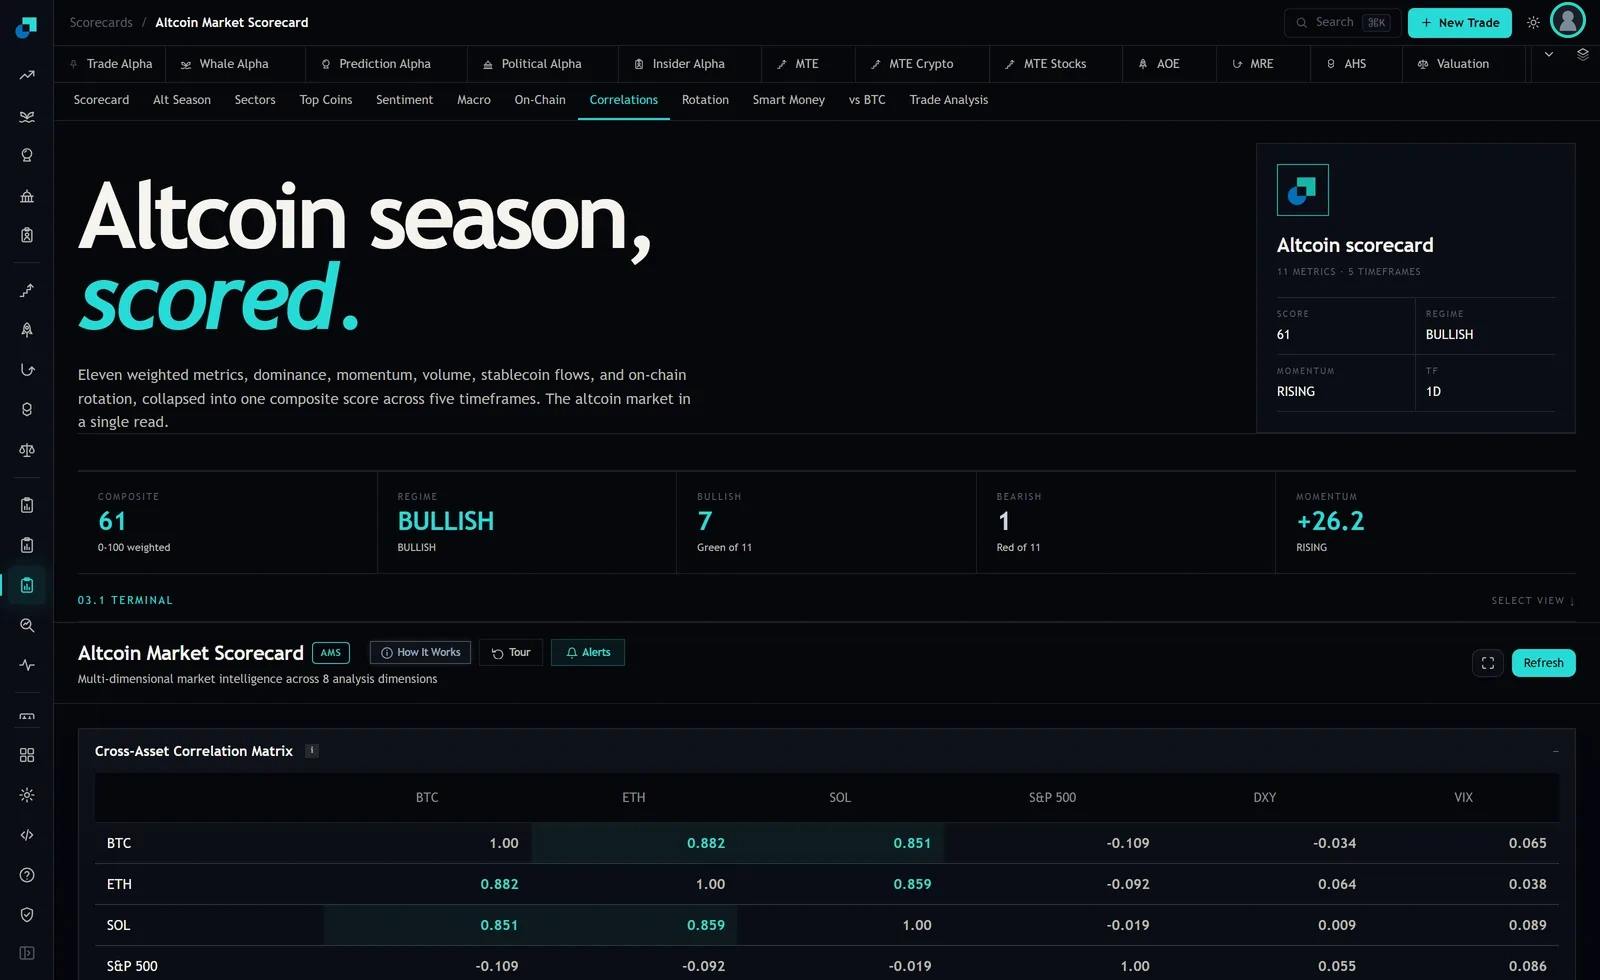
The Correlations tab shows a Cross-Asset Correlation Matrix over BTC, ETH, SOL, S&P 500, DXY and VIX. The crypto block runs BTC to ETH 0.882, BTC to SOL 0.851, ETH to SOL 0.859. The cross terms are small, with BTC against the S&P 500 at minus 0.109, against DXY at minus 0.034, against VIX at 0.065.
Two things about that panel need saying before anything is built on it. There is no estimation window stated on the surface, and I cannot confirm any control that switches the matrix to a conditional or exceedance basis. Treat what is displayed as a full-sample estimate over an unknown lookback. Useful as a cross-check on your own pipeline's unconditional numbers, not sufficient as a tail risk input, and not something to quote in a risk document until the window is established from the module's How It Works control or from whoever maintains it.
Computing the conditional matrix without fooling yourself
The procedure is simple and the statistics are not, so take the traps in order.
Sample size is the first constraint. The worst decile of a 250 day window is 25 observations. The rough standard error of a correlation estimate is one minus r squared, divided by the square root of n minus one. At an estimated 0.5 on 25 points that is about 0.15, which means a reading of 0.5 and a reading of 0.8 are not cleanly distinguishable. Either use a multi-year window, or pool across names with a shared structure, or accept that you are producing a band rather than a point.
The Gaussian benchmark is the trap most desks fall into. Conditioning on one variable being extreme truncates that variable's variance in the subsample, and that alone pushes the measured correlation down. For jointly normal returns with a constant underlying correlation, exceedance correlation computed this way falls toward zero as the threshold gets more extreme. So the null hypothesis is not that the conditional and unconditional numbers match. The null is that the conditional number is somewhat lower. A tail correlation that comes back merely equal to the headline is already evidence of tail dependence, and one that comes back higher is strong evidence.
This inverts the naive reading of the assignment. A crypto pair whose exceedance correlation prints at 0.95 against a full sample of 0.86 has not moved a little. Against the correct benchmark it has moved a lot.
Conditioning variable choice changes the answer. Conditioning on Bitcoin gives you crypto stress. Conditioning on equity drawdown gives you cross-asset stress, and those are different events with different implications for an allocator. Run both, label them separately, and never let the two get averaged into a single tail matrix.
Synchronisation matters more here than in the full sample. Crypto trades continuously and equities do not. A stale equity close paired against a crypto return that includes the overnight move will bias cross-asset tail readings toward zero. Align to a common daily cut and state it.
The figure to put in front of a committee
When the conditional and full-sample matrices disagree materially, showing the committee two matrices is the wrong answer. Nobody in that room is going to difference thirty cells in their head, and the discussion will collapse into an argument about which matrix is right.
Show one number instead. Hold weights and individual volatilities fixed, revalue portfolio risk under the exceedance matrix in place of the full-sample matrix, and report the change in one day 99 percent value at risk in basis points of net asset value. That is the stressed correlation increment, and it has the properties a governance number needs. It is a single figure, it is in units the committee already uses, it is reproducible from inputs you can hand to anyone, and it converts a statistical disagreement into a loss statement.
Put two supporting lines under it and nothing else. The effective number of bets under each matrix, computed as the reciprocal of the first eigenvalue's variance share, because that translates the change into a diversification claim. And the observation count in the conditional sample, because a committee is entitled to know that the alarming number rests on twenty five days.
Where the difference is large, the decision that follows is a sizing decision, not a modelling one. If the tail matrix says the book is worth one independent bet when the headline said three, the position limits were set against a diversification that does not exist in the state the limits are for.
Documenting the disagreement so it survives review
The reason to formalise this is what happens after a drawdown. The predictable exchange in a post mortem is that risk reports showed acceptable correlation and the market behaved without precedent. A conditional matrix computed monthly and stored kills that exchange in both directions.
If the stressed increment was already elevated going in, the loss was foreseeable from the desk's own reporting and the honest finding is that limits were wrong. If it was not elevated, and the tail relationships genuinely broke new ground, you have a dated record demonstrating that, which is a materially stronger position than an assertion after the fact.
Store the inputs, not just the output. Window, threshold definition, conditioning asset, observation count, and the weights used in the revaluation. A stressed VaR increment that cannot be reproduced six months later is decoration.
When the conditional estimate is too weak to act on
Be willing to say the number is not strong enough. With a short history, a thin conditional sample and a wide standard error, an exceedance correlation can be genuinely uninformative, and reporting it with false precision is worse than not reporting it.
The fallback in that case is not to fall back on the full-sample matrix, which is the tempting move and the wrong one. It is to size on an assumed stress correlation rather than an estimated one. Pick a conservative value, state it as an assumption in the risk policy, and revisit it when the data supports something better. An assumption you have written down and defended beats an estimate whose confidence interval spans the entire decision.