There is a spreadsheet on most macro desks with three columns in it. Fed assets, the Treasury General Account, and the overnight reverse repo facility. Subtract the second and third from the first and you have net liquidity, the most widely used back-of-envelope in the business. It earned that status honestly, because for a stretch it captured the mechanism that actually mattered. The problem with identities is that they keep producing numbers long after the mechanism has moved, and this one has a term that has stopped doing any work.
What the three terms were each doing
The formula is not a model. It is an accounting approximation of one variable, which is the level of bank reserves in the system, assembled from three published series that were easier to get daily than reserves themselves.
Fed assets are the supply side. Purchases put reserves into the banking system, runoff takes them out.
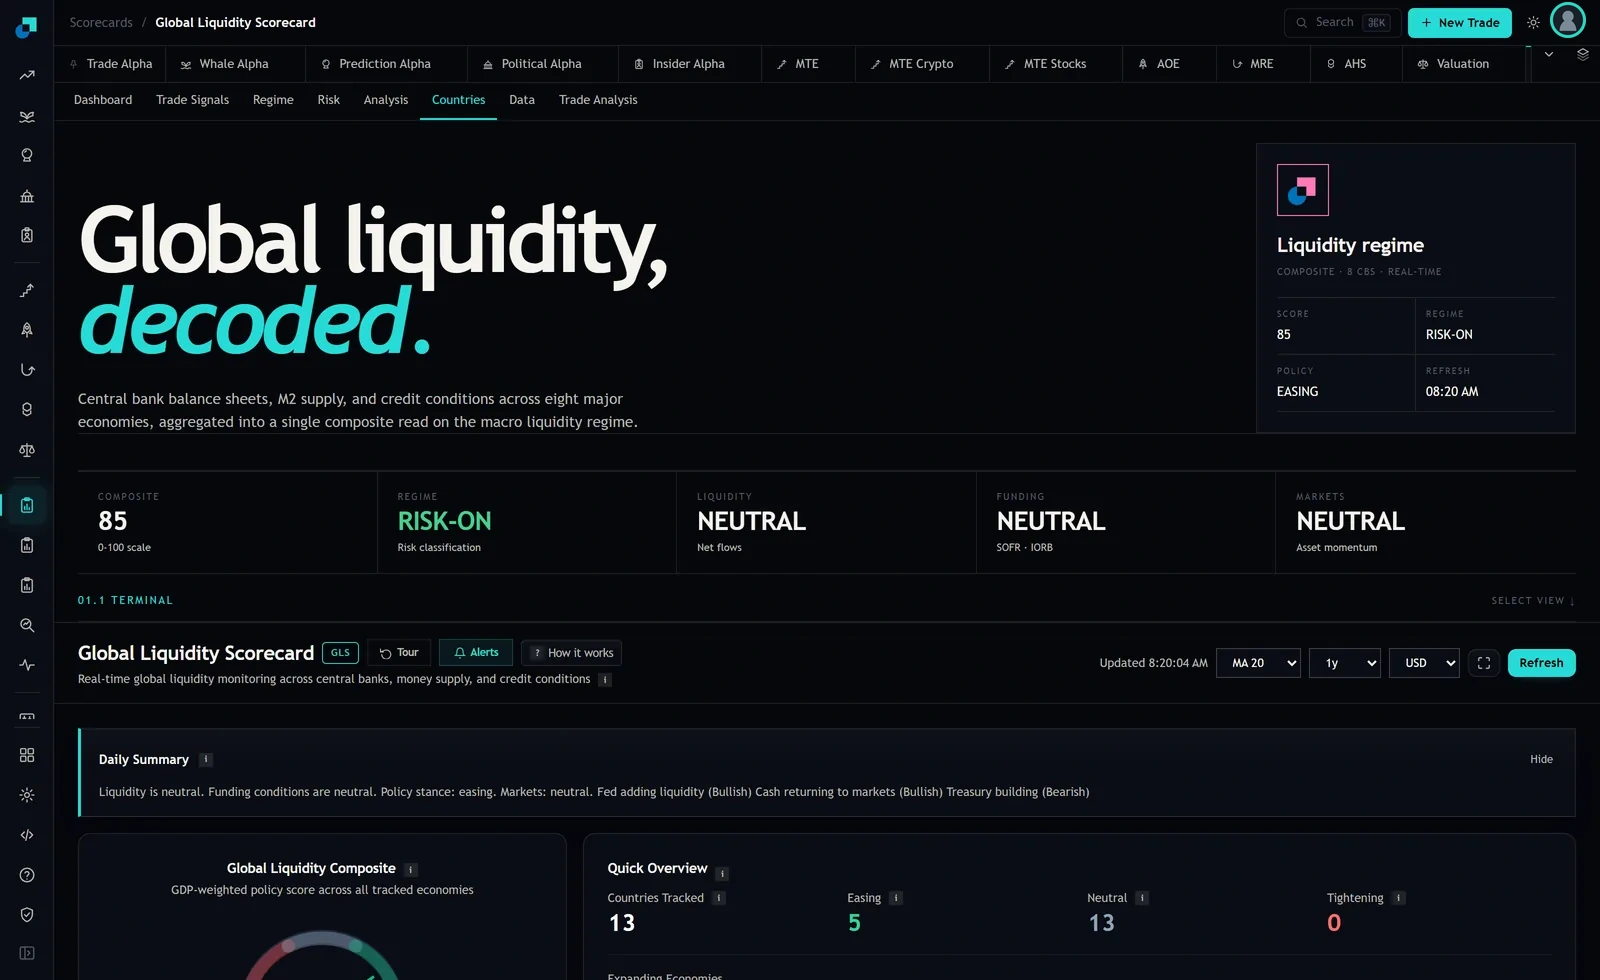
The Treasury General Account is the Treasury's own account at the Fed. When the Treasury issues more than it spends and the account builds, money leaves the private banking system and sits at the central bank. That is a drain, and it is why the third field of the module's Daily Summary reads exactly the way it does, tagging Treasury building as bearish.
The reverse repo facility was the shock absorber. Money market funds parked cash there, and crucially that cash could be released. When the Treasury drained the system by rebuilding its account, funds could pull money out of the facility to buy the bills, and reserves barely moved. That is the whole reason balance sheet runoff was survivable for as long as it was. There was a buffer, and the buffer was being consumed instead of reserves.
What breaks when one term sits on its floor
A facility that has run down toward its floor does not break the arithmetic. It breaks the inference, in two distinct ways, and the second is the dangerous one.
The obvious failure is that a term with no variance contributes no information. Your daily change in net liquidity is now driven entirely by the other two series. The formula has quietly become a two-term formula and nobody edited the header row.
The failure that costs money is about pass-through. When the buffer had cash in it, a Treasury account rebuild drained the facility rather than reserves. With the buffer gone, the same rebuild hits reserves close to one for one. The coefficient on your TGA term has changed even though the term itself looks identical in the spreadsheet. Every historical relationship you estimated between net liquidity and asset prices was estimated in the world where the buffer existed, and you are now applying it in a world where it does not.
That is the general lesson worth extracting. Formulas do not fail loudly. They keep returning plausible values, and the failure appears as a slow degradation in the relationship you were relying on, which is exactly the pattern you will attribute to noise for several months.
Before acting on any of this, check the current level of the facility yourself. I am describing a maintenance rule and the structural consequence of the buffer being consumed, not publishing a reading. The point holds whenever a term approaches its floor, and the date it did so is not the interesting part.
What belongs in the third slot now
Three candidates, and I think the choice is clear once you remember what the formula was approximating.
The first candidate is nothing at all. Drop the third term and use bank reserves directly as the level variable. This is the honest answer, because reserves were always the target and the three-term construction was a convenience born of wanting a daily series. Reserves are published, they are the actual quantity that determines whether the funding market is comfortable, and using them removes the approximation error entirely. The cost is frequency and lag relative to a daily-updating identity, which is a real cost and a smaller one than being wrong about the mechanism.
The second candidate is standing facility usage on the lending side. If the absorbing facility is empty, the informative facility is the one banks go to when they need reserves rather than when they have too many. Usage there is a scarcity indicator rather than an abundance one, and it belongs in the framework, but not as a subtracted level term. It is a discrete event series, and events do not subtract cleanly from a stock.
The third candidate, and the one I would actually adopt alongside reserves, is not a level term at all. It is the price. Put the funding spread in as a state variable that conditions how you read the level, rather than as another quantity you subtract.
Why the price belongs where the quantity used to be
The strip across the top of the Global Liquidity Scorecard already makes this argument. FUNDING sits there as its own field, currently reading NEUTRAL, with its sub-label naming the SOFR and IORB relationship. That is the price of overnight funding against the rate the central bank pays on reserves, and it is the market's own assessment of whether reserves are ample.
The advantage of a price over a quantity here is that nobody knows the level of reserves that counts as ample. It depends on regulation, on intraday payment needs and on how reserves are distributed across institutions rather than on the aggregate. The threshold is unobservable and it moves. The spread, by contrast, is the system telling you directly, and it does not require you to have guessed the threshold correctly.
So the revised framework is two lines rather than three. Reserves as the level. The funding spread as the state that tells you whether that level is currently comfortable. When the spread is quiet, changes in the level are informative in the ordinary slow way. When the spread widens and its daily prints get dispersed, the level has become the only thing that matters and everything else in your macro framework is a second-order consideration.
The maintenance rule this implies for every other identity you run
Generalise it, because this will happen again with a different term.
For every composed indicator on the desk, write down what each term is a proxy for, not just what it is. Then add a monitoring rule. Any term that has sat within a stated distance of a structural floor or ceiling for a stated number of months gets flagged for review, on the grounds that a variable with no variance is either uninformative or has changed the meaning of its neighbours.
Review the composition annually and record the review even when nothing changes. And when a term does get retired, keep the old series computed alongside the new one for a year, so the break in your history is visible and dated rather than discovered later by somebody wondering why a relationship changed character in a particular quarter.
One caveat on reading this across to the module. The Global Liquidity Scorecard publishes its input families rather than its construction, so I cannot tell you whether its composite has been maintained for the same reason, and I am not going to assume either way. What I can tell you is that the driver tags in its Daily Summary still name all three of the forces the classic identity used, which makes it a useful place to see the decomposition even while you rebuild your own version of the arithmetic underneath.